Business Accounting Templates Switzerland
The Business accounting templates have chart of accounts based on the SME system (Swiss SME chart of accounts - Sterchi, Mattle, Helbing), in compliance with the Swiss Code of Obligations (articles 957-963b CO).
They are mainly divided into:
- Cash method -based accounting – Costs and revenues are recorded at the time of payment and receipt.
- Accrual method-based accounting – Costs and revenues are recorded at the time of issuing invoices to customers and receiving invoices from suppliers.
Additionally, templates are included to manage accounts in both the base currency and foreign currencies.
Work quickly with automation features
The program includes many automation features that allow you to work quickly and securely.
- Reuse previously entered texts
Easily reuse previously entered content without having to retype it manually. - Retrieve data from stored transactions
You can store recurring transactions in a table and retrieve them with a click, without having to re-enter the text - Import bank, postal, and credit card data
Effortlessly integrate bank, postal, and credit card data into your accounting. Numerous import formats are available to automatically retrieve the data. - VAT calculations and summaries
Automate VAT calculations and summaries for error-free tax management. - Foreign currencies
Easily account for transactions in different currencies, including cryptocurrencies. Fixed and variable exchange rates. Automated exchange rate differences. - Balance sheets, account ledgers, journals, and other reports
Generate detailed balance sheets, account ledgers, journals, and other reports with just one click. - Cost/Profit Centers and Segments
Used to analyze and monitor the performance of different areas or divisions of a company. - Invoice creation with QR codes, reminders, quotes, and delivery notes
Create invoices in a few steps, which you can integrate into your accounting file for automatic entry. If you need to create highly detailed and extensive invoices, use the features of the Estimates and Invoices application. - File checks and security
Various control functions immediately alert you to discrepancies in opening balances, transactions, bank accounts, errors in the chart of accounts, and much more. - File conversion from one type of accounting to another
If your accounting needs change, you can always convert your data into a different type of accounting file (for example, from double-entry accounting without VAT to one with VAT).
These features are included in the Professional plan. If you're looking for even more efficiency and speed in accounting work, the Advanced plan offers innovative automations to further optimize your workflow.
- Bank data import using Rules
For a complete import without the need to manually enter counterpart accounts, VAT codes, cost centers, and more. - Creation of VAT Statement facsimile, both in paper and XML format, for electronic submission to the AFC
No more manual calculations to sum the amounts for different VAT codes, as everything is automated. - Temporary filtering and sorting of rows
Quickly search for data without navigating from one row to another. You can directly correct or modify the filtered rows. Once done, by removing the filter, the data will return to its previous order. - All your accounting PDF attachments in a single file
This allows you to save and archive all documents in one file. It is highly useful and convenient, especially for audits and tax reviews. - E-banking payments
You can create payments for your suppliers within your accounting file or separately, without the need to manually prepare payment transfers. - Extensions for maximum invoice customization
Offers greater flexibility to customize the position of logos, addresses, and texts. - Balance sheet and cash flow analysis
Evaluate the financial health of your company, monitor liquidity, and identify critical areas to intervene promptly. Use these analyses to plan effective strategies that improve business performance and ensure sustainable growth. - Financial forecasts and budgeting
Anticipate the financial performance to ensure the availability of necessary liquidity, plan targeted investments, and reduce waste. Optimize revenues and ensure efficient resource management, allowing you to make informed decisions and maintain financial control over your company.
Tutorial
On the Tutorial pages, you will find step-by-step instructions on how to set up the file, record transactions, create invoices, import transactions using rules, and generate the balance sheet. The explanations are accompanied by images taken from sample files in the Banana program.
You can download the tutorial file, which contains not only the chart of accounts but also opening balances and sample entries. You can, of course, customize the file by changing the opening balances and replacing the sample transactions with your own.
Complete multilingual Swiss SME chart of accounts (for reference only)
In this article
Complete multilingual Swiss SME chart of accounts (for reference only)
Complete multilingual Swiss SME chart of accounts (for reference only)
Presentation of the complete and multilingual SME accounts template. Template to be used only to see the complete list of all SME accounts. It is particularly useful when you want to add new accounts to your chart of accounts; in this case, just open the template and check the numbering to enter the correct account number, according to the rules of the Swiss Code of Obligations.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
Do not use this template to create a new accounting, but use a chart of accounts specific to your legal entity type.
Introduction
This chart of accounts template contains all the accounts and groups listed in the manual of the Swiss SME Accounting System by Sterchi, Mattle, Helbing.
We have also translated all the account descriptions into different languages, and in the liabilities section, there are all the accounts related to Share Capital/Equity, depending on the legal form of the company.
The columns and the headings of the file are in German; to change the language of the file go to the page Convert to new file.
The SME chart of accounts has been updated following the amendments to the Swiss Code of Obligations that came into force on the January 1, 2023.
List of accounts and groups
All accounts and groups are listed below for reference purposes. See also (KMU Deutsch, PME Francais, PMI Italiano).
The account preview below is in English, but the other languages are also available in the file.
Template preview
| Group | Account | Description | BClass | Sum In |
|---|---|---|---|---|
| Swiss chart of accounts for SME | ||||
| BALANCE SHEET | ||||
| ASSETS | ||||
| 1000 | Cash on hand A | 1 | 100 | |
| 1005 | Cash on hand in foreign currency A | 1 | 100 | |
| 1020 | Bank account A | 1 | 100 | |
| 1025 | Bank account in foreign currency A | 1 | 100 | |
| 1040 | Cheques | 1 | 100 | |
| 1041 | Promissory notes to collect | 1 | 100 | |
| 1045 | Credit cards / Debit cards | 1 | 100 | |
| 1050 | Short-term deposit investments | 1 | 100 | |
| 1051 | Short-term fiduciary investments | 1 | 100 | |
| 100 | Cash and cash equivalents | 10 | ||
| 1060 | Stocks (listed) | 1 | 106 | |
| 1061 | Participation certificates (listed) | 1 | 106 | |
| 1062 | Investment funds (listed) | 1 | 106 | |
| 1063 | Bonds (listed) | 1 | 106 | |
| 1064 | Cryptocurrencies | 1 | 106 | |
| 1068 | Short-term securities fluctuation reserve | 1 | 106 | |
| 1069 | Short-term securities value adjustments | 1 | 106 | |
| 1070 | Financial derivatives | 1 | 106 | |
| 1078 | Other short-term assets fluctuation reserve | 1 | 106 | |
| 1079 | Other short-term assets value adjustments | 1 | 106 | |
| 106 | Short-term assets listed on the stock exchange | 10 | ||
| 1090 | Internal transfers | 1 | 109 | |
| 1091 | Transfer account for salaries | 1 | 109 | |
| 1099 | Clarification account | 1 | 109 | |
| 109 | Transfer accounts | 10 | ||
| 1100 | Receivables Switzerland | 1 | 110 | |
| 1101 | Receivables abroad | 1 | 110 | |
| 1102 | Receivables abroad in foreign currency | 1 | 110 | |
| 1109 | Receivables towards third parties value adjustments | 1 | 110 | |
| 1110 | Receivables towards subsidiary A | 1 | 110 | |
| 1119 | Receivables towards group companies value adjustments | 1 | 110 | |
| 1120 | Receivables towards person involved A | 1 | 110 | |
| 1121 | Receivables towards member of the Board of Directors A | 1 | 110 | |
| 1122 | Receivables towards member of Executive Board A | 1 | 110 | |
| 1123 | Receivables towards group company A | 1 | 110 | |
| 1124 | Receivables towards close person A | 1 | 110 | |
| 1125 | Receivables towards auditor | 1 | 110 | |
| 1129 | Receivables towards shareholders value adjustments | 1 | 110 | |
| 110 | Receivables from deliveries and services | 10 | ||
| 1140 | Advances and loans | 1 | 114 | |
| 1149 | Other short-term receivables towards third parties value adjustments | 1 | 114 | |
| 1150 | Loans to subsidiary A | 1 | 114 | |
| 1159 | Other short-term receivables towards group companies value adjustments | 1 | 114 | |
| 1160 | Loans to person involved A | 1 | 114 | |
| 1161 | Loans to member of the Board of Directors A | 1 | 114 | |
| 1162 | Loans to member of Executive Board A | 1 | 114 | |
| 1163 | Loans to group company A | 1 | 114 | |
| 1164 | Loans to close person A | 1 | 114 | |
| 1169 | Other loans to shareholders value adjustments | 1 | 114 | |
| 1170 | Input tax on materials, goods, services and energy, cl. 4 | 1 | 114 | |
| 1171 | Input tax on investments, remaining operating expenses, cl. 1/5-8 | 1 | 114 | |
| 1172 | Input tax compensation under the reporting method | 1 | 114 | |
| 1173 | Input tax reduction | 1 | 114 | |
| 1174 | Input tax correction | 1 | 114 | |
| 1175 | Settlement account VAT | 1 | 114 | |
| 1176 | Withholding tax | 1 | 114 | |
| 1177 | Receivables towards Directorate General of Customs | 1 | 114 | |
| 1178 | Direct taxes | 1 | 114 | |
| 1179 | Tax at source | 1 | 114 | |
| 1180 | AHV, IV, EO, ALV current account | 1 | 114 | |
| 1181 | Current account family allowance fund | 1 | 114 | |
| 1182 | Current account pension funds | 1 | 114 | |
| 1183 | Current account accident insurance | 1 | 114 | |
| 1184 | Daily sickness benefits insurance current account | 1 | 114 | |
| 1190 | WIR accounts | 1 | 114 | |
| 1191 | Deposits | 1 | 114 | |
| 1192 | Advance payments to suppliers | 1 | 114 | |
| 1193 | Rent deposits | 1 | 114 | |
| 1199 | Other short-term receivables value adjustments | 1 | 114 | |
| 114 | Other short-term receivables | 10 | ||
| 1200 | Inventories of commercial products A | 1 | 120 | |
| 1207 | Change in commercial product inventories | 1 | 120 | |
| 1208 | Advance payments for commercial products | 1 | 120 | |
| 1209 | Commercial products inventories value adjustments | 1 | 120 | |
| 1210 | Inventories of raw materials A | 1 | 120 | |
| 1217 | Change in raw materials | 1 | 120 | |
| 1218 | Advance payments for raw materials | 1 | 120 | |
| 1219 | Raw material inventories value adjustments | 1 | 120 | |
| 1220 | Inventories of finished products | 1 | 120 | |
| 1221 | Inventories of semi-finished products | 1 | 120 | |
| 1227 | Change in production material | 1 | 120 | |
| 1228 | Advance payments for production material | 1 | 120 | |
| 1229 | Production material inventories value adjustments | 1 | 120 | |
| 1230 | Auxiliary material inventories | 1 | 120 | |
| 1231 | Consumables inventories | 1 | 120 | |
| 1232 | Packaging inventories | 1 | 120 | |
| 1237 | Change in auxiliary material and consumables | 1 | 120 | |
| 1238 | Advance payments for auxiliary material and consumables | 1 | 120 | |
| 1239 | Auxiliary material and consumables value adjustments | 1 | 120 | |
| 1240 | Compulsory inventories | 1 | 120 | |
| 1247 | Changes in compulsory inventories | 1 | 120 | |
| 1249 | Compulsory inventories value adjustments | 1 | 120 | |
| 1250 | Goods on delivery | 1 | 120 | |
| 1257 | Changes in goods on delivery | 1 | 120 | |
| 1259 | Goods on delivery value adjustments | 1 | 120 | |
| 1260 | Finished products | 1 | 120 | |
| 1267 | Changes in finished products | 1 | 120 | |
| 1269 | Finished products value adjustments | 1 | 120 | |
| 1270 | Semi-finished products | 1 | 120 | |
| 1277 | Changes in semi-finished products | 1 | 120 | |
| 1279 | Semi-finished products value adjustments | 1 | 120 | |
| 1280 | Non-invoiced services | 1 | 120 | |
| 1287 | Changes in non-invoiced services | 1 | 120 | |
| 1289 | Non-invoiced services value adjustments | 1 | 120 | |
| 120 | Inventories and non-invoiced services | 10 | ||
| 1300 | Prepaid expenses | 1 | 130 | |
| 1301 | Accrued income | 1 | 130 | |
| 1303 | Discount on liabilities | 1 | 130 | |
| 130 | Accrued income and prepaid expenses | 10 | ||
| 10 | Current assets | 1 | ||
| 1400 | Stocks | 1 | 140 | |
| 1401 | Participation certificates | 1 | 140 | |
| 1402 | Investment funds | 1 | 140 | |
| 1403 | Bonds | 1 | 140 | |
| 1404 | Cryptocurrencies (Investments) | 1 | 140 | |
| 1408 | Fixed assets securities fluctuation reserve | 1 | 140 | |
| 1409 | Fixed assets securities value adjustments | 1 | 140 | |
| 1410 | Long-term financial investments | 1 | 140 | |
| 1411 | Rent deposits | 1 | 140 | |
| 1419 | Other financial investments value adjustments | 1 | 140 | |
| 1440 | Loans | 1 | 140 | |
| 1441 | Mortgages | 1 | 140 | |
| 1449 | Long-term receivables towards third parties value adjustments | 1 | 140 | |
| 1450 | Loans to participation A | 1 | 140 | |
| 1451 | Mortgages to participation A | 1 | 140 | |
| 1459 | Long-term receivables towards participations value adjustments | 1 | 140 | |
| 1460 | Loans/Mortgages to person involved A | 1 | 140 | |
| 1461 | Loans/Mortgages to member of the Board of Directors A | 1 | 140 | |
| 1462 | Loans/Mortgages to member of Executive Board A | 1 | 140 | |
| 1463 | Loans/Mortgages to group company A | 1 | 140 | |
| 1464 | Loans/Mortgages to close person A | 1 | 140 | |
| 1469 | Long-term receivables towards shareholders value adjustments | 1 | 140 | |
| 1470 | Employer contribution reserve | 1 | 140 | |
| 140 | Financial assets | 14 | ||
| 1480 | Participation A | 1 | 148 | |
| 1489 | Participations value adjustments | 1 | 148 | |
| 148 | Participations | 14 | ||
| 1500 | Machinery and equipment | 1 | 150 | |
| 1501 | Production plants | 1 | 150 | |
| 1507 | Leased machinery and equipment | 1 | 150 | |
| 1508 | Advance payments for machinery and equipment | 1 | 150 | |
| 1509 | Depreciation and value adjustments to machinery and equipment | 1 | 150 | |
| 1510 | Furniture and installations | 1 | 150 | |
| 1511 | Workshop installations | 1 | 150 | |
| 1512 | Shop installations | 1 | 150 | |
| 1513 | Office furniture | 1 | 150 | |
| 1517 | Leased furniture and installations | 1 | 150 | |
| 1518 | Advance payments for furniture and installations | 1 | 150 | |
| 1519 | Depreciation and value adjustments to furniture and installations | 1 | 150 | |
| 1520 | Office machines | 1 | 150 | |
| 1521 | Information technology | 1 | 150 | |
| 1522 | Communication technology | 1 | 150 | |
| 1527 | Leased office machines, information and communication technology | 1 | 150 | |
| 1528 | Advance payments for office machines, information and communication technology | 1 | 150 | |
| 1529 | Depreciation and value adjustments to office machines, information and communication technology | 1 | 150 | |
| 1530 | Vehicle A | 1 | 150 | |
| 1537 | Leased vehicles | 1 | 150 | |
| 1538 | Advance payments for vehicles | 1 | 150 | |
| 1539 | Depreciation and value adjustments to vehicles | 1 | 150 | |
| 1540 | Tools and equipment | 1 | 150 | |
| 1547 | Leased tools and equipment | 1 | 150 | |
| 1548 | Advance payments for tools and equipment | 1 | 150 | |
| 1549 | Depreciation and value adjustments to tools and equipment | 1 | 150 | |
| 1550 | Storage facilities | 1 | 150 | |
| 1557 | Leased storage facilities | 1 | 150 | |
| 1558 | Advance payments for storage facilities | 1 | 150 | |
| 1559 | Depreciation and value adjustments to storage facilities | 1 | 150 | |
| 1570 | Fixed facilities | 1 | 150 | |
| 1571 | Installations | 1 | 150 | |
| 1572 | Movable structures | 1 | 150 | |
| 1577 | Leased fixed facilities and installations | 1 | 150 | |
| 1578 | Advance payments for fixed facilities and installations | 1 | 150 | |
| 1579 | Depreciation and value adjustments to fixed facilities and installations | 1 | 150 | |
| 1590 | Linen and work clothing | 1 | 150 | |
| 1591 | Moulds and models | 1 | 150 | |
| 1597 | Other leased movable tangible assets | 1 | 150 | |
| 1598 | Advance payments for other movable tangible assets | 1 | 150 | |
| 1599 | Depreciation and value adjustments to other movable tangible assets | 1 | 150 | |
| 150 | Movable tangible assets | 14 | ||
| 1600 | Commercial properties | 1 | 160 | |
| 1601 | Commercial properties land | 1 | 160 | |
| 1606 | Commercial properties renovation | 1 | 160 | |
| 1607 | Leased commercial properties | 1 | 160 | |
| 1608 | Advance payments for commercial properties | 1 | 160 | |
| 1609 | Depreciation and value adjustments to commercial properties | 1 | 160 | |
| 1610 | Factories | 1 | 160 | |
| 1611 | Factories land | 1 | 160 | |
| 1617 | Leased factories | 1 | 160 | |
| 1618 | Advance payments for factories | 1 | 160 | |
| 1619 | Depreciation and value adjustments to factories | 1 | 160 | |
| 1620 | Workshops and ateliers | 1 | 160 | |
| 1621 | Workshops and ateliers land | 1 | 160 | |
| 1627 | Leased workshops and ateliers | 1 | 160 | |
| 1628 | Advance payments for workshops and ateliers | 1 | 160 | |
| 1629 | Depreciation and value adjustments to workshops and ateliers | 1 | 160 | |
| 1630 | Warehouses | 1 | 160 | |
| 1631 | Warehouses land | 1 | 160 | |
| 1637 | Leased warehouses | 1 | 160 | |
| 1638 | Advance payments for warehouses | 1 | 160 | |
| 1639 | Depreciation and value adjustments to warehouses | 1 | 160 | |
| 1640 | Exhibition buildings | 1 | 160 | |
| 1641 | Sales buildings | 1 | 160 | |
| 1642 | Sales buildings land | 1 | 160 | |
| 1647 | Leased exhibition and sales buildings | 1 | 160 | |
| 1648 | Advance payments for exhibition and sales buildings | 1 | 160 | |
| 1649 | Depreciation and value adjustments to exhibition and sales buildings | 1 | 160 | |
| 1650 | Office and administration buildings | 1 | 160 | |
| 1652 | Office and administration buildings land | 1 | 160 | |
| 1657 | Leased office and administration buildings | 1 | 160 | |
| 1658 | Advance payments for office and administration buildings | 1 | 160 | |
| 1659 | Depreciation and value adjustments to office and administration buildings | 1 | 160 | |
| 1660 | Staff housing | 1 | 160 | |
| 1661 | Other residential buildings | 1 | 160 | |
| 1662 | Other residential buildings land | 1 | 160 | |
| 1667 | Leased residential buildings | 1 | 160 | |
| 1668 | Advance payments for residential buildings | 1 | 160 | |
| 1669 | Depreciation and value adjustments to residential buildings | 1 | 160 | |
| 1680 | Undeveloped land | 1 | 160 | |
| 1687 | Leased undeveloped land | 1 | 160 | |
| 1688 | Advance payments for undeveloped land | 1 | 160 | |
| 1689 | Depreciation and value adjustments to undeveloped land | 1 | 160 | |
| 160 | Fixed tangible assets | 14 | ||
| 1700 | Patents | 1 | 170 | |
| 1701 | Know-how | 1 | 170 | |
| 1702 | Recipes | 1 | 170 | |
| 1709 | Depreciation and value adjustments to patents, know-how and recipes | 1 | 170 | |
| 1710 | Brands | 1 | 170 | |
| 1711 | Samples | 1 | 170 | |
| 1712 | Models | 1 | 170 | |
| 1713 | Plans | 1 | 170 | |
| 1719 | Depreciation and value adjustments to brands, samples, models and plans | 1 | 170 | |
| 1720 | Licences | 1 | 170 | |
| 1721 | Concessions | 1 | 170 | |
| 1722 | Rights of use | 1 | 170 | |
| 1723 | Company rights | 1 | 170 | |
| 1729 | Depreciation and value adjustments to licences, concessions, rights of use and company rights | 1 | 170 | |
| 1730 | Copyrights | 1 | 170 | |
| 1731 | Publishing rights | 1 | 170 | |
| 1732 | Contractual rights | 1 | 170 | |
| 1739 | Depreciation and value adjustments to copyrights, publishing rights and contractual rights | 1 | 170 | |
| 1740 | In-house developed software | 1 | 170 | |
| 1741 | Purchased software and licences | 1 | 170 | |
| 1749 | Depreciation and value adjustments to software | 1 | 170 | |
| 1750 | Own development | 1 | 170 | |
| 1751 | Purchased development | 1 | 170 | |
| 1759 | Depreciation and value adjustments to development | 1 | 170 | |
| 1770 | Goodwill | 1 | 170 | |
| 1779 | Depreciation and value adjustments to goodwill | 1 | 170 | |
| 1790 | Other intangible assets | 1 | 170 | |
| 1799 | Depreciation and value adjustments to other intangible assets | 1 | 170 | |
| 170 | Intangible assets | 14 | ||
| 1850 | Unpaid share capital | 1 | 180 | |
| 1850(2) | Unpaid nominal capital | 1 | 180 | |
| 1850(3) | Unpaid participation certificate capital | 1 | 180 | |
| 1850(4) | Unpaid foundation capital | 1 | 180 | |
| 1851 | Unpaid participation capital | 1 | 180 | |
| 180 | Unpaid share capital or foundation capital | 14 | ||
| 14 | Fixed assets | 1 | ||
| 1 | Total assets | 00 | ||
| LIABILITIES | ||||
| 2000 | Costs of materials and goods payables | 2 | 200 | |
| 2001 | Third-party/subcontracted services payables | 2 | 200 | |
| 2002 | Personnel expenses payables | 2 | 200 | |
| 2004 | Other operating expenses payables | 2 | 200 | |
| 2030 | Advance payments from third parties | 2 | 200 | |
| 2050 | Payables due to participation A | 2 | 200 | |
| 2060 | Payables due to person involved A | 2 | 200 | |
| 2061 | Payables due to member of the Board of Directors A | 2 | 200 | |
| 2062 | Payables due to member of Executive Board A | 2 | 200 | |
| 2063 | Payables due to group company A | 2 | 200 | |
| 2064 | Payables due to close person A | 2 | 200 | |
| 2065 | Payables due to auditor | 2 | 200 | |
| 200 | Accounts payable | 20 | ||
| 2100 | Current account A | 2 | 210 | |
| 2107 | Loan A | 2 | 210 | |
| 2109 | Mortgage A | 2 | 210 | |
| 2111 | WIR commitments | 2 | 210 | |
| 2120 | Financial leasing commitments | 2 | 210 | |
| 2130 | Bond loans | 2 | 210 | |
| 2140 | Other onerous debts due to third parties | 2 | 210 | |
| 2150 | Debts due to participation A | 2 | 210 | |
| 2160 | Debts due to person involved A | 2 | 210 | |
| 2161 | Debts due to member of the Board of Directors A | 2 | 210 | |
| 2162 | Debts due to member of Executive Board A | 2 | 210 | |
| 2163 | Debts due to group company A | 2 | 210 | |
| 2164 | Debts due to close person A | 2 | 210 | |
| 2170 | Debts due to pension funds | 2 | 210 | |
| 210 | Short-term interest-bearing debts | 20 | ||
| 2200 | VAT due | 2 | 220 | |
| 2200A | Automatic VAT | 2 | 220 | |
| 2201 | VAT settlement account | 2 | 220 | |
| 2202 | VAT due compensation according to the reporting method | 2 | 220 | |
| 2203 | Acquisition tax | 2 | 220 | |
| 2206 | Withholding tax | 2 | 220 | |
| 2207 | Stamp duty | 2 | 220 | |
| 2208 | Direct taxes | 2 | 220 | |
| 2209 | Tax at source | 2 | 220 | |
| 2210 | Debts due to third parties | 2 | 220 | |
| 2250 | Debts due to participation A | 2 | 220 | |
| 2260 | Debts due to person involved A | 2 | 220 | |
| 2261 | Debts due to member of the Board of Directors A | 2 | 220 | |
| 2262 | Debts due to member of Executive Board A | 2 | 220 | |
| 2263 | Debts due to group company A | 2 | 220 | |
| 2264 | Debts due to close person A | 2 | 220 | |
| 2265 | Debts due to auditor | 2 | 220 | |
| 2269 | Adopted distributions (dividends) | 2 | 220 | |
| 2270 | AHV, IV, EO, ALV current account | 2 | 220 | |
| 2271 | Family allowance fund current account | 2 | 220 | |
| 2272 | Pension funds current account | 2 | 220 | |
| 2273 | Accident insurance current account | 2 | 220 | |
| 2274 | Daily sickness benefits insurance current account | 2 | 220 | |
| 220 | Other short-term debts | 20 | ||
| 2300 | Accrued expenses | 2 | 230 | |
| 2301 | Revenues received in advance | 2 | 230 | |
| 2303 | Receivables discount | 2 | 230 | |
| 2330 | Provisions for warranty commitments | 2 | 230 | |
| 2331 | Provisions for purchase commitments | 2 | 230 | |
| 2340 | Provisions for direct taxes | 2 | 230 | |
| 2341 | Provisions for indirect taxes | 2 | 230 | |
| 2350 | Provisions for repairs and maintenance | 2 | 230 | |
| 2351 | Provisions for renovation of tangible assets | 2 | 230 | |
| 2352 | Provisions for research | 2 | 230 | |
| 2353 | Provisions for development | 2 | 230 | |
| 2354 | Provisions for restructuring | 2 | 230 | |
| 2355 | Provisions for environmental protection measures | 2 | 230 | |
| 2360 | Provisions for threatening losses from ongoing business | 2 | 230 | |
| 2370 | Provisions for pension funds commitments | 2 | 230 | |
| 2371 | Provisions for salary commitments | 2 | 230 | |
| 2380 | Provisions for participations commitments | 2 | 230 | |
| 2381 | Provisions for commitments to shareholders | 2 | 230 | |
| 2390 | Provisions to ensure the lastingly prosperity of the company | 2 | 230 | |
| 2391 | Other short-term provisions | 2 | 230 | |
| 230 | Accruals and deferred income, short-term provisions | 20 | ||
| 20 | Short-term third party capital | 2 | ||
| 2400 | Loan A | 2 | 240 | |
| 2401 | Mortgage A | 2 | 240 | |
| 2420 | Financial leasing commitments | 2 | 240 | |
| 2430 | Debenture loans | 2 | 240 | |
| 2450 | Loans | 2 | 240 | |
| 2451 | Mortgages | 2 | 240 | |
| 2470 | Loans to participation A | 2 | 240 | |
| 2471 | Mortgage to participation A | 2 | 240 | |
| 2480 | Loans/Mortgages to person involved A | 2 | 240 | |
| 2481 | Loans/Mortgages to the Board of Directors A | 2 | 240 | |
| 2482 | Loans/Mortgages to member of Executive Board A | 2 | 240 | |
| 2483 | Loans/Mortgages to group company A | 2 | 240 | |
| 2484 | Loans/Mortgages to close person A | 2 | 240 | |
| 2490 | Pension funds loans | 2 | 240 | |
| 2491 | Mortgages to pension funds | 2 | 240 | |
| 240 | Long-term interest-bearing debts | 24 | ||
| 2500 | Debts due to third parties | 2 | 250 | |
| 2550 | Debts due to participation A | 2 | 250 | |
| 2560 | Debts due to person involved A | 2 | 250 | |
| 2561 | Debts due to member of the Board of Directors A | 2 | 250 | |
| 2562 | Debts due to member of Executive Board A | 2 | 250 | |
| 2563 | Debts due to group company A | 2 | 250 | |
| 2564 | Debts due to close person A | 2 | 250 | |
| 2570 | Debts due to pension funds | 2 | 250 | |
| 250 | Other long-term debts | 24 | ||
| 2630 | Provisions for warranty commitments | 2 | 260 | |
| 2631 | Provisions for purchase commitments | 2 | 260 | |
| 2640 | Provisions for direct taxes | 2 | 260 | |
| 2641 | Provisions for indirect taxes | 2 | 260 | |
| 2650 | Provisions for repairs and maintenance | 2 | 260 | |
| 2651 | Provisions for renovation of tangible assets | 2 | 260 | |
| 2652 | Provisions for research | 2 | 260 | |
| 2653 | Provisions for development | 2 | 260 | |
| 2654 | Provisions for restructuring | 2 | 260 | |
| 2655 | Provisions for environmental protection measures | 2 | 260 | |
| 2660 | Provisions for threatening losses from ongoing business | 2 | 260 | |
| 2670 | Provisions for pension funds commitments | 2 | 260 | |
| 2671 | Provisions for salary commitments | 2 | 260 | |
| 2680 | Provisions for participations commitments | 2 | 260 | |
| 2681 | Provisions for commitments to shareholders | 2 | 260 | |
| 2690 | Provisions to ensure the lastingly prosperity of the company | 2 | 260 | |
| 2691 | Other long-term provisions | 2 | 260 | |
| 260 | Long-term provisions and similar statutory positions | 24 | ||
| 24 | Long-term third party capital | 2 | ||
| Equity (legal entities) | ||||
| 2800 | Share capital category A | 2 | 280 | |
| 2800(2) | Nominal capital category A | 2 | 280 | |
| 2800(3) | Participation certificate capital category A | 2 | 280 | |
| 2800(4) | Foundation capital | 2 | 280 | |
| 2810 | Participation capital | 2 | 280 | |
| 280 | Nominal capital or capital of the foundation | 28 | ||
| 2900 | Premium at foundation or in the event of a capital increase | 2 | 290 | |
| 2901 | Other contributions or allocations | 2 | 290 | |
| 2902 | Premium from merger, demerger or asset transfer | 2 | 290 | |
| 2903 | Reserves from capital contributions (fiscally recognised) | 2 | 290 | |
| 2904 | Profit from capital reduction | 2 | 290 | |
| 2905 | Profit/loss from own capital share acquisition | 2 | 290 | |
| 2950 | Legal retained earnings | 2 | 290 | |
| 2955 | Revaluation reserve | 2 | 290 | |
| 2959 | Reserves for own shares (indirect acquisition) | 2 | 290 | |
| 2960 | Statutory retained earnings | 2 | 290 | |
| 2961 | Decided retained earnings | 2 | 290 | |
| 2962 | Profit/loss from own capital share acquisition | 2 | 290 | |
| 2965 | Own shares | 2 | 290 | |
| 2965(2) | Own nominal shares | 2 | 290 | |
| 2965(3) | Own share certificates | 2 | 290 | |
| 2966 | Own participation certificates | 2 | 290 | |
| 2970 | Profit or loss carried forward | 2 | 290 | |
| 2971 | Interim dividend distribution | 2 | 290 | |
| 2972 | Contribution of interim profit to the legal retained earnings | 2 | 290 | |
| 2973 | Contribution of interim profit to the voluntary retained earnings | 2 | 290 | |
| 2979 | Annual profit or loss | 2 | 290 | |
| 290 | Reserves, own capital share and profit or loss | 28 | ||
| Equity (sole proprietorships) | ||||
| 2800.E | Own capital | 2 | 28 | |
| 2801.E | Spouse individual property | 2 | 28 | |
| 2820.E | Capital contributions and capital withdrawals | 2 | 28 | |
| 2821.E | Individual property contributions and individual property withdrawals of the spouse | 2 | 28 | |
| 2850.E | Private cash withdrawals | 2 | 28 | |
| 2851.E | In kind withdrawals | 2 | 28 | |
| 2852.E | Private share of operating expenses | 2 | 28 | |
| 2853.E | Private flat rental value | 2 | 28 | |
| 2854.E | Private insurance premiums | 2 | 28 | |
| 2855.E | Private pension contributions | 2 | 28 | |
| 2856.E | Private taxes | 2 | 28 | |
| 2891.E | Annual profit or loss | 2 | 28 | |
| Equity (partnership) | ||||
| 2800.P | Partner A equity at the beginning of the financial year | 2 | 28 | |
| 2810.P | Partner A capital contributions and capital withdrawals | 2 | 28 | |
| 2820.P | Partner A cash withdrawals | 2 | 28 | |
| 2821.P | Partner A in kind withdrawals | 2 | 28 | |
| 2822.P | Partner A private share of operating expenses | 2 | 28 | |
| 2823.P | Partner A private flat rental value | 2 | 28 | |
| 2824.P | Partner A private insurance premiums | 2 | 28 | |
| 2825.P | Partner A private pension contributions | 2 | 28 | |
| 2826.P | Partner A private taxes | 2 | 28 | |
| 2830.P | Partner A annual profit or loss | 2 | 28 | |
| 2850.P | Limited partner A equity at the beginning of the financial year | 2 | 28 | |
| 2860.P | Limited partner A capital contributions and capital withdrawals | 2 | 28 | |
| 2870.P | Limited partner A cash withdrawals | 2 | 28 | |
| 2871.P | Limited partner A in kind withdrawals | 2 | 28 | |
| 2872.P | Limited partner A private share of operating expenses | 2 | 28 | |
| 2873.P | Limited partner A private flat rental value | 2 | 28 | |
| 2874.P | Limited partner A private insurance premiums | 2 | 28 | |
| 2875.P | Limited partner A private pension contributions | 2 | 28 | |
| 2876.P | Limited partner A private taxes | 2 | 28 | |
| 2880.P | Limited partner A annual profit or loss | 2 | 28 | |
| 297 | Profit/Loss from Balance Sheet | 28 | ||
| 28 | Equity | 2 | ||
| 2 | Total liabilities | 00 | ||
| PROFIT & LOSS STATEMENT | ||||
| REVENUES | ||||
| 3000 | Gross revenues from product A | 4 | 30 | |
| 3000(2) | Gross revenues from cash sales | 4 | 30 | |
| 3001 | Gross revenues from retail credit sales | 4 | 30 | |
| 3002 | Gross revenues from wholesale credit sales | 4 | 30 | |
| 3007 | Gross revenues from ancillary services (postage and packing) | 4 | 30 | |
| 3008 | Changes in receivables | 4 | 30 | |
| 3090 | Discounts | 4 | 30 | |
| 3091 | Rebates and price reductions | 4 | 30 | |
| 3092 | Refunds | 4 | 30 | |
| 3093 | Commissions to third parties | 4 | 30 | |
| 3094 | Collection charges | 4 | 30 | |
| 3095 | Losses on receivables, changes in value adjustments | 4 | 30 | |
| 3096 | Exchange rate differences | 4 | 30 | |
| 3097 | Freights, postages | 4 | 30 | |
| 30 | Manufactured products revenues | 3 | ||
| 3200 | Gross revenues from item A | 4 | 32 | |
| 3200(2) | Gross revenues from cash sales | 4 | 32 | |
| 3201 | Gross revenues from retail credit sales | 4 | 32 | |
| 3202 | Gross revenues from wholesale credit sales | 4 | 32 | |
| 3203 | Gross revenues from purchase prices | 4 | 32 | |
| 3207 | Gross revenues from ancillary services (postage and packing) | 4 | 32 | |
| 3208 | Changes in receivables | 4 | 32 | |
| 3290 | Discounts | 4 | 32 | |
| 3291 | Rebates and price reductions | 4 | 32 | |
| 3292 | Refunds | 4 | 32 | |
| 3293 | Commissions to third parties | 4 | 32 | |
| 3294 | Collection charges | 4 | 32 | |
| 3295 | Losses on receivables, changes in value adjustments | 4 | 32 | |
| 3296 | Exchange rate differences | 4 | 32 | |
| 3297 | Freights, postages | 4 | 32 | |
| 32 | Revenues from resale of goods | 3 | ||
| 3400 | Gross revenues from provided service A | 4 | 34 | |
| 3400(2) | Gross revenues in cash | 4 | 34 | |
| 3401 | Gross revenues on credit | 4 | 34 | |
| 3407 | Gross revenues from ancillary services | 4 | 34 | |
| 3408 | Changes in receivables | 4 | 34 | |
| 3490 | Discounts | 4 | 34 | |
| 3491 | Rebates and price reductions | 4 | 34 | |
| 3492 | Refunds | 4 | 34 | |
| 3493 | Commissions to third parties | 4 | 34 | |
| 3494 | Collection charges | 4 | 34 | |
| 3495 | Losses on receivables, changes in value adjustments | 4 | 34 | |
| 3496 | Exchange rate differences | 4 | 34 | |
| 3497 | Postages | 4 | 34 | |
| 34 | Revenues from provided services | 3 | ||
| 3600 | Revenues from raw materials | 4 | 36 | |
| 3601 | Revenues from auxiliary materials | 4 | 36 | |
| 3602 | Revenues from garbages | 4 | 36 | |
| 3607 | Revenues from ancillary services | 4 | 36 | |
| 3608 | Changes in receivables | 4 | 36 | |
| 3609 | Decrease in ancillary revenues | 4 | 36 | |
| 3610 | Revenues from product A licence | 4 | 36 | |
| 3619 | Decrease in revenues from licences, patents, etc. | 4 | 36 | |
| 3670 | Revenues from staff provision | 4 | 36 | |
| 3680 | Other revenues | 4 | 36 | |
| 3690 | Discounts | 4 | 36 | |
| 3691 | Rebates and price reductions | 4 | 36 | |
| 36 | Other revenues from deliveries and services | 3 | ||
| 3700 | Own production of movable tangible assets | 4 | 37 | |
| 3701 | Own production of fixed tangible assets | 4 | 37 | |
| 3702 | Own repair of movable tangible assets | 4 | 37 | |
| 3703 | Own repair of fixed tangible assets | 4 | 37 | |
| 3710 | Own consumption of product A | 4 | 37 | |
| 3720 | Own consumption of product A | 4 | 37 | |
| 3740 | Own consumption of provided service A | 4 | 37 | |
| 3790 | In kind withdrawals | 4 | 37 | |
| 37 | Own contributions and own consumption | 3 | ||
| 3800 | Discounts | 4 | 38 | |
| 3801 | Rebates and price reductions | 4 | 38 | |
| 3802 | Refunds | 4 | 38 | |
| 3803 | Commissions to third parties | 4 | 38 | |
| 3804 | Collection charges | 4 | 38 | |
| 3805 | Losses on receivables, changes in value adjustments | 4 | 38 | |
| 3806 | Exchange rate differences | 4 | 38 | |
| 3807 | Shipping costs | 4 | 38 | |
| 3809 | VAT net tax rate | 4 | 38 | |
| 3810 | Credit/debit card fees | 4 | 38 | |
| 3860 | Changes in warranty provisions | 4 | 38 | |
| 3861 | Changes in deductible provisions | 4 | 38 | |
| 38 | Decrease in revenues | 3 | ||
| 3900 | Changes in finished products inventories | 4 | 39 | |
| 3901 | Changes in semi-finished products inventories | 4 | 39 | |
| 3940 | Changes in non-invoiced services value | 4 | 39 | |
| 39 | Changes in inventories of semi-finished products, finished products and value of non-invoiced services | 3 | ||
| 3 | Net revenues from supplies and services | 02 | ||
| EXPENSES | ||||
| 4000 | Purchases of product A material | 3 | 40 | |
| 4000(2) | Purchases of equipment | 3 | 40 | |
| 4001 | Purchases of components | 3 | 40 | |
| 4002 | Purchases of accessories | 3 | 40 | |
| 4003 | Purchases of other materials | 3 | 40 | |
| 4004 | Purchases of auxiliary and consumable materials | 3 | 40 | |
| 4005 | Purchases of packing material | 3 | 40 | |
| 4006 | Third-party services | 3 | 40 | |
| 4007 | Direct purchasing expenses | 3 | 40 | |
| 4008 | Changes in inventories | 3 | 40 | |
| 4009 | Purchase price reductions | 3 | 40 | |
| 4060 | Sector A third-party services | 3 | 40 | |
| 4070 | Incoming freight | 3 | 40 | |
| 4071 | Import duties | 3 | 40 | |
| 4072 | Incoming shipments | 3 | 40 | |
| 4080 | Changes in sector A inventories | 3 | 40 | |
| 4086 | Sector A material losses | 3 | 40 | |
| 4090 | Discounts | 3 | 40 | |
| 4091 | Rebates and price reductions | 3 | 40 | |
| 4092 | Refunds | 3 | 40 | |
| 4093 | Commissions to third parties | 3 | 40 | |
| 4096 | Exchange rate differences | 3 | 40 | |
| 40 | Material costs | 4 | ||
| 4200 | Purchases of resale product A | 3 | 42 | |
| 4205 | Purchases of packing material | 3 | 42 | |
| 4207 | Direct purchasing expenses | 3 | 42 | |
| 4208 | Changes in inventories | 3 | 42 | |
| 4209 | Purchase price reductions | 3 | 42 | |
| 4270 | Incoming freight | 3 | 42 | |
| 4271 | Import duties | 3 | 42 | |
| 4272 | Incoming shipments | 3 | 42 | |
| 4280 | Changes in sector A inventories | 3 | 42 | |
| 4286 | Sector A loss of goods | 3 | 42 | |
| 4290 | Discounts | 3 | 42 | |
| 4291 | Rebates and price reductions | 3 | 42 | |
| 4292 | Refunds | 3 | 42 | |
| 4293 | Purchasing commissions | 3 | 42 | |
| 4296 | Exchange rate differences | 3 | 42 | |
| 42 | Costs of goods for resale | 4 | ||
| 4400 | Expenses for service A | 3 | 44 | |
| 4407 | Direct purchasing expenses | 3 | 44 | |
| 4409 | Deductions obtained on purchases | 3 | 44 | |
| 4470 | Direct purchase expenses for purchased services | 3 | 44 | |
| 4490 | Discounts | 3 | 44 | |
| 4491 | Rebates and price reductions | 3 | 44 | |
| 4492 | Refunds | 3 | 44 | |
| 4493 | Purchasing commissions | 3 | 44 | |
| 4496 | Exchange rate differences | 3 | 44 | |
| 44 | Expenses for purchased services | 4 | ||
| 4500 | Heat electricity | 3 | 45 | |
| 4501 | Industrial electricity | 3 | 45 | |
| 4510 | Natural gas | 3 | 45 | |
| 4511 | Liquid gas in cylinders | 3 | 45 | |
| 4520 | Heating oil | 3 | 45 | |
| 4521 | Coal, briquettes, wood | 3 | 45 | |
| 4530 | Petrol | 3 | 45 | |
| 4531 | Diesel | 3 | 45 | |
| 4532 | Oil | 3 | 45 | |
| 4540 | Water | 3 | 45 | |
| 45 | Energy consumption for production | 4 | ||
| 4600 | Other material costs of production | 3 | 46 | |
| 4620 | Other costs of goods for resale | 3 | 46 | |
| 4640 | Other costs of services | 3 | 46 | |
| 4650 | Packaging costs | 3 | 46 | |
| 4660 | Changes in warranty provisions | 3 | 46 | |
| 4661 | Changes in deductible provisions | 3 | 46 | |
| 46 | Other costs of materials, goods for resale and services | 4 | ||
| 4700 | Incoming freight | 3 | 47 | |
| 4701 | Import duties | 3 | 47 | |
| 4702 | Incoming shipments | 3 | 47 | |
| 47 | Direct purchasing expenses | 4 | ||
| 4800 | Discounts | 3 | 48 | |
| 4801 | Rebates and price reductions | 3 | 48 | |
| 4802 | Refunds | 3 | 48 | |
| 4803 | Purchasing commissions | 3 | 48 | |
| 4804 | Exchange rate differences | 3 | 48 | |
| 48 | Purchase price reductions | 4 | ||
| 4900 | Changes in goods for resale inventories | 3 | 49 | |
| 4901 | Changes in raw material inventories | 3 | 49 | |
| 4902 | Changes in production material inventories | 3 | 49 | |
| 4903 | Changes in auxiliary material and consumables inventories | 3 | 49 | |
| 4904 | Changes in compulsory inventories | 3 | 49 | |
| 4905 | Changes in goods on delivery inventories | 3 | 49 | |
| 4980 | Material losses | 3 | 49 | |
| 4986 | Losses of goods for resale | 3 | 49 | |
| 49 | Changes in inventories, material and goods losses | 4 | ||
| 4 | Costs for material, goods, services and energy | 02 | ||
| 5000 | Salaries | 3 | 50 | |
| 5001 | Allowances | 3 | 50 | |
| 5002 | Profit-sharing | 3 | 50 | |
| 5003 | Commissions | 3 | 50 | |
| 5005 | Social insurance benefits | 3 | 50 | |
| 5006 | Provision of personnel | 3 | 50 | |
| 5007 | Social insurance expenses | 3 | 50 | |
| 5008 | Other personnel expenses | 3 | 50 | |
| 5009 | Benefits from third parties | 3 | 50 | |
| 5070 | AHV, IV, EO, ALV | 3 | 50 | |
| 5071 | Family allowance | 3 | 50 | |
| 5072 | Pension funds | 3 | 50 | |
| 5073 | Accident insurance | 3 | 50 | |
| 5074 | Daily sickness benefits insurance | 3 | 50 | |
| 5079 | Tax at source | 3 | 50 | |
| 5080 | Staff recruitment | 3 | 50 | |
| 5081 | Education and training | 3 | 50 | |
| 5082 | Reimbursements of actual expenses | 3 | 50 | |
| 5083 | Reimbursements of flat-rate expenses | 3 | 50 | |
| 5089 | Other personnel expenses | 3 | 50 | |
| 5090 | Temporary staff | 3 | 50 | |
| 50 | Personnel expenses - production | 5 | ||
| 5200 | Salaries | 3 | 52 | |
| 5201 | Allowances | 3 | 52 | |
| 5202 | Profit-sharing | 3 | 52 | |
| 5203 | Commissions | 3 | 52 | |
| 5205 | Social insurance benefits | 3 | 52 | |
| 5206 | Provision of personnel | 3 | 52 | |
| 5207 | Social insurance expenses | 3 | 52 | |
| 5208 | Other personnel expenses | 3 | 52 | |
| 5209 | Benefits from third parties | 3 | 52 | |
| 5270 | AHV, IV, EO, ALV | 3 | 52 | |
| 5271 | Family allowance | 3 | 52 | |
| 5272 | Pension funds | 3 | 52 | |
| 5273 | Accident insurance | 3 | 52 | |
| 5274 | Daily sickness benefits insurance | 3 | 52 | |
| 5279 | Tax at source | 3 | 52 | |
| 5280 | Staff recruitment | 3 | 52 | |
| 5281 | Education and training | 3 | 52 | |
| 5282 | Reimbursements of actual expenses | 3 | 52 | |
| 5283 | Reimbursements of flat-rate expenses | 3 | 52 | |
| 5289 | Other personnel expenses | 3 | 52 | |
| 5290 | Temporary staff | 3 | 52 | |
| 52 | Personnel expenses - commerce | 5 | ||
| 5400 | Salaries | 3 | 54 | |
| 5401 | Allowances | 3 | 54 | |
| 5402 | Profit-sharing | 3 | 54 | |
| 5403 | Commissions | 3 | 54 | |
| 5405 | Social insurance benefits | 3 | 54 | |
| 5406 | Provision of personnel | 3 | 54 | |
| 5407 | Social insurance expenses | 3 | 54 | |
| 5408 | Other personnel expenses | 3 | 54 | |
| 5409 | Benefits from third parties | 3 | 54 | |
| 5470 | AHV, IV, EO, ALV | 3 | 54 | |
| 5471 | Family allowance | 3 | 54 | |
| 5472 | Pension funds | 3 | 54 | |
| 5473 | Accident insurance | 3 | 54 | |
| 5474 | Daily sickness benefits insurance | 3 | 54 | |
| 5479 | Tax at source | 3 | 54 | |
| 5480 | Staff recruitment | 3 | 54 | |
| 5481 | Education and training | 3 | 54 | |
| 5482 | Reimbursements of actual expenses | 3 | 54 | |
| 5483 | Reimbursements of flat-rate expenses | 3 | 54 | |
| 5489 | Other personnel expenses | 3 | 54 | |
| 5490 | Temporary staff | 3 | 54 | |
| 54 | Personnel expenses - supply of services | 5 | ||
| 5600 | Salaries | 3 | 56 | |
| 5601 | Allowances | 3 | 56 | |
| 5602 | Profit-sharing | 3 | 56 | |
| 5603 | Salaries to participants and members of the Executive Board | 3 | 56 | |
| 5604 | Board of Directors fees | 3 | 56 | |
| 5605 | Social insurance benefits | 3 | 56 | |
| 5606 | Provision of personnel | 3 | 56 | |
| 5607 | Social insurance expenses | 3 | 56 | |
| 5608 | Other personnel expenses | 3 | 56 | |
| 5609 | Benefits from third parties | 3 | 56 | |
| 5670 | AHV, IV, EO, ALV | 3 | 56 | |
| 5671 | Family allowance | 3 | 56 | |
| 5672 | Pension funds | 3 | 56 | |
| 5673 | Accident insurance | 3 | 56 | |
| 5674 | Daily sickness benefits insurance | 3 | 56 | |
| 5679 | Tax at source | 3 | 56 | |
| 5680 | Staff recruitment | 3 | 56 | |
| 5681 | Education and training | 3 | 56 | |
| 5682 | Reimbursements of actual expenses | 3 | 56 | |
| 5683 | Reimbursements of flat-rate expenses | 3 | 56 | |
| 5689 | Other personnel expenses | 3 | 56 | |
| 5690 | Temporary staff | 3 | 56 | |
| 56 | Personnel expenses - administration | 5 | ||
| 5700 | AHV, IV, EO, ALV | 3 | 57 | |
| 5701 | AHV, IV, EO holder | 3 | 57 | |
| 5710 | Family allowance | 3 | 57 | |
| 5720 | Pension funds | 3 | 57 | |
| 5730 | Accident insurance | 3 | 57 | |
| 5740 | Daily sickness benefits insurance | 3 | 57 | |
| 5790 | Tax at source | 3 | 57 | |
| 57 | Social insurance expenses | 5 | ||
| 5800 | Advertisements of job openings | 3 | 58 | |
| 5801 | Recruitment commissions | 3 | 58 | |
| 5810 | Training necessary for business needs | 3 | 58 | |
| 5811 | Professional training | 3 | 58 | |
| 5820 | Travel expenses | 3 | 58 | |
| 5821 | Food expenses | 3 | 58 | |
| 5822 | Accommodation expenses | 3 | 58 | |
| 5830 | Management flat-rate expenses | 3 | 58 | |
| 5831 | Executive Board flat-rate expenses | 3 | 58 | |
| 5832 | Board of Directors flat-rate expenses | 3 | 58 | |
| 5840 | Staff canteen meals | 3 | 58 | |
| 5841 | Staff canteen beverages | 3 | 58 | |
| 5845 | Revenues for meals (as expense reduction) | 3 | 58 | |
| 5846 | Revenues for beverages (as expense reduction) | 3 | 58 | |
| 5880 | Staff events | 3 | 58 | |
| 5881 | Company sports group | 3 | 58 | |
| 5890 | Private share of personnel expenses | 3 | 58 | |
| 58 | Other personnel expenses | 5 | ||
| 5900 | Benefits from third parties | 3 | 59 | |
| 5901 | Temporary staff | 3 | 59 | |
| 59 | Benefits from third parties | 5 | ||
| 5 | Personnel expenses | 02 | ||
| 6000 | Factory rent | 3 | 60 | |
| 6001 | Workshop and atelier rent | 3 | 60 | |
| 6002 | Warehouse rent | 3 | 60 | |
| 6003 | Showrooms and shop floors rent | 3 | 60 | |
| 6004 | Office and administration rooms rent | 3 | 60 | |
| 6005 | Staff rooms rent | 3 | 60 | |
| 6006 | Garage, parking rent | 3 | 60 | |
| 6030 | Factory additional costs | 3 | 60 | |
| 6031 | Workshop and atelier additional costs | 3 | 60 | |
| 6032 | Warehouse additional costs | 3 | 60 | |
| 6033 | Showrooms and shop floors additional costs | 3 | 60 | |
| 6034 | Office and administration rooms additional costs | 3 | 60 | |
| 6035 | Staff rooms additional costs | 3 | 60 | |
| 6036 | Garage additional costs | 3 | 60 | |
| 6030(2) | Heating additional costs | 3 | 60 | |
| 6031(2) | Electricity, gas, water additional costs | 3 | 60 | |
| 6032(2) | Caretaker additional costs | 3 | 60 | |
| 6040 | Factory cleaning | 3 | 60 | |
| 6041 | Workshop and atelier cleaning | 3 | 60 | |
| 6042 | Warehouse cleaning | 3 | 60 | |
| 6043 | Showrooms and shop floors cleaning | 3 | 60 | |
| 6044 | Office and administration rooms cleaning | 3 | 60 | |
| 6045 | Staff rooms cleaning | 3 | 60 | |
| 6040(2) | Cleaning staff | 3 | 60 | |
| 6041(2) | Third-party cleaning services | 3 | 60 | |
| 6042(2) | Cleaning materials | 3 | 60 | |
| 6050 | Factory maintenance | 3 | 60 | |
| 6051 | Workshop and atelier maintenance | 3 | 60 | |
| 6052 | Warehouse maintenance | 3 | 60 | |
| 6053 | Showrooms and shop floors maintenance | 3 | 60 | |
| 6054 | Office and administration rooms maintenance | 3 | 60 | |
| 6055 | Staff rooms maintenance | 3 | 60 | |
| 6056 | Garage maintenance | 3 | 60 | |
| 6050(2) | Repairs | 3 | 60 | |
| 6051(2) | Small investments | 3 | 60 | |
| 6052(2) | Subscription services | 3 | 60 | |
| 6059 | Insurance services | 3 | 60 | |
| 6060 | Factory leasing | 3 | 60 | |
| 6061 | Workshop and atelier leasing | 3 | 60 | |
| 6062 | Warehouse leasing | 3 | 60 | |
| 6063 | Showrooms and shop floors leasing | 3 | 60 | |
| 6064 | Office and administration rooms leasing | 3 | 60 | |
| 6065 | Staff rooms leasing | 3 | 60 | |
| 6066 | Garage leasing | 3 | 60 | |
| 6070 | Ground rents | 3 | 60 | |
| 6090 | Private share of facility expenses | 3 | 60 | |
| 60 | Facility expenses | 6 | ||
| 6100 | MRR machines and apparatuses | 3 | 61 | |
| 6101 | MRR furniture and equipment | 3 | 61 | |
| 6102 | MRR tools and devices | 3 | 61 | |
| 6105 | Leasing of manufacturing plants | 3 | 61 | |
| 6110 | MRR shop equipment | 3 | 61 | |
| 6111 | MRR showroom equipment | 3 | 61 | |
| 6115 | Leasing of sales equipment | 3 | 61 | |
| 6120 | MRR central warehouse | 3 | 61 | |
| 6121 | MRR warehouse A | 3 | 61 | |
| 6125 | Leasing of warehouse equipment | 3 | 61 | |
| 6130 | MRR office furniture | 3 | 61 | |
| 6131 | MRR office machines | 3 | 61 | |
| 6132 | MRR information technology | 3 | 61 | |
| 6133 | MRR communication technology | 3 | 61 | |
| 6135 | Leasing of office equipment | 3 | 61 | |
| 6140 | MRR staff canteen furniture | 3 | 61 | |
| 6141 | MRR staff rooms furniture | 3 | 61 | |
| 6145 | Leasing of staff equipment | 3 | 61 | |
| 6190 | Insurance services | 3 | 61 | |
| 61 | Maintenance, repairs, replacements (MRR): leasing of movable tangible assets | 6 | ||
| 6200 | Repairs | 3 | 62 | |
| 6201 | Services | 3 | 62 | |
| 6202 | Cleaning | 3 | 62 | |
| 6210 | Petrol | 3 | 62 | |
| 6211 | Diesel | 3 | 62 | |
| 6212 | Oil | 3 | 62 | |
| 6213 | Electricity | 3 | 62 | |
| 6220 | Liability insurance | 3 | 62 | |
| 6221 | Comprehensive insurance | 3 | 62 | |
| 6222 | Legal protection insurance | 3 | 62 | |
| 6230 | Road taxes | 3 | 62 | |
| 6231 | Contributions | 3 | 62 | |
| 6232 | Vehicle taxes | 3 | 62 | |
| 6260 | Vehicle leasing | 3 | 62 | |
| 6264 | Vehicle rentals | 3 | 62 | |
| 6270 | Private share of vehicle expenses | 3 | 62 | |
| 6280 | Freights | 3 | 62 | |
| 6281 | Freight forwarder | 3 | 62 | |
| 6282 | Cargo domicile | 3 | 62 | |
| 62 | Vehicle and transport expenses | 6 | ||
| 6300 | Natural hazard insurance | 3 | 63 | |
| 6301 | Glass breakage insurance | 3 | 63 | |
| 6302 | Theft insurance | 3 | 63 | |
| 6310 | Business liability insurance | 3 | 63 | |
| 6311 | Warranty insurance | 3 | 63 | |
| 6312 | Legal protection insurance | 3 | 63 | |
| 6320 | Business interruption insurance | 3 | 63 | |
| 6330 | Death risk insurance | 3 | 63 | |
| 6331 | Guarantee premiums | 3 | 63 | |
| 6360 | Charges | 3 | 63 | |
| 6361 | Fees | 3 | 63 | |
| 6370 | Permits | 3 | 63 | |
| 6371 | Operating licences | 3 | 63 | |
| 63 | Property insurance, charges, fees, permits | 6 | ||
| 6400 | Industrial electricity | 3 | 64 | |
| 6401 | Heat electricity | 3 | 64 | |
| 6402 | Electricity for lighting | 3 | 64 | |
| 6410 | Natural gas | 3 | 64 | |
| 6411 | Liquid gas in cylinders | 3 | 64 | |
| 6420 | Heating oil | 3 | 64 | |
| 6421 | Coal, briquettes, wood | 3 | 64 | |
| 6430 | Water | 3 | 64 | |
| 6460 | Garbage collection | 3 | 64 | |
| 6461 | Hazardous waste collection | 3 | 64 | |
| 6462 | Waste water | 3 | 64 | |
| 64 | Energy and disposal costs | 6 | ||
| 6500 | Office equipment | 3 | 65 | |
| 6501 | Printers | 3 | 65 | |
| 6502 | Photocopies | 3 | 65 | |
| 6503 | Specialist publications, newspapers, periodicals | 3 | 65 | |
| 6510 | Telephone | 3 | 65 | |
| 6512 | Internet | 3 | 65 | |
| 6513 | Postages | 3 | 65 | |
| 6520 | Contributions | 3 | 65 | |
| 6521 | Donations, grants | 3 | 65 | |
| 6522 | Tips | 3 | 65 | |
| 6530 | Bookkeeping | 3 | 65 | |
| 6531 | Business consultancy | 3 | 65 | |
| 6532 | Legal advice | 3 | 65 | |
| 6540 | Board of Directors expenses | 3 | 65 | |
| 6541 | General meeting expenses | 3 | 65 | |
| 6542 | Auditing expenses | 3 | 65 | |
| 6550 | Formation, capital increase and organisational expenses | 3 | 65 | |
| 6551 | Collection and execution costs | 3 | 65 | |
| 6555 | Management fees | 3 | 65 | |
| 6559 | Other administration costs | 3 | 65 | |
| 6560 | Private share of administration costs | 3 | 65 | |
| 6570 | Hardware leasing | 3 | 65 | |
| 6571 | Software leasing | 3 | 65 | |
| 6572 | Hardware rent | 3 | 65 | |
| 6573 | Software rent | 3 | 65 | |
| 6580 | Licenses and updates expenses | 3 | 65 | |
| 6581 | Hardware maintenance/hotline | 3 | 65 | |
| 6582 | Software maintenance/hotline | 3 | 65 | |
| 6583 | Consumables | 3 | 65 | |
| 6585 | Dedicated phone line expenses | 3 | 65 | |
| 6590 | Basic advice | 3 | 65 | |
| 6591 | Individual development, individual adjustments | 3 | 65 | |
| 6592 | Implementation costs | 3 | 65 | |
| 6590(2) | IT development - project A | 3 | 65 | |
| 65 | Administrative and IT expenses | 6 | ||
| 6600 | Advertisements | 3 | 66 | |
| 6601 | Radio advertising | 3 | 66 | |
| 6602 | TV advertising | 3 | 66 | |
| 6604 | Internet and social media | 3 | 66 | |
| 6610 | Printed advertisements, advertising material | 3 | 66 | |
| 6611 | Advertising items, samples, billboards and electronic adverts | 3 | 66 | |
| 6620 | Shop windows, decorations | 3 | 66 | |
| 6621 | Trade fairs, exhibitions | 3 | 66 | |
| 6640 | Expenses | 3 | 66 | |
| 6641 | Customer care | 3 | 66 | |
| 6642 | Gifts to customers | 3 | 66 | |
| 6660 | Advertising contributions | 3 | 66 | |
| 6661 | Sponsoring | 3 | 66 | |
| 6670 | Customer events | 3 | 66 | |
| 6671 | Media contacts | 3 | 66 | |
| 6672 | Corporate anniversaries | 3 | 66 | |
| 6680 | Advertising consultancy | 3 | 66 | |
| 6681 | Market analysis | 3 | 66 | |
| 6690 | Private share of advertising expenses | 3 | 66 | |
| 66 | Advertising expenses | 6 | ||
| 6700 | Business information | 3 | 67 | |
| 6701 | Debt collection | 3 | 67 | |
| 6710 | Operational safety | 3 | 67 | |
| 6711 | Surveillance | 3 | 67 | |
| 6720 | Project A research | 3 | 67 | |
| 6721 | Project A development | 3 | 67 | |
| 6740 | Input tax correction (in the case of mixed use) | 3 | 67 | |
| 6790 | Other operating expenses | 3 | 67 | |
| 6791 | Private shares | 3 | 67 | |
| 67 | Other operating expenses | 6 | ||
| 6800 | Fixed assets securities value adjustments | 3 | 68 | |
| 6801 | Other financial assets value adjustments | 3 | 68 | |
| 6804 | Long-term receivables towards third parties value adjustments | 3 | 68 | |
| 6805 | Long-term receivables towards participations value adjustments | 3 | 68 | |
| 6806 | Long-term receivables towards shareholders value adjustments | 3 | 68 | |
| 6810 | Participation A value adjustments | 3 | 68 | |
| 6820 | Depreciation and value adjustments to machinery and equipment | 3 | 68 | |
| 6821 | Depreciation and value adjustments to furniture and installations | 3 | 68 | |
| 6822 | Depreciation and value adjustments to office machines, information and communication technology | 3 | 68 | |
| 6823 | Depreciation and value adjustments to vehicles | 3 | 68 | |
| 6824 | Depreciation and value adjustments to tools and equipment | 3 | 68 | |
| 6825 | Depreciation and value adjustments to storage facilities | 3 | 68 | |
| 6827 | Depreciation and value adjustments to fixed facilities and installations | 3 | 68 | |
| 6829 | Depreciation and value adjustments to other movable tangible assets | 3 | 68 | |
| 6830 | Depreciation and value adjustments to commercial properties | 3 | 68 | |
| 6831 | Depreciation and value adjustments to factories | 3 | 68 | |
| 6832 | Depreciation and value adjustments to workshops and ateliers | 3 | 68 | |
| 6833 | Depreciation and value adjustments to warehouses | 3 | 68 | |
| 6834 | Depreciation and value adjustments to exhibition and sales buildings | 3 | 68 | |
| 6835 | Depreciation and value adjustments to office and administration buildings | 3 | 68 | |
| 6836 | Depreciation and value adjustments to residential buildings | 3 | 68 | |
| 6837 | Depreciation and value adjustments to undeveloped land | 3 | 68 | |
| 6840 | Depreciation and value adjustments to patents, know-how and recipes | 3 | 68 | |
| 6841 | Depreciation and value adjustments to brands, samples, models and plans | 3 | 68 | |
| 6842 | Depreciation and value adjustments to licences, concessions, rights of use and company rights | 3 | 68 | |
| 6843 | Depreciation and value adjustments to copyrights, publishing rights and contractual rights | 3 | 68 | |
| 6845 | Depreciation and value adjustments to development | 3 | 68 | |
| 6847 | Depreciation and value adjustments to goodwill | 3 | 68 | |
| 6849 | Depreciation and value adjustments to other intangible assets | 3 | 68 | |
| 68 | Depreciation and value adjustments to fixed assets positions | 6 | ||
| 6900 | Bank interest fees | 3 | 69 | |
| 6901 | Loan interest fees | 3 | 69 | |
| 6902 | Mortgage interest fees | 3 | 69 | |
| 6903 | Default interest fees | 3 | 69 | |
| 6904 | Interest fees from advance payments received | 3 | 69 | |
| 6905 | Interest fees from financial leasing | 3 | 69 | |
| 6920 | Person involved A interest fees | 3 | 69 | |
| 6921 | Member of the Board of Directors A interest fees | 3 | 69 | |
| 6922 | Member of Executive Board A interest fees | 3 | 69 | |
| 6923 | Group company A interest fees | 3 | 69 | |
| 6924 | Close person A interest fees | 3 | 69 | |
| 6930 | Pension funds loans interest fees | 3 | 69 | |
| 6940 | Bank charges | 3 | 69 | |
| 6941 | Custody fees | 3 | 69 | |
| 6942 | Exchange losses on short-term assets listed on the stock exchange | 3 | 69 | |
| 6943 | Exchange losses on financial assets | 3 | 69 | |
| 6944 | Exchange losses on interest-bearing debts | 3 | 69 | |
| 6945 | Granted customer accounts | 3 | 69 | |
| 6946 | Exchange loss on cryptocurrencies | 3 | 69 | |
| 6947 | Factoring fee | 3 | 69 | |
| 6949 | Currency losses | 3 | 69 | |
| 6950 | Revenues from bank deposits | 3 | 69 | |
| 6951 | Revenues from short-term financial investments | 3 | 69 | |
| 6952 | Revenues from short-term securities | 3 | 69 | |
| 6953 | Revenues from other short-term assets | 3 | 69 | |
| 6960 | Revenues from fixed assets securities | 3 | 69 | |
| 6961 | Revenues from other financial assets | 3 | 69 | |
| 6962 | Revenues from participations | 3 | 69 | |
| 6963 | Revenues from long-term receivables | 3 | 69 | |
| 6980 | Revenues from person involved A | 3 | 69 | |
| 6981 | Revenues from member of the Board of Directors A | 3 | 69 | |
| 6982 | Revenues from member of Executive Board A | 3 | 69 | |
| 6983 | Revenues from group company A | 3 | 69 | |
| 6984 | Revenues from close person A | 3 | 69 | |
| 6990 | Default interest income, remuneration interest | 3 | 69 | |
| 6991 | Revenue from advance payments to suppliers | 3 | 69 | |
| 6992 | Exchange gains on short-term assets listed on the stock exchange | 3 | 69 | |
| 6993 | Exchange gains on financial assets | 3 | 69 | |
| 6995 | Discounts received from suppliers | 3 | 69 | |
| 6996 | Exchange gain on cryptocurrencies | 3 | 69 | |
| 6999 | Currency gains | 3 | 69 | |
| 69 | Financial expenses and revenues | 6 | ||
| 6 | Other operating expenses, depreciation, value adjustments and financial results | 02 | ||
| 7000 | Gross profits | 3 | 70 | |
| 7009 | Decrease in revenues | 3 | 70 | |
| 7010 | Material costs | 3 | 70 | |
| 7011 | Personnel expenses | 3 | 70 | |
| 7012 | Facility expenses | 3 | 70 | |
| 7013 | Maintenance, repairs, replacements, leasing expenses | 3 | 70 | |
| 7014 | Vehicle and transport expenses | 3 | 70 | |
| 7015 | Property insurance, charges, fees, permits | 3 | 70 | |
| 7016 | Energy and disposal costs | 3 | 70 | |
| 7017 | Administrative and IT expenses | 3 | 70 | |
| 7018 | Advertising expenses | 3 | 70 | |
| 7019 | Other expenses | 3 | 70 | |
| 70 | Result from ancillary activities | 7 | ||
| 7502 | Rental income from commercial premises | 3 | 75 | |
| 7503 | Rental income from flats | 3 | 75 | |
| 7504 | Rental income from garages | 3 | 75 | |
| 7505 | Opted rental income | 3 | 75 | |
| 7508 | Share of heating, lighting | 3 | 75 | |
| 7509 | Other real estate income | 3 | 75 | |
| 7510 | Mortgage interest fees | 3 | 75 | |
| 7511 | Real estate maintenance | 3 | 75 | |
| 7512 | Charges, fees, property taxes | 3 | 75 | |
| 7513 | Insurance premiums | 3 | 75 | |
| 7514 | Water, waste water | 3 | 75 | |
| 7515 | Waste, disposal | 3 | 75 | |
| 7516 | Administrative expenses | 3 | 75 | |
| 7517 | Heating, lighting, water | 3 | 75 | |
| 7518 | Depreciation and value adjustment | 3 | 75 | |
| 7519 | Other real estate expenses | 3 | 75 | |
| 75 | Result from operational real estate | 7 | ||
| 7 | Ancillary operating result | 02 | ||
| 8000 | Non-operating costs | 3 | 80 | |
| 8100 | Non-operating revenues | 3 | 80 | |
| 80 | Non-operating costs and revenues | 8 | ||
| 8500 | Extraordinary provisions | 3 | 85 | |
| 8501 | Extraordinary depreciation and value adjustment | 3 | 85 | |
| 8503 | Extraordinary currency losses | 3 | 85 | |
| 8504 | Extraordinary losses on disposal of fixed assets | 3 | 85 | |
| 8505 | Extraordinary losses on receivables | 3 | 85 | |
| 8506 | Inconvenience compensation payments | 3 | 85 | |
| 8510 | Dissolution of reserves | 3 | 85 | |
| 8511 | Dissolution of provisions no longer required | 3 | 85 | |
| 8513 | Extraordinary currency gains | 3 | 85 | |
| 8514 | Extraordinary gains on disposal of fixed assets | 3 | 85 | |
| 8515 | Subsidies and other non-payments received with input tax reduction | 3 | 85 | |
| 8516 | Donations and other non-payments received without input tax reduction | 3 | 85 | |
| 8517 | Inconvenience compensation received | 3 | 85 | |
| 8600 | Non-recurring expenses | 3 | 85 | |
| 8610 | Non-recurring revenues | 3 | 85 | |
| 8704 | Creation of employer contribution reserve | 3 | 85 | |
| 8705 | Deductibles | 3 | 85 | |
| 8709 | Other expenses unrelated to the period | 3 | 85 | |
| 8710 | Revenues from insurance services or indemnity payments | 3 | 85 | |
| 8711 | Revenues from refunds | 3 | 85 | |
| 8712 | Revenues from reimbursements | 3 | 85 | |
| 8714 | Dissolution of employer contribution reserve | 3 | 85 | |
| 8719 | Other revenues unrelated to the period | 3 | 85 | |
| 85 | Extraordinary, non-recurring or unrelated to the period expenses and revenues | 8 | ||
| 8900 | Taxes on profits | 3 | 89 | |
| 8901 | Capital taxes | 3 | 89 | |
| 8902 | Direct taxes unrelated to the period | 3 | 89 | |
| 8900(2) | Cantonal and municipal taxes | 3 | 89 | |
| 8901(2) | Direct federal taxes | 3 | 89 | |
| 89 | Direct taxes | 8 | ||
| 8 | Non-operating, extraordinary, non-recurring or unrelated to the period result | 02 | ||
| 9200 | Profit or loss for the year | 3 | 9 | |
| 9 | Closure | 02 | ||
| 02 | Loss(+)/Profit(-) from income statement | 297 | ||
| 00 | Difference should be = 0 (empty cell) |
Business Templates Switzerland without VAT
Templates without VAT are ideal for managing the accounting of small businesses and professionals not subject to VAT. You work easily in tables, similar to Excel, where you can correct and edit entries. The models are based on the Swiss SME system of accounts (Sterchi, Mattle, Helbing), in compliance with the Swiss Code of Obligations (articles 957-963b CO).
VAT-free templates ready for your accounting needs
Banana Accounting Plus offers various pre-set accounting models suitable for different types of businesses and accounting skills.
If you have no accounting knowledge, you can choose the Cash Manager (Cashbook) model to manage cash inflows and outflows, or an Income/Expense template, which allows you to manage income and expenses across multiple accounts.
On the other hand, if you have accounting knowledge or work in the field, choose a double-entry accounting model tailored to your legal structure or business activity.
Easy and Quick Start
You can open the templates immediately with our WebApp by saving the file to your computer, or by downloading the program from our Download page.
Create your file:
- Using the File > File Properties command, set the period, the name of your company, and the base currency (you can create the budget and accounting in any currency)
- With the File > Save As command, save the file. It's helpful to include the company name and year in the file name. For example, "Rossi-SA-20xx.ac2."
WARNING: If you close the browser without saving, you will lose the entered data. Always save the file to your computer.
To reopen the saved file, click on File > Open. You can also double-click the file name on your computer.
Since the charts of accounts are already set up, you can immediately start recording transactions.
Once the transactions are recorded, you can generate professional reports and prints. Banana Accounting Plus offers multiple functions, from invoicing with the Swiss QR code to the automatic import of bank or postal transactions, including the counterpart.
Here are the most important features for businesses in detail:
- Create and print invoices with the Swiss QR code
- Import transactions from bank statements
- Set up Rules to store and automate the completion of entries imported from bank statements
- Manage cost centers, customisable according to your needs, to get specific details on certain accounts
- Create budgets and financial forecasts
- Print all the reports you need: Balance Sheets, Journals, Account Ledgers, VAT Reports, Open Invoices, and much more
Some features require a subscription to the Advanced plan of Banana Accounting Plus, such as using the new Rules features, temporary Row Filter, and Sort. Check out all the features of the Advanced plan.
Cash Manager (free) | Self-employed professional
In this article
Cash Manager (free) | Self-employed professional
Cash Manager (free) | Self-employed professional
Ideal cash model for accounting the cash inflows and outflows of a professional office. To maintain order, accuracy, and control over the cash, scan receipts into PDF and attach them directly to your file. Supporting documents are always at your fingertips without needing to search for the paper copies. You can view the various expense categories and payments made. You can also quickly create your forecast of inflows and outflows and know your liquidity situation in advance. Open the model from our WebApp or from the program and save the file to your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
The Banana Accounting Plus Cash Manager is a completely free application. It only takes a few simple steps to create your file.
Create your file
- Open the template with Banana Accounting Plus WebApp.
- Using the command File > File Properties, set the period, the name of your office, and the base currency (you can create the budget and accounting in any currency).
- With the command File > Save As, save the file. It's useful to include the name of your office and the year in the file name. For example, "Rossi-20xx.ac2."
ATTENTION: If you close the browser without saving, you will lose the entered data. Always save the file to your computer.
You can then consult all the information in our Documentation, particularly on the following web pages:
Template preview
Professional studio XX
Accounting 2024
Basic Currency: CHF
Cash Manager
| Group | Account | Description | Sum In |
|---|---|---|---|
| 1000 | Cash on hand | ||
| Group | Category | Description | Sum In |
|---|---|---|---|
| OPERATING RESULT | |||
| INCOME | |||
| 3400 | Services/Honoraria | 3 | |
| 3407 | Commissions | 3 | |
| 3620 | Various income | 3 | |
| 3 | TOTAL INCOME | 00 | |
| EXPENSES | |||
| 4090 | Discounts | 4 | |
| 5000 | Salaries employees | 4 | |
| 5482 | Representation expenses | 4 | |
| 5489 | Commissions | 4 | |
| 6000 | Rent | 4 | |
| 6100 | Cleaning and Upkeep | 4 | |
| 6210 | Fuel | 4 | |
| 6220 | Insurances | 4 | |
| 6280 | Shipping charges | 4 | |
| 6400 | Electricity, water, heating | 4 | |
| 6500 | Office supplies | 4 | |
| 6510 | Telephone | 4 | |
| 6640 | Transportation | 4 | |
| 4 | TOTAL EXPENSES | 00 | |
| 00 | TOTAL OPERATING RESULT | ||
Cash Manager (free) | Business
In this article
Cash Manager (free) | Business
Cash Manager (free) | Business
Model for easily managing all cash transactions. For cash outflows, you can quickly record all receipts and attach them in PDF format directly to the file. Just one click is needed to open the document. With the Budget feature, you can instantly create a forecast of your income and expenses to know your liquidity situation in advance. Open the model from our WebApp or the program and save the file to your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
The Banana Accounting Plus Cash Manager is a completely free application.
It is designed to manage the cash inflows and outflows of a small business. The file can also complement the main accounting file:
- Record all cash transactions in the file.
- At the end of each quarter (or a period of your choice), import the totals of categories and accounts into the main accounting file.
You will have the advantage of keeping all the details of cash transactions in a single file, while the main accounting file will only display the grouped totals by quarter or chosen period, streamlining the main accounting process.
Create your file
- Open the template with the Banana Accounting Plus WebApp.
- Using the command File > File Properties, set the period, the name of your business, and the base currency (you can create the budget and accounting in any currency).
- With the command File > Save As, save the file. It’s helpful to include the business name and the year in the file name. For example, "Cassa-Rossi-20xx.ac2".
WARNING: If you close the browser without saving, you will lose the entered data. Always save the file to your computer.
More information is available on the following pages:
Template preview
Shop XXX
Accounting 2024
Basic Currency: CHF
Cash Manager
| Group | Account | Description | Sum In |
|---|---|---|---|
| 1000 | Cash on hand | ||
| Group | Category | Description | Sum In |
|---|---|---|---|
| OPERATING RESULT | |||
| INCOME | |||
| 3000 | Income from sales | 3 | |
| 3090 | Discounts on sales | 3 | |
| 3400 | Income from services | 3 | |
| 3620 | Various Income | 3 | |
| 3 | TOTAL INCOME | 00 | |
| EXPENSES | |||
| 4000 | Purchases | 4 | |
| 4090 | Discounts | 4 | |
| 5000 | Salaries | 4 | |
| 5070 | Social contributions | 4 | |
| 5482 | Representation expenses | 4 | |
| 6000 | Rent | 4 | |
| 6040 | Cleaning expenses | 4 | |
| 6100 | Upkeep | 4 | |
| 6210 | Fuel | 4 | |
| 6220 | Insurances | 4 | |
| 6264 | Rental charges | 4 | |
| 6400 | Electricity | 4 | |
| 6410 | Gas | 4 | |
| 6420 | Heating | 4 | |
| 6430 | Water | 4 | |
| 6500 | Office supplies | 4 | |
| 6510 | Telephone & fax | 4 | |
| 6640 | Transportation | 4 | |
| 6840 | Postage | 4 | |
| 4 | TOTAL EXPENSES | 00 | |
| 00 | TOTAL OPERATING RESULT | ||
Business | Income & Expense accounting
In this article
Business | Income & Expense accounting
Business | Income & Expense accounting
Ideal model for managing the cash flow of a small business, an association, or for auxiliary accounting of projects. Simple and intuitive, based on income and expenses, neatly organized in columns. It can be used even without accounting knowledge. By viewing the Accounts and Categories table, you have everything under control with always up-to-date balances. Professional reports are always possible. Open the model from our WebApp, or from the program, and save the file on your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
The model, while having a simple and essential setup, still allows you to manage accounting professionally.
- You can customize the accounts and categories at any time, adapting it to your specific needs.
- The Accounts and Categories tables provide an immediate overview of the balances for each account and category, allowing you to maintain full control over your financial situation.
- By setting up the customer ledger, you can issue invoices to your clients with the added benefit of having them automatically recorded in your accounting.
- You can speed up the entry of transactions by importing bank data and using Rules: for each imported transaction, you enter a keyword (Rule) that completes all other elements of the transaction (counterparty, cost center...). On subsequent imports, whenever the program finds the keyword in the imported transaction, it completes it automatically, significantly reducing work time and minimizing the risk of errors.
Some features require a subscription to the Advanced plan of Banana Accounting Plus, such as using the new features of Rules, Filter, and Temporary Row Sorting. See all the features of the Advanced plan.
Create your file
- Open the template with the Banana Accounting Plus WebApp.
- Using the command File > File Properties, set the period, your company's name, and the base currency.
- Using the command File > Save As, save the file. It’s helpful to include your company's name and the year in the file name. For example, "Rossi-SA-20xx.ac2".
ATTENTION: If you close the browser without saving, you will lose the entered data. Always save the file to your computer.
In our documentation, you’ll find all the explanations on various topics to help you manage your accounting efficiently:
Template preview
Company XX
Accounting 2024
Basic Currency: CHF
Income & Expense accounting
| Group | Account | Description | Sum In |
|---|---|---|---|
| ESTATE | |||
| 1000 | Cash | 1 | |
| 1010 | Post office current account | 1 | |
| 1020 | Bank 1 | 1 | |
| 1100 | Credits | 1 | |
| 1176 | Withholding tax | 1 | |
| 2000 | Current liabilities short term | 1 | |
| 2400 | Liabilities long term | 1 | |
| 1 | NET ESTATE | ||
| Group | Category | Description | Sum In |
|---|---|---|---|
| OPERATING RESULT | |||
| INCOME | |||
| 3400 | Earnings from services rendered | 3 | |
| 3620 | Other income | 3 | |
| 6950 | Financial revenue | 3 | |
| 3 | TOTAL INCOME | 00 | |
| EXPENSES | |||
| 5000 | Salaries | 4 | |
| 5700 | Social contributions | 4 | |
| 5720 | Contribution to pension funds | 4 | |
| 5730 | Insurance of personnel | 4 | |
| 5820 | Travel expenses-conferences and trainings | 4 | |
| 5850 | Other costs and expenses | 4 | |
| 5900 | Temporary staff | 4 | |
| 5901 | Subcontracting | 4 | |
| 6000 | Rental | 4 | |
| 6100 | Cost of maintenance | 4 | |
| 6200 | Motor vehicle expenses | 4 | |
| 6300 | Car insurance premiums | 4 | |
| 6402 | Electricity | 4 | |
| 6410 | Heating expenses | 4 | |
| 6430 | Water | 4 | |
| 6460 | Garbage | 4 | |
| 6500 | Office supplies | 4 | |
| 6510 | Telephone | 4 | |
| 6600 | Advertising | 4 | |
| 6800 | Depreciation and value adjustments of fixed assets | 4 | |
| 6900 | Financial costs | 4 | |
| 8900 | Taxes | 4 | |
| 4 | TOTAL EXPENSES | 00 | |
| 00 | OPERATING RESULT | ||
Freelance | Income & Expense accounting
In this article
Freelance | Income & Expense accounting
Freelance | Income & Expense accounting
Template to easily and quickly manage the income and expenses of your professional practice. Even if you have no accounting knowledge, this template allows you to maintain your accounts like a professional. Automatically generate Balance Sheets, Income and Expense Reports, cost centers, and segments. You can attach digital documents, such as invoices and receipts, directly to the accounting entry and have them readily available. With the transaction import feature from bank statements and the application of Rules, your accounting is completed in no time. Open the template from our WebApp or the program, and save the file to your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
The Income and Expense Accounting module of Banana Accounting Plus allows you to manage your income and expenses across multiple accounts in a simple, fast, and professional way. While intuitive to use, it delivers professional-level results, as it is based on the same calculation engine as double-entry bookkeeping. This means you can easily generate balance sheets, income and expense reports, and manage cost and profit centers, segments, financial forecasts, and much more.
In the Accounts table, you will find the accounts to manage your resources (cash, equipment, clients, etc.), while in the Categories table, all income and expenses are categorized by item.
Certain functions require a subscription to the Advanced Plan of Banana Accounting Plus, such as the use of new features like Rules, Filter, and Temporary Row Sorting. Discover all the features included in the Advanced Plan.
- Open the template using the WebApp of Banana Accounting.
- Use the File > File Properties command to set the period, the name of your professional practice, and the base currency (you can create budgets and accounting in any currency).
- Use the File > Save As command to save your file. It’s a good idea to include your practice’s name and the year in the file name. For example: Studio Rossi-SA-20xx.ac2.
WARNING: If you close your browser without saving, the data you entered will be lost. Always save the file on your computer.
Quickly Enter Transactions
- Import transactions from your bank, postal, or credit card statements.
- Reminders: Send reminders for overdue payments.
- Reports: Track due dates and payment statuses.
Create Invoices and Track Deadlines
In our Documentation, you’ll find detailed explanations on various topics to help you optimize your accounting:
Template preview
Professional Studio XX
Accounting 2024
Basic Currency: CHF
Income & Expense accounting
| Group | Account | Description | Sum In |
|---|---|---|---|
| ESTATE | |||
| 1000 | Cash | 1 | |
| 1010 | Post office current account | 1 | |
| 1020 | Bank current account | 1 | |
| 1100 | Credits | 1 | |
| 1176 | Withholding tax | 1 | |
| 1510 | Office furniture | 1 | |
| 1520 | Office machines | 1 | |
| 2000 | Current liabilities short term | 1 | |
| 2400 | Liabilities long term | 1 | |
| 1 | NET ESTATE |
| Group | Category | Description | Sum In |
|---|---|---|---|
| OPERATING RESULT | |||
| INCOME | |||
| 3400 | Services/Honoraria | 3 | |
| 3407 | Commissions | 3 | |
| 3680 | Various income | 3 | |
| 3 | TOTAL INCOME | 00 | |
| EXPENSES | |||
| 4090 | Discounts | 4 | |
| 5000 | Salaries employees | 4 | |
| 5700 | Contribution to old age insurance and unemployment | 4 | |
| 5800 | Other personnel expenses | 4 | |
| 6000 | Rent | 4 | |
| 6100 | Cleaning and Upkeep | 4 | |
| 6210 | Fuel | 4 | |
| 6280 | Shipping charges | 4 | |
| 6300 | Insurances | 4 | |
| 6402 | Electricity | 4 | |
| 6410 | Heating expenses | 4 | |
| 6430 | Water | 4 | |
| 6460 | Garbage | 4 | |
| 6500 | Office supplies | 4 | |
| 6510 | Telephone | 4 | |
| 6640 | Transportation | 4 | |
| 6800 | Depreciation and value adjustments of fixed assets | 4 | |
| 6900 | Financial costs | 4 | |
| 8900 | Taxes | 4 | |
| 4 | TOTAL EXPENSES | 00 | |
| 00 | TOTAL OPERATING RESULT | ||
Accounting for sole proprietorship (chart of accounts SME) | Double-entry accounting
In this article
Accounting for sole proprietorship (chart of accounts SME) | Double-entry accounting
Accounting for sole proprietorship (chart of accounts SME) | Double-entry accounting
This template features an SME chart of accounts, structured with subdivisions of accounts into various subtotal groups and general total groups. It follows a step-by-step format, allowing you to view the composition of the financial result even at intermediate stages. Numerous functions enable faster entry of transactions and automatically generate account ledgers, journals, balance sheets, and income statements. Open the template from our WebApp or directly from the program and save the file to your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
Template with SME Chart of Accounts, compliant with the rules established in the Swiss Code of Obligations (Art. 957 and following). Ideal for managing the accounting of a business with an annual turnover of at least CHF 500,000.
- You can customize the accounts to suit your specific needs.
- To streamline data entry, you can use bank data import with the Rules feature: for each imported transaction, you assign a keyword (Rule) and complete all other fields of the record (e.g., counterpart, cost center). For subsequent imports, the program automatically completes the record whenever it detects the keyword in the imported data, significantly reducing work time and minimizing errors.
Many automation features, such as bank data import with Rules, filtering, and other advanced functions, are available exclusively in the Advanced plan of Banana Accounting Plus.
Create Your File
- Open the template using the Banana Accounting Plus WebApp.
- Use the command File > File Properties to set the period, your company name, and the base currency (you can manage your budget and accounting in any currency).
- Use the command File > Save As to save the file. It's helpful to include the company name and year in the file name, e.g., "Rossi-SA-20xx.ac2".
IMPORTANT: If you close your browser without saving, any entered data will be lost. Always save the file to your computer.
In our Documentation, you’ll find all the details and guidance needed to manage your accounting effectively:
Template preview
Company XXX
Accounting 2025
Basic Currency: CHF
Double-entry
| Group | Account | Description | Sum In | Gr1 |
|---|---|---|---|---|
| BALANCE SHEET | ||||
| ASSETS | ||||
| 1000 | Cash on hand | 100 | ||
| 1020 | Bank account | 100 | ||
| 100 | Cash and cash equivalents | 10 | 1 | |
| 1060 | Bonds and stocks | 106 | ||
| 106 | Short-term Assets listed in Stock Exchange | 10 | ||
| 1090 | Internal transfers | 109 | ||
| 1091 | Transfer account for salaries | 109 | ||
| 1099 | Amounts to be clarified | 109 | ||
| 109 | Transfer accounts | 10 | ||
| 1100 | Due from Clients or Debtors | 110 | ||
| 1109 | Provision for Doubtful Debts | 110 | ||
| 110 | Accounts receivable | 10 | ||
| 1140 | Advances and loans | 114 | ||
| 1176 | Withholding tax | 114 | ||
| 1180 | Receivables from social insurances and social security institutions | 114 | ||
| 1188 | Source tax | 114 | ||
| 1190 | Various short-term receivables | 114 | ||
| 1199 | Securities | 114 | ||
| 114 | Other short-term receivables | 10 | ||
| 1200 | Goods for resale | 120 | ||
| 1210 | Raw materials | 120 | ||
| 1220 | Auxiliary material | 120 | ||
| 1230 | Consumables | 120 | ||
| 1260 | Finished products | 120 | ||
| 1270 | In-process products | 120 | ||
| 1280 | Non-invoiced services | 120 | ||
| 120 | Inventories | 10 | 1 | |
| 1300 | Prepaid expenses | 130 | ||
| 1301 | Accrued income | 130 | ||
| 130 | Prepaid Expenses | 10 | 1 | |
| 10 | Current assets | 1 | 1 | |
| 1400 | Bonds and stocks | 140 | ||
| 1440 | Loans | 140 | ||
| 140 | Financial assets | 14 | ||
| 1480 | Investments | 148 | ||
| 148 | Investments | 14 | ||
| 1500 | Machinery | 150 | ||
| 1510 | Office furniture and equipment | 150 | ||
| 1520 | Office machinery, information and communication technology | 150 | ||
| 1530 | Motor vehicles | 150 | ||
| 1540 | Tools and equipment | 150 | ||
| 150 | Tangible assets | 14 | ||
| 1600 | Commercial buildings | 160 | ||
| 160 | Tangible fixed asset management | 14 | ||
| 14 | Fixed Assets | 1 | ||
| 1 | Total Assets | 00 | ||
| LIABILITIES | ||||
| 2000 | Suppliers or creditors | 200 | ||
| 2030 | Deposits received | 200 | ||
| 200 | Suppliers or creditors | 20 | 1 | |
| 2100 | Due to banks short/term | 210 | ||
| 2120 | Financial leasing commitments | 210 | ||
| 2140 | Other onerous debts | 210 | ||
| 210 | Short-term onorous debts | 20 | ||
| 2206 | Withholding tax | 220 | ||
| 2208 | Direct taxes | 220 | ||
| 2210 | Other short-term debts | 220 | ||
| 2270 | Social insurances and social security institutions | 220 | ||
| 2279 | Source tax | 220 | ||
| 220 | Other short-term debts | 20 | ||
| 2300 | Accrued expenses | 230 | ||
| 2301 | Next year's revenues collected | 230 | ||
| 2330 | Short-term provisions | 230 | ||
| 230 | Accruals and deferred income | 20 | ||
| 20 | Short-term third party capital | 2A | ||
| 2400 | Due to banks | 240 | ||
| 2420 | Financial leasing commitments | 240 | ||
| 2430 | Debenture loans | 240 | ||
| 2450 | Loans | 240 | ||
| 2451 | Mortgage | 240 | ||
| 240 | Long-term onorous debts | 24 | ||
| 2500 | Other long-term debts (non-onorous) | 250 | ||
| 250 | Other long-term debts | 24 | ||
| 2600 | Provisions | 260 | ||
| 260 | Provisions and similar statutory posts | 24 | ||
| 24 | Long-term third party capital | 2A | ||
| 2A | Third party capital | 2 | ||
| 2800 | Equity at the beginning of the financial year | 28 | ||
| 2850 | Private account | 28 | ||
| 2970 | Profit / Loss for the year | 28 | ||
| 2891 | Profit/loss for the period | 28 | ||
| 28 | Equity | 2 | ||
| 2 | Total liabilities | 00 | 1 | |
| PROFIT & LOSS STATEMENT | ||||
| 3000 | Earnings from own products | 30 | ||
| 3200 | Earnings from resale | 30 | ||
| 3400 | Earnings from services rendered | 30 | ||
| 3600 | Other revenues and services | 30 | ||
| 3710 | Own consumption | 30 | ||
| 3800 | Decrease in revenues | 30 | ||
| 3805 | Losses on accounts receivable, credit variation | 30 | ||
| 30 | Net revenues from supplies and services | 3 | ||
| 3900 | Change in inventories of in-process products | 39 | ||
| 3901 | Change in inventories of finished products | 39 | ||
| 3940 | Non-invoiced services variations | 39 | ||
| 39 | Change in inventories and Non-invoiced services | 3 | ||
| 3 | Revenues from supplies and services | E1 | ||
| 4000 | Raw materials | 4 | ||
| 4200 | Expenses for goods for resale | 4 | ||
| 4400 | Third party expenses | 4 | ||
| 4500 | Energy consumption for production | 4 | ||
| 4900 | Reduction of costs | 4 | ||
| 4 | Costs for material, goods, services and energy | E1 | ||
| E1 | Gross operating result after deducting costs for materials and goods | E2 | ||
| 5000 | Salaries | 5 | ||
| 5700 | Contribution to old age insurance and unemployment | 5 | ||
| 5710 | Family equalization fund | 5 | ||
| 5720 | Contribution to pension funds | 5 | ||
| 5730 | Contribution to accident insurance | 5 | ||
| 5740 | Contribution to voluntary daily benefits insurance | 5 | ||
| 5790 | Source tax | 5 | ||
| 5800 | Other personnel expenses | 5 | ||
| 5810 | Training of personnel | 5 | ||
| 5820 | Travel and entertainment expenses effective | 5 | ||
| 5830 | Travel and entertainment expense allowance | 5 | ||
| 5900 | Temporary staff | 5 | ||
| 5 | Personnel expenses | E2 | ||
| E2 | Gross operating result after deducting personnel expenses | E3 | ||
| 6000 | Rental | 60 | ||
| 6040 | Cleaning of facilities | 60 | ||
| 60 | Rental | 6 | ||
| 6100 | Maintenance, repairs and replacement of tangible assets | 61 | ||
| 6105 | Leasing costs tangible assets | 61 | ||
| 61 | Maintenance, repairs and replacement of tangible assets | 6 | ||
| 6200 | Repairs | 62 | ||
| 6210 | Fuel | 62 | ||
| 6220 | Car insurance | 62 | ||
| 6260 | Car leasing and rental | 62 | ||
| 6270 | Car costs - private part | 62 | ||
| 6282 | Transportation expenses | 62 | ||
| 62 | Vehicle and transportation expenses | 6 | ||
| 6300 | Insurance for damage of items | 63 | ||
| 63 | Insurance for damage of items | 6 | ||
| 6402 | Electricity | 64 | ||
| 6410 | Heating expenses | 64 | ||
| 6430 | Water | 64 | ||
| 6460 | Garbage | 64 | ||
| 64 | Energy and disposal costs | 6 | ||
| 6500 | Office supplies | 65 | ||
| 6503 | Technical magazines, newspapers, periodicals | 65 | ||
| 6510 | Telephone / internet | 65 | ||
| 6511 | Hosting at third-party | 65 | ||
| 6513 | Postal charges | 65 | ||
| 6570 | IT charges including leasing | 65 | ||
| 6580 | Licenses and updates | 65 | ||
| 6583 | Consumables | 65 | ||
| 65 | Administrative and IT costs | 6 | ||
| 6600 | Advertising | 66 | ||
| 6642 | Gifts to customers | 66 | ||
| 66 | Advertising | 6 | ||
| 6700 | Various costs for the financial year | 67 | ||
| 67 | Various costs for the financial year | 6 | ||
| 6 | Other operating expenses, depreciation, value adjustments and financial results | E3 | ||
| E3 | Operating result before depreciation and value adjustments, financial results and taxes (EBITDA) | E4 | ||
| 6800 | Depreciation and value adjustments of fixed assets | 68 | ||
| 68 | Depreciation and value adjustments of fixed assets | E4 | ||
| E4 | Operating result before financial results and taxes (EBIT) | E5 | ||
| 6900 | Costs for bank interest | 69 | ||
| 6940 | Bank costs | 69 | ||
| 6950 | Financial revenue | 69 | ||
| 69 | Financial costs and revenue | E5 | ||
| E5 | Operating result before taxes (EBT) | E6 | ||
| 7000 | Non-operating revenue | 7 | ||
| 7010 | Non-operating costs | 7 | ||
| 7500 | Corporate real estate revenues | 7 | ||
| 7510 | Corporate real estate costs | 7 | ||
| 7 | Non-operating items | E6 | ||
| 8000 | Extraneous costs | 8 | ||
| 8100 | Extraneous revenue | 8 | ||
| 8500 | Extraordinary, unique costs or costs relating to other accounting periods | 8 | ||
| 8510 | Extraordinary, unique revenue or revenue relating to other accounting periods | 8 | ||
| 8 | Results of extraneous, extraordinary or unique character, or for other accounting periods | E6 | ||
| E6 | Profit or loss before taxes | E7 | ||
| 8900 | Direct taxes | 89 | ||
| 89 | Direct taxes | E7 | ||
| E7 | Annual profit or loss | 2891 | ||
| 00 | Difference should be = 0 (blank cell) | |||
| 1 | ||||
| COST CENTERS | ||||
| .PAC | Packaging A | INV | ||
| .RM | Raw materials A | INV | ||
| .AM | Auxiliairy materials A | INV | ||
| INV | Total inventories | |||
| ,MAN1 | Maintenance 1 | MAN | ||
| ,MAN2 | Maintenance 2 | MAN | ||
| ,MAN3 | Maintenance 3 | MAN | ||
| MAN | Total maintenance | |||
| ;PB1 | Publicity 1 | PU | ||
| ;PB2 | Publicity 2 | PU | ||
| PU | Total publicity | |||
Small businesses with a maximum turnover of CHF 500,000 | Double-entry accounting | Without subgroups
In this article
Small businesses with a maximum turnover of CHF 500,000 | Double-entry accounting | Without subgroups
Small businesses with a maximum turnover of CHF 500,000 | Double-entry accounting | Without subgroups
The template is ideal for accounting with an annual turnover below CHF 500,000. The structure of the chart of accounts is very simple, with accounts summarized in the main groups (assets, liabilities, costs, and revenues) and without subdivisions into subgroups. At the end of the chart of accounts, three cost centers are set up, which can be customized to meet your needs. Once transactions are entered, the program automatically generates account ledgers, journals, balance sheets, and income statements. There are many features to speed up transaction entry, including saved rows and bank data import using Rules. Open the template from our WebApp or directly from the program, and save the file to your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
The program includes numerous features to work efficiently and achieve professional results:
- Import bank statement data for quick and accurate transaction entry.
- Create and print invoices with the Swiss QR code by simply setting up the customer subledger with cost center CC3.
- Set up Rules to save and automate the completion of imported transactions from bank statements.
- Manage cost centers, customizable to your needs, for detailed insights into specific accounts.
- Create budgets and financial forecasts to anticipate cash flow evolution, plan for investments, and simulate profitability.
- Print all the reports you need: Balance sheets, journals, account ledgers, VAT reports, open invoices, and much more.
Many automation features, such as bank data import with Rules, filtering, and other advanced functions, are available exclusively in the Advanced plan of Banana Accounting Plus.
Create Your File
- Open the template using the Banana Accounting Plus WebApp.
- Use the command File > File Properties to set the period, your company name, and the base currency (you can manage your budget and accounting in any currency).
- Use the command File > Save As to save the file. It's helpful to include the company name and year in the file name, e.g., "Rossi-SA-20xx.ac2".
IMPORTANT: If you close your browser without saving, any entered data will be lost. Always save the file to your computer.
In our Documentation, you’ll find all the details and guidance needed to manage your accounting effectively:
Invoice tutorial, revenue accounting | Double-entry accounting
In this article
Invoice tutorial, revenue accounting | Double-entry accounting
Invoice tutorial, revenue accounting | Double-entry accounting
This tutorial shows the innovative method of Banana Accounting Plus to create invoices (in this case, without VAT). To test all the features, open this file, enter your clients' data in the Accounts table, and record the invoice items in the Transactions table, then proceed with printing. By entering both the Debit and Credit accounts, the invoice will automatically be recorded in the accounting system. Open the template from our WebApp or from the program and save the file to your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open tutorial in WebAppTemplate documentation
A simple and brief chart of accounts tutorial, in which we provide examples of transactions to create invoices without VAT. The file also includes the Items table, where you can enter data for the items or services to be invoiced. The data entered in the Items table is automatically retrieved in the Transactions table.
If you want to test the invoice printing functions with QR code, you can start with this template.
Create the file and test the Invoice features.
Open the tutorial with the Banana Accounting WebApp. - Use the command File > File Properties to set the period, your company's name, and the base currency.
- With the command File > Save As, save the file, for example, as "Rossi-SA-20xx.ac2".
- In the Accounts table, enter the details of one of your clients. In the Addresses view, you can complete the information with the full address, country code, and the client's language.
- In the Items table, input the data for your products or services to be invoiced.
- In the Transactions table, you'll find examples of transactions covering various invoicing scenarios. You can delete the rows and enter the details of your invoice. By entering the Debit and Credit accounts, the invoice is simultaneously recorded in the accounting system.
- Select the menu Reports > Customers > Print Invoices, and click OK to preview the documents.
- To explore the different available print templates, consult the Invoice Layouts pages.
- For customizing invoices, refer to the page Advanced Entry - Type Column.
You can find all the information on creating and printing invoices with a QR code on the page Create and Print Invoices with Swiss QR Code.
WARNING: If you close the browser without saving, you will lose the entered data. Always save the file to your computer.
To reopen the saved file, click on File > Open
Additional Resources
- Import data from bank statements
- Set up Rules to store and automate the completion of entries imported from bank statements
- Manage cost centers, customisable to suit your needs for detailed insights into specific accounts
- Create budgets and financial forecasts
- Print all the reports you need: Balance Sheets, Journal, Account Ledgers, VAT Statements, Open Invoices, and much more
For some features, a subscription to the Advanced plan of Banana Accounting Plus is required. For example, this includes using the new features like Rules, Temporary Row Filter, and Sort. Check out all the features available in the Advanced plan.
Template preview
Invoices 2025
Basic Currency: CHF
Double-entry
| Group | Account | Description | Sum In |
|---|---|---|---|
| BALANCE SHEET | |||
| Assets | |||
| 1020 | Bank account | 1 | |
| 10 | Customers ledger | 1 | |
| 1 | Total assets | 00 | |
| Liabilities | |||
| 20 | Suppliers ledger | 2 | |
| 297 | Annual profit or loss | 2 | |
| 2 | Total liabilities | 00 | |
| PROFIT & LOSS STATEMENT | |||
| Revenues & Expenses | |||
| 3000 | Revenues from product A | 4 | |
| 3001 | Revenues from product B | 4 | |
| 3400 | Revenue from services | 4 | |
| 3600 | Other revenues | 4 | |
| 3800 | Discounts | 4 | |
| 4 | Total Revenue & Expenses | 02 | |
| 02 | Profit/Loss for Profit & Loss Statement | 297 | |
| 00 | Difference should be = 0 (blank cell) | ||
| CUSTOMERS LEDGER | |||
| 1100 | Customer A | DEB | |
| 1101 | Customer B | DEB | |
| 1102 | Customer C | DEB | |
| 1103 | Customer D | DEB | |
| 1104 | Customer E | DEB | |
| DEB | Total | 10 | |
| SUPPLIERS LEDGER | |||
| 200001 | Supplier A | SUP | |
| 200002 | Supplier B | SUP | |
| 200003 | Supplier C | SUP | |
| 200004 | Supplier D | SUP | |
| 200005 | Supplier E | SUP | |
| SUP | Total | 20 | |
| Group | Item | Description | Sum In |
|---|---|---|---|
| A00 | Oak chair | 1 | |
| B00 | Oak table | 1 | |
| C00 | Assembly | 1 | |
| 1 | Total | ||
Legal entities, SME, Accounts Receivable/Payable | Double-entry accounting
In this article
Legal entities, SME, Accounts Receivable/Payable | Double-entry accounting
Legal entities, SME, Accounts Receivable/Payable | Double-entry accounting
Turnover-Based Accounting Model for an SA or Sagl Without VAT Obligation. Many automation features significantly reduce working time while delivering professional results. With the automated import of data from bank statements and the Rules, you can enter transactions without errors. The customer and supplier ledger is already set up to create invoices with or without the Swiss QR code, send reminders, and generate reports to monitor deadlines. You can make forecasts, obtain the Balance Sheet and Income Statement, Account Cards, Journal, and many other reports. If you need more detailed information for a sector, branch, or product, you can set up cost/profit centers or adopt segments. Open the model from our WebApp or directly from the program and save the file to your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
Ideal model for managing the accounting of an SA or Sagl without VAT obligation and with an annual turnover equal to or exceeding CHF 500,000. The chart of accounts is structured according to the SME framework and includes the customer/supplier ledger, suitable for those managing accounting based on turnover.
- In the Accounts table, at the end of the chart of accounts, you will find the customer and supplier ledger set up with accounts linked to assets and liabilities, respectively; therefore, the balances will appear in the Balance Sheet.
- All customer and supplier invoices are recorded at the time of issuance and receipt.
Create your File
- Open the template using the Banana Accounting Plus WebApp.
- Use the command File > File Properties to set the period, your company name, and the base currency (you can manage your budget and accounting in any currency).
- Use the command File > Save As to save the file. It's helpful to include the company name and year in the file name, e.g., "Rossi-SA-20xx.ac2".
IMPORTANT: If you close your browser without saving, any entered data will be lost. Always save the file to your computer.
To reopen the saved file, click on File > Open.
- Create invoices to send to customers by using the customer account in the Debit column and the revenue account in the Credit column. This way, the invoice will already be recorded and integrated into your accounting file.
- Record invoices received from suppliers, including scanning QR codes, and create payment orders (pain.001). Pain.001 files are XML messages containing payment details that can be sent to financial institutions supporting this format. More information: Payment orders with pain.001 (available only with the Advanced plan).
- Import all transactions from bank, postal, or credit card statements using Rules for fully automated recordings (available only with the Advanced plan).
- Manage cost centers to obtain detailed insights into specific accounts.
- Create budgets and financial forecasts to monitor cash flow, ensure you can meet future obligations, predict revenues and expenses, and evaluate different scenarios to assess your company’s profitability.
- Print all the reports you need: Balance Sheets, Journal, Account Cards, Open Invoices, and much more.
Some features require a subscription to the Advanced plan of Banana Accounting Plus, such as using the new features Rules, Filter, and Temporary Row Sorting. For more details, check out all the features of the Advanced plan.
In our Documentation, you will find many insights to help you manage accounting like a professional:
Template preview
Company XXX
Accounting 202024
Basic Currency: CHF
Double-entry
| Group | Account | Description | Sum In | Gr1 |
|---|---|---|---|---|
| BALANCE SHEET | ||||
| ASSETS | ||||
| 1000 | Cash on hand | 100 | ||
| 1020 | Bank account | 100 | ||
| 100 | Cash and cash equivalents | 10 | 1 | |
| 1060 | Bonds and stocks | 106 | ||
| 106 | Short-term Assets listed in Stock Exchange | 10 | ||
| 1090 | Internal transfers | 109 | ||
| 1091 | Transfer account for salaries | 109 | ||
| 1099 | Amounts to be clarified | 109 | ||
| 109 | Transfer accounts | 10 | ||
| 1100 | Due from Clients or Debitors | 110 | ||
| 1109 | Provision for Doubtful Debts | 110 | ||
| 110A | Clients or Debtors | 110 | ||
| 110 | Accounts receivable | 10 | ||
| 1140 | Advances and loans | 114 | ||
| 1176 | Withholding tax | 114 | ||
| 1180 | Receivables from social insurances and social security institutions | 114 | ||
| 1188 | Source tax | 114 | ||
| 1190 | Various short-term receivables | 114 | ||
| 1199 | Securities | 114 | ||
| 114 | Other short-term receivables | 10 | ||
| 1200 | Goods for resale | 120 | ||
| 1210 | Raw materials | 120 | ||
| 1220 | Auxiliary material | 120 | ||
| 1230 | Consumables | 120 | ||
| 1260 | Finished products | 120 | ||
| 1270 | In-process products | 120 | ||
| 1280 | Non-invoiced services | 120 | ||
| 120 | Inventories | 10 | 1 | |
| 1300 | Prepaid expenses | 130 | ||
| 1301 | Accrued income | 130 | ||
| 130 | Prepaid Expenses | 10 | 1 | |
| 10 | Current assets | 1 | 1 | |
| 1400 | Bonds and stocks | 140 | ||
| 1440 | Loans | 140 | ||
| 1460 | Loan to share-holder | 140 | ||
| 140 | Financial assets | 14 | ||
| 1480 | Investments | 148 | ||
| 148 | Investments | 14 | ||
| 1500 | Machinery | 150 | ||
| 1510 | Office furniture and equipment | 150 | ||
| 1520 | Office machinery, information and communication technology | 150 | ||
| 1530 | Motor vehicles | 150 | ||
| 1540 | Tools and equipment | 150 | ||
| 150 | Tangible assets | 14 | ||
| 1600 | Commercial buildings | 160 | ||
| 160 | Tangible fixed asset management | 14 | ||
| 1700 | Patents, know-how, licences, rights and development | 170 | ||
| 1710 | Brands | 170 | ||
| 1712 | Models | 170 | ||
| 1770 | Goodwill | 170 | ||
| 170 | Intangible fixed assets | 14 | ||
| 1850 | Share capital, rights not paid or non-paid Foundation capital | 180 | ||
| 180 | Capital or non-paid Foundation capital | 14 | ||
| 14 | Fixed Assets | 1 | ||
| 1 | Total Assets | 00 | ||
| LIABILITIES | ||||
| 2000 | Suppliers or creditors | 200 | ||
| 2030 | Deposits received | 200 | ||
| 200A | Suppliers or creditors | 200 | ||
| 200 | Suppliers or creditors | 20 | 1 | |
| 2100 | Due to banks short/term | 210 | ||
| 2120 | Financial leasing commitments | 210 | ||
| 2140 | Other onerous debts | 210 | ||
| 210 | Short-term onorous debts | 20 | ||
| 2206 | Withholding tax | 220 | ||
| 2208 | Direct taxes | 220 | ||
| 2210 | Other short-term debts | 220 | ||
| 2260 | Due to share-holders | 220 | ||
| 2261 | Dividends | 220 | ||
| 2270 | Social insurances and social security institutions | 220 | ||
| 2279 | Source tax | 220 | ||
| 220 | Other short-term debts | 20 | ||
| 2300 | Accrued expenses | 230 | ||
| 2301 | Next year's revenues collected | 230 | ||
| 2330 | Short-term provisions | 230 | ||
| 230 | Accruals and deferred income | 20 | ||
| 20 | Short-term third party capital | 2A | ||
| 2400 | Due to banks | 240 | ||
| 2420 | Financial leasing commitments | 240 | ||
| 2430 | Debenture loans | 240 | ||
| 2450 | Loans | 240 | ||
| 2451 | Mortgage | 240 | ||
| 240 | Long-term onorous debts | 24 | ||
| 2500 | Other long-term debts (non-onorous) | 250 | ||
| 250 | Other long-term debts | 24 | ||
| 2600 | Provisions | 260 | ||
| 260 | Provisions and similar statutory posts | 24 | ||
| 24 | Long-term third party capital | 2A | ||
| 2A | Third party capital | 2 | ||
| 2800 | Share capital, rights, foundation capital | 280 | ||
| 280 | Capital or capital of the foundation | 28 | ||
| 2900 | Legal reserves | 290 | ||
| 2940 | Revaluation reserves | 290 | ||
| 290 | Legal reserves | 28 | ||
| 2950 | Legal reserve from profit | 295 | ||
| 295 | Legal reserve from profit | 28 | ||
| 2960 | Optional reserves from profit | 296 | ||
| 296 | Optional reserves from profit | 28 | ||
| 2970 | Profit / Loss carried forward | 297 | ||
| 29A | Profit / Loss for the year | 297 | ||
| 297 | Profit / Loss from Balance Sheet | 28 | ||
| 2980 | Treasury stock, shares, rights of investment (negative) | 298 | ||
| 298 | Treasury stock, shares, rights of investment (negative) | 28 | ||
| 28 | Equity | 2 | ||
| 2 | Total liabilities | 00 | 1 | |
| PROFIT & LOSS STATEMENT | ||||
| 3000 | Earnings from own products | 30 | ||
| 3200 | Earnings from resale | 30 | ||
| 3400 | Earnings from services rendered | 30 | ||
| 3600 | Other revenues and services | 30 | ||
| 3710 | Own consumption | 30 | ||
| 3800 | Decrease in revenues | 30 | ||
| 3805 | Losses on accounts receivable, credit variation | 30 | ||
| 30 | Net revenues from supplies and services | 3 | ||
| 3900 | Change in inventories of in-process products | 39 | ||
| 3901 | Change in inventories of finished products | 39 | ||
| 3940 | Non-invoiced services variations | 39 | ||
| 39 | Change in inventories and Non-invoiced services | 3 | ||
| 3 | Revenues from supplies and services | E1 | ||
| 4000 | Raw materials | 4 | ||
| 4200 | Expenses for goods for resale | 4 | ||
| 4400 | Third party expenses | 4 | ||
| 4500 | Energy consumption for production | 4 | ||
| 4900 | Reduction of costs | 4 | ||
| 4 | Costs for material, goods, services and energy | E1 | ||
| E1 | Gross operating result after deducting costs for materials and goods | E2 | ||
| 5000 | Salaries | 5 | ||
| 5700 | Contribution to old age insurance and unemployment | 5 | ||
| 5710 | Family equalization fund | 5 | ||
| 5720 | Contribution to pension funds | 5 | ||
| 5730 | Contribution to accident insurance | 5 | ||
| 5740 | Contribution to voluntary daily benefits insurance | 5 | ||
| 5790 | Source tax | 5 | ||
| 5800 | Other personnel expenses | 5 | ||
| 5810 | Training of personnel | 5 | ||
| 5820 | Travel and entertainment expenses effective | 5 | ||
| 5830 | Travel and entertainment expense allowance | 5 | ||
| 5900 | Temporary staff | 5 | ||
| 5 | Personnel expenses | E2 | ||
| E2 | Gross operating result after deducting personnel expenses | E3 | ||
| 6000 | Rental | 60 | ||
| 6040 | Cleaning of facilities | 60 | ||
| 60 | Rental | 6 | ||
| 6100 | Maintenance, repairs and replacement of tangible assets | 61 | ||
| 6105 | Leasing costs tangible assets | 61 | ||
| 61 | Maintenance, repairs and replacement of tangible assets | 6 | ||
| 6200 | Repairs | 62 | ||
| 6210 | Fuel | 62 | ||
| 6220 | Car insurance | 62 | ||
| 6260 | Car leasing and rental | 62 | ||
| 6270 | Car costs - private part | 62 | ||
| 6282 | Transportation expenses | 62 | ||
| 62 | Vehicle and transportation expenses | 6 | ||
| 6300 | Insurance for damage of items | 63 | ||
| 63 | Insurance for damage of items | 6 | ||
| 6402 | Electricity | 64 | ||
| 6410 | Heating expenses | 64 | ||
| 6430 | Water | 64 | ||
| 6460 | Garbage | 64 | ||
| 64 | Energy and disposal costs | 6 | ||
| 6500 | Office supplies | 65 | ||
| 6503 | Technical magazines, newspapers, periodicals | 65 | ||
| 6510 | Telephone / internet | 65 | ||
| 6511 | Hosting at third-party | 65 | ||
| 6513 | Postal charges | 65 | ||
| 6570 | IT charges including leasing | 65 | ||
| 6580 | Licenses and updates | 65 | ||
| 6583 | Consumables | 65 | ||
| 65 | Administrative and IT costs | 6 | ||
| 6600 | Advertising | 66 | ||
| 6642 | Gifts to customers | 66 | ||
| 66 | Advertising | 6 | ||
| 6700 | Various costs for the financial year | 67 | ||
| 67 | Various costs for the financial year | 6 | ||
| 6 | Other operating expenses, depreciation, value adjustments and financial results | E3 | ||
| E3 | Operating result before depreciation and value adjustments, financial results and taxes (EBITDA) | E4 | ||
| 6800 | Depreciation and value adjustments of fixed assets | 68 | ||
| 68 | Depreciation and value adjustments of fixed assets | E4 | ||
| E4 | Operating result before financial results and taxes (EBIT) | E5 | ||
| 6900 | Costs for bank interest | 69 | ||
| 6940 | Bank costs | 69 | ||
| 6950 | Financial revenue | 69 | ||
| 69 | Financial costs and revenue | E5 | ||
| E5 | Operating result before taxes (EBT) | E6 | ||
| 7000 | Non-operating revenue | 7 | ||
| 7010 | Non-operating costs | 7 | ||
| 7500 | Corporate real estate revenues | 7 | ||
| 7510 | Corporate real estate costs | 7 | ||
| 7 | Non-operating items | E6 | ||
| 8000 | Extraneous costs | 8 | ||
| 8100 | Extraneous revenue | 8 | ||
| 8500 | Extraordinary, unique costs or costs relating to other accounting periods | 8 | ||
| 8510 | Extraordinary, unique revenue or revenue relating to other accounting periods | 8 | ||
| 8 | Results of extraneous, extraordinary or unique character, or for other accounting periods | E6 | ||
| E6 | Profit or loss before taxes | E7 | ||
| 8900 | Direct taxes | 89 | ||
| 89 | Direct taxes | E7 | ||
| E7 | Annual profit or loss | 29A | ||
| 00 | Difference should be = 0 (blank cell) | |||
| CLIENTS/DEBTORS | ||||
| 110001 | Company 1 | DEB1 | ||
| 110002 | Company 2 | DEB1 | ||
| 110003 | Company 3 | DEB1 | ||
| DEB1 | Total Clients/Debtors | 110A | ||
| SUPPLIERS/CREDITORS | ||||
| 200001 | Company 1 | CRE1 | ||
| 200002 | Company 2 | CRE1 | ||
| 200003 | Company 3 | CRE1 | ||
| CRE1 | Total suppliers/Creditors | 200A | ||
| COST CENTERS | ||||
| .PAC | Packaging A | INV | ||
| .RM | Raw materials A | INV | ||
| .AM | Auxiliairy materials A | INV | ||
| INV | Total inventories | |||
| ,MAN1 | Maintenance 1 | MAN | ||
| ,MAN2 | Maintenance 2 | MAN | ||
| ,MAN3 | Maintenance 3 | MAN | ||
| MAN | Total maintenance | |||
| ;PB1 | Publicity 1 | PU | ||
| ;PB2 | Publicity 2 | PU | ||
| PU | Total publicity | |||
Legal entities, SMEs, Customer/Supplier Ledger with CC3 (cash principle) | Double-entry Accounting
In this article
Legal entities, SMEs, Customer/Supplier Ledger with CC3 (cash principle) | Double-entry Accounting
Legal entities, SMEs, Customer/Supplier Ledger with CC3 (cash principle) | Double-entry Accounting
This model is designed to manage the cash-based accounting for a SA or Sagl without VAT obligations. The customer ledger is configured with CC3. Numerous features automate the entry of records, calculations, and VAT reporting, verify and flag errors, and provide outputs such as Balance Sheets and Income Statements, Account Sheets, Journals, financial forecasts and budgets, as well as invoices with Swiss QR codes. Optimize and accelerate your work with professional results. Open the model from our WebApp or directly from the program and save the file on your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
Ideal model for managing cash-based accounting for a SA or Sagl, without VAT liability and with an annual turnover equal to or exceeding CHF 500,000. The chart of accounts is structured according to the SME schema and includes the customer/supplier ledger, suitable for those who use cash-based accounting.
- In the Accounts table, at the end of the chart of accounts, you will find the customer and supplier ledger set up with the cost and profit center CC3. There is no connection with assets and liabilities.
- All invoices from customers and suppliers are recorded in the CC3 cost and profit center accounts.
Create your File
- Open the template using the Banana Accounting Plus WebApp.
- Use the command File > File Properties to set the period, your company name, and the base currency (you can manage your budget and accounting in any currency).
- Use the command File > Save As to save the file. It's helpful to include the company name and year in the file name, e.g., "Rossi-SA-20xx.ac2".
IMPORTANT: If you close your browser without saving, any entered data will be lost. Always save the file to your computer.
To reopen the saved file, click on File > Open.
- Create invoices to send to customers by using the CC3 column in the Transactions table (cost centers view).
- Create Payment Orders (pain.001).The pain.001 files are XML messages that contain the details for making payments and can be sent to financial institutions that recognize this format. For more information, see Payment Orders pain.001 (available only with the Advanced plan).
- Import all transactions from bank, postal, or credit card statements using Rules for fully automated recordings (available only with the Advanced plan).
- Manage cost centers to obtain detailed insights into specific accounts.
- Create budgets and financial forecasts to monitor cash flow, ensure you can meet future obligations, predict revenues and expenses, and evaluate different scenarios to assess your company’s profitability.
- Print all the reports you need: Balance Sheets, Journal, Account Cards, Open Invoices, and much more.
Some features require a subscription to the Advanced plan of Banana Accounting Plus, such as using the new features Rules, Filter, and Temporary Row Sorting. For more details, check out all the features of the Advanced plan.
Template preview
Company XXX
Accounting 2025
Basic Currency: CHF
Double-entry
| Group | Account | Description | Sum In | Gr1 |
|---|---|---|---|---|
| BALANCE SHEET | ||||
| ASSETS | ||||
| 1000 | Cash on hand | 100 | ||
| 1020 | Bank account | 100 | ||
| 1045 | Credit cards / Debit cards | 100 | ||
| 100 | Cash and cash equivalents | 10 | 1 | |
| 1060 | Bonds and stocks | 106 | ||
| 106 | Short-term Assets listed in Stock Exchange | 10 | ||
| 1090 | Internal transfers | 109 | ||
| 1091 | Transfer account for salaries | 109 | ||
| 1099 | Amounts to be clarified | 109 | ||
| 109 | Transfer accounts | 10 | ||
| 1100 | Due from Clients or Debtors | 110 | ||
| 1109 | Provision for Doubtful Debts | 110 | ||
| 110 | Accounts receivable | 10 | ||
| 1140 | Advances and loans | 114 | ||
| 1176 | Withholding tax | 114 | ||
| 1179 | Source tax | 114 | ||
| 1180 | Receivables from social insurances and social security institutions | 114 | ||
| 1190 | Various short-term receivables | 114 | ||
| 1199 | Securities | 114 | ||
| 114 | Other short-term receivables | 10 | ||
| 1200 | Goods for resale | 120 | ||
| 1210 | Raw materials | 120 | ||
| 1230 | Auxiliary material | 120 | ||
| 1231 | Consumables | 120 | ||
| 1260 | Finished products | 120 | ||
| 1270 | In-process products | 120 | ||
| 1280 | Non-invoiced services | 120 | ||
| 120 | Inventories | 10 | 1 | |
| 1300 | Prepaid expenses | 130 | ||
| 1301 | Accrued income | 130 | ||
| 130 | Prepaid Expenses | 10 | 1 | |
| 10 | Current assets | 1 | 1 | |
| 1400 | Bonds and stocks | 140 | ||
| 1440 | Loans | 140 | ||
| 1460 | Loan to shareholder | 140 | ||
| 140 | Financial assets | 14 | ||
| 1480 | Investments | 148 | ||
| 148 | Investments | 14 | ||
| 1500 | Machinery | 150 | ||
| 1510 | Office furniture and equipment | 150 | ||
| 1520 | Office machinery, information and communication technology | 150 | ||
| 1530 | Motor vehicles | 150 | ||
| 1540 | Tools and equipment | 150 | ||
| 150 | Movable tangible assets | 14 | ||
| 1600 | Commercial buildings | 160 | ||
| 160 | Fixed tangible assets | 14 | ||
| 1700 | Patents, know-how, licences, rights and development | 170 | ||
| 1710 | Brands | 170 | ||
| 1712 | Models | 170 | ||
| 1770 | Goodwill | 170 | ||
| 170 | Intangible fixed assets | 14 | ||
| 1850 | Unpaid share capital, nominal capital, participation certificate capital or foundation capital | 180 | ||
| 180 | Unpaid share capital or foundation capital | 14 | ||
| 14 | Fixed assets | 1 | ||
| 1 | Total assets | 00 | ||
| LIABILITIES | ||||
| 2000 | Suppliers or creditors | 200 | ||
| 2030 | Deposits received | 200 | ||
| 200 | Suppliers or creditors | 20 | 1 | |
| 2100 | Due to banks short/term | 210 | ||
| 2120 | Financial leasing commitments | 210 | ||
| 2140 | Other onerous debts | 210 | ||
| 210 | Short-term interest-bearing debts | 20 | ||
| 2206 | Withholding tax | 220 | ||
| 2208 | Direct taxes | 220 | ||
| 2210 | Other short-term debts | 220 | ||
| 2260 | Due to share-holders | 220 | ||
| 2261 | Dividends | 220 | ||
| 2270 | Social insurances and social security institutions | 220 | ||
| 2279 | Source tax | 220 | ||
| 220 | Other short-term debts | 20 | ||
| 2300 | Accrued expenses | 230 | ||
| 2301 | Next year's revenues collected | 230 | ||
| 2330 | Short-term provisions | 230 | ||
| 230 | Accruals and deferred income | 20 | ||
| 20 | Short-term third party capital | 2A | ||
| 2400 | Due to banks | 240 | ||
| 2420 | Financial leasing commitments | 240 | ||
| 2430 | Debenture loans | 240 | ||
| 2450 | Loans | 240 | ||
| 2451 | Mortgage | 240 | ||
| 240 | Long-term onerous debts | 24 | ||
| 2500 | Other long-term debts (non-onerous) | 250 | ||
| 250 | Other long-term debts | 24 | ||
| 2600 | Provisions | 260 | ||
| 260 | Provisions and similar statutory posts | 24 | ||
| 24 | Long-term third party capital | 2A | ||
| 2A | Third party capital | 2 | ||
| 2800 | Share capital, nominal capital, participation certificate capital or foundation capital | 280 | ||
| 280 | Share capital or capital of the foundation | 28 | ||
| 2900 | Premium at foundation or in the event of a capital increase | 290 | ||
| 2903 | Reserves from capital contributions | 290 | ||
| 2950 | Legal retained earnings | 290 | ||
| 2955 | Revaluation reserve | 290 | ||
| 2960 | Optional reserves from profit | 290 | ||
| 290 | Reserves | 28 | ||
| 2965 | Treasury stock, shares, rights of investment (negative) | 296 | ||
| 296 | Treasury stock, shares, rights of investment (negative) | 28 | ||
| 2970 | Profit / Loss carried forward | 297 | ||
| 2979 | Profit / Loss for the year | 297 | ||
| 297 | Profit / Loss from Balance Sheet | 28 | ||
| 28 | Equity | 2 | ||
| 2 | Total liabilities | 00 | 1 | |
| PROFIT & LOSS STATEMENT | ||||
| 3000 | Earnings from own products | 30 | ||
| 3200 | Earnings from resale | 30 | ||
| 3400 | Earnings from services rendered | 30 | ||
| 3600 | Other revenues and services | 30 | ||
| 3710 | Own consumption | 30 | ||
| 3800 | Decrease in revenues | 30 | ||
| 3805 | Losses on accounts receivable, credit variation | 30 | ||
| 3810 | Credit/debit card fees | 30 | ||
| 30 | Net revenues from supplies and services | 3 | ||
| 3900 | Changes in finished products inventories | 39 | ||
| 3901 | Changes in semi-finished products inventories | 39 | ||
| 3940 | Changes in non-invoiced services value | 39 | ||
| 39 | Change in inventories and non-invoiced services | 3 | ||
| 3 | Revenues from supplies and services | E1 | ||
| 4000 | Raw materials | 4 | ||
| 4200 | Expenses for goods for resale | 4 | ||
| 4400 | Third party expenses | 4 | ||
| 4500 | Energy consumption for production | 4 | ||
| 4800 | Reduction of costs | 4 | ||
| 4 | Costs for material, goods, services and energy | E1 | ||
| E1 | Gross operating result after deducting costs for materials and goods | E2 | ||
| 5000 | Salaries | 5 | ||
| 5700 | Contribution to old age insurance and unemployment | 5 | ||
| 5710 | Family equalization fund | 5 | ||
| 5720 | Contribution to pension funds | 5 | ||
| 5730 | Contribution to accident insurance | 5 | ||
| 5740 | Daily sickness benefits insurance | 5 | ||
| 5790 | Source tax | 5 | ||
| 5800 | Other personnel expenses | 5 | ||
| 5810 | Training of personnel | 5 | ||
| 5820 | Travel and entertainment expenses effective | 5 | ||
| 5830 | Travel and entertainment expense allowance | 5 | ||
| 5900 | Temporary staff | 5 | ||
| 5 | Personnel expenses | E2 | ||
| E2 | Gross operating result after deducting personnel expenses | E3 | ||
| 6000 | Rental | 60 | ||
| 6040 | Cleaning of facilities | 60 | ||
| 60 | Rental | 6 | ||
| 6100 | Maintenance, repairs and replacement of movable tangible assets | 61 | ||
| 6105 | Leasing costs of movable tangible assets | 61 | ||
| 61 | Maintenance, repairs and replacement of movable tangible assets | 6 | ||
| 6200 | Repairs | 62 | ||
| 6210 | Fuel | 62 | ||
| 6220 | Car insurance | 62 | ||
| 6260 | Car leasing and rental | 62 | ||
| 6270 | Private share of vehicle expenses | 62 | ||
| 6280 | Transportation expenses | 62 | ||
| 62 | Vehicle and transportation expenses | 6 | ||
| 6300 | Insurance for damage of items | 63 | ||
| 63 | Insurance for damage of items | 6 | ||
| 6402 | Electricity | 64 | ||
| 6410 | Heating expenses | 64 | ||
| 6430 | Water | 64 | ||
| 6460 | Garbage | 64 | ||
| 64 | Energy and disposal costs | 6 | ||
| 6500 | Office supplies | 65 | ||
| 6503 | Technical magazines, newspapers, periodicals | 65 | ||
| 6510 | Telephone / internet | 65 | ||
| 6511 | Hosting at third-party | 65 | ||
| 6513 | Postal charges | 65 | ||
| 6570 | IT charges including leasing | 65 | ||
| 6580 | Licenses and updates | 65 | ||
| 6583 | Consumables | 65 | ||
| 65 | Administrative and IT costs | 6 | ||
| 6600 | Advertising | 66 | ||
| 6642 | Gifts to customers | 66 | ||
| 66 | Advertising | 6 | ||
| 6700 | Various costs for the financial year | 67 | ||
| 67 | Various costs for the financial year | 6 | ||
| 6 | Other operating expenses, depreciation, value adjustments and financial results | E3 | ||
| E3 | Operating result before depreciation and value adjustments, financial results and taxes (EBITDA) | E4 | ||
| 6800 | Depreciation and value adjustments of fixed assets | 68 | ||
| 68 | Depreciation and value adjustments of fixed assets | E4 | ||
| E4 | Operating result before financial results and taxes (EBIT) | E5 | ||
| 6900 | Costs for bank interest | 69 | ||
| 6940 | Bank costs | 69 | ||
| 6950 | Financial revenue | 69 | ||
| 69 | Financial costs and revenue | E5 | ||
| E5 | Operating result before taxes (EBT) | E6 | ||
| 7000 | Non-operating revenue | 7 | ||
| 7010 | Non-operating costs | 7 | ||
| 7500 | Corporate real estate revenues | 7 | ||
| 7510 | Corporate real estate costs | 7 | ||
| 7 | Result from non-operating activities | E6 | ||
| 8000 | Extraneous costs | 8 | ||
| 8100 | Extraneous revenue | 8 | ||
| 8500 | Extraordinary, unique costs or costs relating to other accounting periods | 8 | ||
| 8510 | Extraordinary, unique revenue or revenue relating to other accounting periods | 8 | ||
| 8 | Results of extraneous, extraordinary or unique character, or for other accounting periods | E6 | ||
| E6 | Profit or loss before taxes | E7 | ||
| 8900 | Direct taxes | 89 | ||
| 89 | Direct taxes | E7 | ||
| E7 | Annual profit or loss | 2979 | 1 | |
| 00 | Difference should be = 0 (blank cell) | |||
| Clients ledger | ||||
| ;110001 | Bianchi Ltd. | CLI | ||
| ;110002 | Rossi Francesco | CLI | ||
| ;110003 | John Smith | CLI | ||
| ;110004 | Rossier Anne | CLI | ||
| ;110005 | Müller Ltd. | CLI | ||
| CLI | Total clients | |||
| Suppliers ledger | ||||
| ;200001 | Alberti Sergio | SUP | ||
| ;200002 | Fumagalli Lorenzo | SUP | ||
| ;200003 | Color Ltd. | SUP | ||
| ;200004 | Martini LLC. | SUP | ||
| SUP | Total suppliers | |||
| COST CENTERS | ||||
| .PAC | Packaging A | INV | ||
| .RM | Raw materials A | INV | ||
| .AM | Auxiliairy materials A | INV | ||
| INV | Total inventories | |||
| ,MAN1 | Maintenance 1 | MAN | ||
| ,MAN2 | Maintenance 2 | MAN | ||
| ,MAN3 | Maintenance 3 | MAN | ||
| MAN | Total maintenance | |||
| ;PB1 | Publicity 1 | PU | ||
| ;PB2 | Publicity 2 | PU | ||
| PU | Total publicity | |||
| Group | Item | Description | Sum In |
|---|---|---|---|
| AD-1 | Chairs category A | 10 | |
| AD-2 | Chairs category B | 10 | |
| 10 | Total chairs category A and B | ||
| AB-1 | Tables category A | 12 | |
| AB-2 | Tables category B | 12 | |
| 12 | Total tables category A and B | ||
Partnerships, general and limited , SMEs, cash-based accounting | Double-entry accounting
In this article
Partnerships, general and limited , SMEs, cash-based accounting | Double-entry accounting
Partnerships, general and limited , SMEs, cash-based accounting | Double-entry accounting
Ideal model for managing a partnership’s accounting. The chart of accounts is structured according to the Swiss SME system. By using Banana Accounting, you can take advantage of many innovative features that make your work fast, secure, and professional. You can plan and anticipate cash flows, ensuring that you can meet future commitments without difficulty. You can manage customers and suppliers, create invoices with a Swiss QR code, track deadlines, and send reminders. Data is always up to date for the Balance Sheet, Profit and Loss Statement, Account Cards, Journal, and other reports—even by period. Get detailed information for a specific area by using cost centers, and attach digital documents to transactions for better organisation and immediate visibility, without having to consult paper documents. Open the model from our WebApp, or directly from the program, and save the file on your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
- Create and print invoices with the Swiss QR code
- Import data from bank statements
- Set up Rules to memorise and automate the completion of transactions imported from bank statements
- Manage VAT according to the new VAT rates
- Manage cost centers, customisable according to your needs, to get detailed information on specific accounts
- Create budgets and financial forecasts
- Print all the reports you need: Balance Sheets, Journal, Account Cards, VAT Returns, Open Invoices, and much more.
For VAT management with the new rates, you can find detailed information in the VAT Management pages on our website.
Some features require a subscription to the Advanced plan of Banana Accounting Plus, such as using the new features Rules, Filter, and Temporary Row Sorting. For more details, check out all the features of the Advanced plan.
In the equity section of the liabilities, you will find the accounts for managing each partner’s capital, contributions, private portion, and profits.
Create your File
- Open the template using the Banana Accounting Plus WebApp.
Use the command File > File Properties to set the period, your company name, and the base currency (you can manage your budget and accounting in any currency).
Use the command File > Save As to save the file. It's helpful to include the company name and year in the file name, e.g., "Rossi-SA-20xx.ac2".
IMPORTANT: If you close your browser without saving, any entered data will be lost. Always save the file to your computer.
In our Documentation, you'll find a wealth of information to help you manage your accounting like a professional and discover the full potential of the program:
Template preview
Company XXX
Accounting 2024
Basic Currency: CHF
Double-entry
| Group | Account | Description | Sum In | Gr1 |
|---|---|---|---|---|
| BALANCE SHEET | ||||
| ASSETS | ||||
| 1000 | Cash on hand | 100 | ||
| 1020 | Bank account | 100 | ||
| 100 | Cash and cash equivalents | 10 | 1 | |
| 1060 | Bonds and stocks | 106 | ||
| 106 | Short-term Assets listed in Stock Exchange | 10 | ||
| 1090 | Internal transfers | 109 | ||
| 1091 | Transfer account for salaries | 109 | ||
| 1099 | Amounts to be clarified | 109 | ||
| 109 | Transfer accounts | 10 | ||
| 1100 | Due from Clients or Debtors | 110 | ||
| 1109 | Provision for Doubtful Debts | 110 | ||
| 110 | Accounts receivable | 10 | ||
| 1140 | Advances and loans | 114 | ||
| 1176 | Withholding tax | 114 | ||
| 1180 | Receivables from social insurances and social security institutions | 114 | ||
| 1188 | Source tax | 114 | ||
| 1190 | Various short-term receivables | 114 | ||
| 1199 | Securities | 114 | ||
| 114 | Other short-term receivables | 10 | ||
| 1200 | Goods for resale | 120 | ||
| 1210 | Raw materials | 120 | ||
| 1220 | Auxiliary material | 120 | ||
| 1230 | Consumables | 120 | ||
| 1260 | Finished products | 120 | ||
| 1270 | In-process products | 120 | ||
| 1280 | Non-invoiced services | 120 | ||
| 120 | Inventories | 10 | 1 | |
| 1300 | Prepaid expenses | 130 | ||
| 1301 | Accrued income | 130 | ||
| 130 | Prepaid Expenses | 10 | 1 | |
| 10 | Current assets | 1 | 1 | |
| 1400 | Bonds and stocks | 140 | ||
| 1440 | Loans | 140 | ||
| 1460 | Loan to partner | 140 | ||
| 140 | Financial assets | 14 | ||
| 1480 | Investments | 148 | ||
| 148 | Investments | 14 | ||
| 1500 | Machinery | 150 | ||
| 1510 | Office furniture and equipment | 150 | ||
| 1520 | Office machinery, information and communication technology | 150 | ||
| 1530 | Motor vehicles | 150 | ||
| 1540 | Tools and equipment | 150 | ||
| 150 | Tangible assets | 14 | ||
| 1600 | Commercial buildings | 160 | ||
| 160 | Tangible fixed asset management | 14 | ||
| 1700 | Patents, know-how, licences, rights and development | 170 | ||
| 1710 | Brands | 170 | ||
| 1712 | Models | 170 | ||
| 1770 | Goodwill | 170 | ||
| 170 | Intangible fixed assets | 14 | ||
| 1850 | Share capital, rights not paid or non-paid Foundation capital | 180 | ||
| 180 | Capital or non-paid Foundation capital | 14 | ||
| 14 | Fixed Assets | 1 | ||
| 1 | Total Assets | 00 | ||
| LIABILITIES | ||||
| 2000 | Suppliers or creditors | 200 | ||
| 2030 | Deposits received | 200 | ||
| 200 | Suppliers or creditors | 20 | 1 | |
| 2100 | Due to banks short/term | 210 | ||
| 2120 | Financial leasing commitments | 210 | ||
| 2140 | Other onerous debts | 210 | ||
| 210 | Short-term onorous debts | 20 | ||
| 2206 | Withholding tax | 220 | ||
| 2208 | Direct taxes | 220 | ||
| 2210 | Other short-term debts | 220 | ||
| 2260 | Due to partner | 220 | ||
| 2270 | Social insurances and social security institutions | 220 | ||
| 2279 | Source tax | 220 | ||
| 220 | Other short-term debts | 20 | ||
| 2300 | Accrued expenses | 230 | ||
| 2301 | Next year's revenues collected | 230 | ||
| 2330 | Short-term provisions | 230 | ||
| 230 | Accruals and deferred income | 20 | ||
| 20 | Short-term third party capital | 2A | ||
| 2400 | Due to banks | 240 | ||
| 2420 | Financial leasing commitments | 240 | ||
| 2430 | Debenture loans | 240 | ||
| 2450 | Loans | 240 | ||
| 2451 | Mortgage | 240 | ||
| 240 | Long-term onorous debts | 24 | ||
| 2500 | Other long-term debts (non-onorous) | 250 | ||
| 250 | Other long-term debts | 24 | ||
| 2600 | Provisions | 260 | ||
| 260 | Provisions and similar statutory posts | 24 | ||
| 24 | Long-term third party capital | 2A | ||
| 2A | Third party capital | 2 | ||
| 2800 | Equity partner A at the beginning of the year | 28 | ||
| 2810 | Contributions to equity/equity withdrawals partner A | 28 | ||
| 2820 | Private account partner A | 28 | ||
| 2831 | Profit / Loss for the year partner A | 28 | ||
| 2850 | Equity sponsor A at the beginning of the year | 28 | ||
| 2860 | Contributions to equity/equity withdrawals sponsor A | 28 | ||
| 2870 | Private account sponsor A | 28 | ||
| 2881 | Profit / Loss for the year sponsor A | 28 | ||
| 297 | Profit/loss for the period | 28 | ||
| 28 | Equity | 2 | ||
| 2 | Total liabilities | 00 | 1 | |
| PROFIT & LOSS STATEMENT | ||||
| 3000 | Earnings from own products | 30 | ||
| 3200 | Earnings from resale | 30 | ||
| 3400 | Earnings from services rendered | 30 | ||
| 3600 | Other revenues and services | 30 | ||
| 3710 | Own consumption | 30 | ||
| 3800 | Decrease in revenues | 30 | ||
| 3805 | Losses on accounts receivable, credit variation | 30 | ||
| 30 | Net revenues from supplies and services | 3 | ||
| 3900 | Change in inventories of in-process products | 39 | ||
| 3901 | Change in inventories of finished products | 39 | ||
| 3940 | Non-invoiced services variations | 39 | ||
| 39 | Change in inventories and Non-invoiced services | 3 | ||
| 3 | Revenues from supplies and services | E1 | ||
| 4000 | Raw materials | 4 | ||
| 4200 | Expenses for goods for resale | 4 | ||
| 4400 | Third party expenses | 4 | ||
| 4500 | Energy consumption for production | 4 | ||
| 4900 | Reduction of costs | 4 | ||
| 4 | Costs for material, goods, services and energy | E1 | ||
| E1 | Gross operating result after deducting costs for materials and goods | E2 | ||
| 5000 | Salaries | 5 | ||
| 5700 | Contribution to old age insurance and unemployment | 5 | ||
| 5710 | Family equalization fund | 5 | ||
| 5720 | Contribution to pension funds | 5 | ||
| 5730 | Contribution to accident insurance | 5 | ||
| 5740 | Contribution to voluntary daily benefits insurance | 5 | ||
| 5790 | Source tax | 5 | ||
| 5800 | Other personnel expenses | 5 | ||
| 5810 | Training of personnel | 5 | ||
| 5820 | Travel and entertainment expenses effective | 5 | ||
| 5830 | Travel and entertainment expense allowance | 5 | ||
| 5900 | Temporary staff | 5 | ||
| 5 | Personnel expenses | E2 | ||
| E2 | Gross operating result after deducting personnel expenses | E3 | ||
| 6000 | Rental | 60 | ||
| 6040 | Cleaning of facilities | 60 | ||
| 60 | Rental | 6 | ||
| 6100 | Maintenance, repairs and replacement of tangible assets | 61 | ||
| 6105 | Leasing costs tangible assets | 61 | ||
| 61 | Maintenance, repairs and replacement of tangible assets | 6 | ||
| 6200 | Repairs | 62 | ||
| 6210 | Fuel | 62 | ||
| 6220 | Car insurance | 62 | ||
| 6260 | Car leasing and rental | 62 | ||
| 6270 | Car costs - private part | 62 | ||
| 6282 | Transportation expenses | 62 | ||
| 62 | Vehicle and transportation expenses | 6 | ||
| 6300 | Insurance for damage of items | 63 | ||
| 63 | Insurance for damage of items | 6 | ||
| 6402 | Electricity | 64 | ||
| 6410 | Heating expenses | 64 | ||
| 6430 | Water | 64 | ||
| 6460 | Garbage | 64 | ||
| 64 | Energy and disposal costs | 6 | ||
| 6500 | Office supplies | 65 | ||
| 6503 | Technical magazines, newspapers, periodicals | 65 | ||
| 6510 | Telephone / internet | 65 | ||
| 6511 | Hosting at third-party | 65 | ||
| 6513 | Postal charges | 65 | ||
| 6570 | IT charges including leasing | 65 | ||
| 6580 | Licenses and updates | 65 | ||
| 6583 | Consumables | 65 | ||
| 65 | Administrative and IT costs | 6 | ||
| 6600 | Advertising | 66 | ||
| 6642 | Gifts to customers | 66 | ||
| 66 | Advertising | 6 | ||
| 6700 | Various costs for the financial year | 67 | ||
| 67 | Various costs for the financial year | 6 | ||
| 6 | Other operating expenses, depreciation, value adjustments and financial results | E3 | ||
| E3 | Operating result before depreciation and value adjustments, financial results and taxes (EBITDA) | E4 | ||
| 6800 | Depreciation and value adjustments of fixed assets | 68 | ||
| 68 | Depreciation and value adjustments of fixed assets | E4 | ||
| E4 | Operating result before financial results and taxes (EBIT) | E5 | ||
| 6900 | Costs for bank interest | 69 | ||
| 6940 | Bank costs | 69 | ||
| 6950 | Financial revenue | 69 | ||
| 69 | Financial costs and revenue | E5 | ||
| E5 | Operating result before taxes (EBT) | E6 | ||
| 7000 | Non-operating revenue | 7 | ||
| 7010 | Non-operating costs | 7 | ||
| 7500 | Corporate real estate revenues | 7 | ||
| 7510 | Corporate real estate costs | 7 | ||
| 7 | Non-operating items | E6 | ||
| 8000 | Extraneous costs | 8 | ||
| 8100 | Extraneous revenue | 8 | ||
| 8500 | Extraordinary, unique costs or costs relating to other accounting periods | 8 | ||
| 8510 | Extraordinary, unique revenue or revenue relating to other accounting periods | 8 | ||
| 8 | Results of extraneous, extraordinary or unique character, or for other accounting periods | E6 | ||
| E6 | Profit or loss before taxes | E7 | ||
| 8900 | Direct taxes | 89 | ||
| 89 | Direct taxes | E7 | ||
| E7 | Annual profit or loss | 297 | ||
| 00 | Difference should be = 0 (blank cell) | |||
| 1 | ||||
| COST CENTERS | ||||
| .PAC | Packaging A | INV | ||
| .RM | Raw materials A | INV | ||
| .AM | Auxiliairy materials A | INV | ||
| INV | Total inventories | |||
| ,MAN1 | Maintenance 1 | MAN | ||
| ,MAN2 | Maintenance 2 | MAN | ||
| ,MAN3 | Maintenance 3 | MAN | ||
| MAN | Total maintenance | |||
| ;PB1 | Publicity 1 | PU | ||
| ;PB2 | Publicity 2 | PU | ||
| PU | Total publicity | |||
Company with Customers/Suppliers | Double-Entry Accounting with Multi-Currency
In this article
Company with Customers/Suppliers | Double-Entry Accounting with Multi-Currency
Company with Customers/Suppliers | Double-Entry Accounting with Multi-Currency
Ideal model for the accounting of an SA or Sagl designed for companies with an annual turnover of CHF 500,000 or more, including accounts in foreign currencies. The file, based on double-entry accounting, includes an Exchange Rates table and columns to manage accounts in foreign currencies. For each currency, you can set the exchange rate freely, and every time you record a transaction, the program automatically calculates the equivalent value in the base currency. Exchange rate differences are also calculated automatically. You have access to features for automated checks and controls to prevent errors. If you need to present reports and balance sheets abroad, you can set up accounting in a second currency to display balances in both the base currency and the secondary currency. Open the model from our WebApp or directly in the program, and save the file on your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
- Model for managing the accounting of an SA or Sagl with VAT and an annual turnover equal to or exceeding CHF 500,000. The chart of accounts is structured according to the SME scheme and includes customer/supplier ledgers, ideal for companies that manage accounting based on turnover.
- In the Accounts Table, at the end of the chart of accounts, you will find the customer and supplier ledgers set up with accounts linked to assets and liabilities, respectively; thus, the balances will appear in the Balance Sheet.
- All customer and supplier invoices are recorded at the time of issuance and receipt.
Create your File
- Open the template using the Banana Accounting Plus WebApp.
Use the command File > File Properties to set the period, your company name, and the base currency (you can manage your budget and accounting in any currency).
Use the command File > Save As to save the file. It's helpful to include the company name and year in the file name, e.g., "Rossi-SA-20xx.ac2".
IMPORTANT: If you close your browser without saving, any entered data will be lost. Always save the file to your computer.
- In the Exchange Rates table, set foreign currencies always in reference to the base currency and their exchange rates. Opening rates are set only the first time you use Banana Accounting. At the transition to the new year, these rates will be automatically carried over based on the closing rates entered as of 31.12.
- In the Chart of Accounts, set up your accounts in foreign currencies and the account for recording exchange rate differences.
- In the File Properties (Basic Data), under the Foreign Currency section, indicate the accounts for exchange rate differences and, if necessary, set up a second currency for your accounting.
- In the Exchange Rates table, set the rates for foreign currencies.
You are ready to register!
You can register all possible cases of foreign currency transactions, including transfers and operations that do not involve the base currency.
In our Documentation, you will find detailed explanations and topics on multi-currency accounting, particularly:
Template preview
Company XXX
Accounting 2024
Basic Currency: CHF
Double-entry with foreign currencies
| Group | Account | Description | Currency | Sum In | Gr1 |
|---|---|---|---|---|---|
| BALANCE SHEET | |||||
| ASSETS | |||||
| 1000 | Cash on hand | CHF | 100 | ||
| 1020 | Bank account | CHF | 100 | ||
| 1024 | Bank account Euro | EUR | 100 | ||
| 1025 | Bank account USD | USD | 100 | ||
| 100 | Cash and cash equivalents | 10 | 1 | ||
| 1060 | Bonds and stocks | CHF | 106 | ||
| 106 | Short-term Assets listed in Stock Exchange | 10 | |||
| 1090 | Internal transfers | CHF | 109 | ||
| 1091 | Transfer account for salaries | CHF | 109 | ||
| 1099 | Amounts to be clarified | CHF | 109 | ||
| 109 | Transfer accounts | 10 | |||
| 1100 | Due from Clients or Debitors | CHF | 110 | ||
| 1109 | Provision for Doubtful Debts | CHF | 110 | ||
| 110A | Clients or Debtors | 110 | |||
| 110 | Accounts receivable | 10 | |||
| 1140 | Advances and loans | CHF | 114 | ||
| 1176 | Withholding tax | CHF | 114 | ||
| 1180 | Receivables from social insurances and social security institutions | CHF | 114 | ||
| 1188 | Source tax | CHF | 114 | ||
| 1190 | Various short-term receivables | CHF | 114 | ||
| 1191 | Securities | CHF | 114 | ||
| 114 | Other short-term receivables | 10 | |||
| 1200 | Goods for resale | CHF | 120 | ||
| 1210 | Raw materials | CHF | 120 | ||
| 1220 | Auxiliary material | CHF | 120 | ||
| 1230 | Consumables | CHF | 120 | ||
| 1260 | Finished products | CHF | 120 | ||
| 1270 | In-process products | CHF | 120 | ||
| 1280 | Non-invoiced services | CHF | 120 | ||
| 120 | Inventories | 10 | 1 | ||
| 1300 | Prepaid expenses | CHF | 130 | ||
| 1301 | Accrued income | CHF | 130 | ||
| 130 | Prepaid Expenses | 10 | 1 | ||
| 10 | Current assets | 1 | 1 | ||
| 1400 | Bonds and stocks | CHF | 140 | ||
| 1440 | Loans | CHF | 140 | ||
| 1460 | Loan to share-holder | CHF | 140 | ||
| 140 | Financial assets | 14 | |||
| 1480 | Investments | CHF | 148 | ||
| 148 | Investments | 14 | |||
| 1500 | Machinery | CHF | 150 | ||
| 1510 | Office furniture and equipment | CHF | 150 | ||
| 1520 | Office machinery, information and communication technology | CHF | 150 | ||
| 1530 | Motor vehicles | CHF | 150 | ||
| 1540 | Tools and equipment | CHF | 150 | ||
| 150 | Tangible assets | 14 | |||
| 1600 | Commercial buildings | CHF | 160 | ||
| 160 | Tangible fixed asset management | 14 | |||
| 1700 | Patents, know-how, licences, rights and development | CHF | 170 | ||
| 1710 | Brands | CHF | 170 | ||
| 1712 | Models | CHF | 170 | ||
| 1770 | Goodwill | CHF | 170 | ||
| 170 | Intangible fixed assets | 14 | |||
| 1850 | Share capital, rights not paid or non-paid Foundation capital | CHF | 180 | ||
| 180 | Capital or non-paid Foundation capital | 14 | |||
| 14 | Fixed Assets | 1 | |||
| 1 | Total Assets | 00 | |||
| LIABILITIES | |||||
| 2000 | Suppliers or creditors | CHF | 200 | ||
| 2030 | Deposits received | CHF | 200 | ||
| 200A | Suppliers or creditors | 200 | |||
| 200 | Suppliers or creditors | 20 | 1 | ||
| 2100 | Due to banks short/term | CHF | 210 | ||
| 2120 | Financial leasing commitments | CHF | 210 | ||
| 2140 | Other onerous debts | CHF | 210 | ||
| 210 | Short-term onorous debts | 20 | |||
| 2200 | VAT Due | CHF | 220 | ||
| 2201 | VAT according to VAT report | CHF | 220 | ||
| 2206 | Withholding tax | CHF | 220 | ||
| 2208 | Direct taxes | CHF | 220 | ||
| 2210 | Other short-term debts | CHF | 220 | ||
| 2260 | Due to share-holder | CHF | 220 | ||
| 2261 | Dividends | CHF | 220 | ||
| 2270 | Social insurances and social security institutions | CHF | 220 | ||
| 2279 | Source tax | CHF | 220 | ||
| 220 | Other short-term debts | 20 | |||
| 2300 | Accrued expenses | CHF | 230 | ||
| 2301 | Next year's revenues collected | CHF | 230 | ||
| 2330 | Short-term provisions | CHF | 230 | ||
| 230 | Accruals and deferred income | 20 | |||
| 20 | Short-term third party capital | 2A | |||
| 2400 | Due to banks | CHF | 240 | ||
| 2420 | Financial leasing commitments | CHF | 240 | ||
| 2430 | Debenture loans | CHF | 240 | ||
| 2450 | Loans | CHF | 240 | ||
| 2451 | Mortgage | CHF | 240 | ||
| 240 | Long-term onorous debts | 24 | |||
| 2500 | Other long-term debts (non-onorous) | CHF | 250 | ||
| 250 | Other long-term debts | 24 | |||
| 2600 | Provisions | CHF | 260 | ||
| 260 | Provisions and similar statutory posts | 24 | |||
| 24 | Long-term third party capital | 2A | |||
| 2A | Third party capital | 2 | |||
| 2800 | Share capital, rights, foundation capital | CHF | 280 | ||
| 280 | Capital or capital of the foundation | 28 | |||
| 2900 | Legal reserves | CHF | 290 | ||
| 2940 | Revaluation reserves | CHF | 290 | ||
| 290 | Legal reserves | 28 | |||
| 2950 | Legal reserve from profit | CHF | 295 | ||
| 295 | Legal reserve from profit | 28 | |||
| 2960 | Optional reserves from profit | CHF | 296 | ||
| 296 | Optional reserves from profit | 28 | |||
| 2970 | Profit / Loss carried forward | CHF | 297 | ||
| 29A | Profit / Loss for the year | 297 | |||
| 297 | Profit / Loss from Balance Sheet | 28 | |||
| 2980 | Treasury stock, shares, rights of investment (negative) | CHF | 298 | ||
| 298 | Treasury stock, shares, rights of investment (negative) | 28 | |||
| 28 | Equity | 2 | |||
| 2 | Total liabilities | 00 | |||
| PROFIT & LOSS STATEMENT | |||||
| 3000 | Earnings from own products | CHF | 30 | ||
| 3200 | Earnings from resale | CHF | 30 | ||
| 3400 | Earnings from services rendered | CHF | 30 | ||
| 3600 | Other revenues and services | CHF | 30 | ||
| 3710 | Own consumption | CHF | 30 | ||
| 3800 | Decrease in revenues | CHF | 30 | ||
| 3805 | Losses on accounts receivable, credit variation | CHF | 30 | ||
| 30 | Net revenues from supplies and services | 3 | |||
| 3900 | Change in inventories of in-process products | CHF | 39 | ||
| 3901 | Change in inventories of finished products | CHF | 39 | ||
| 3940 | Non-invoiced services variations | CHF | 39 | ||
| 39 | Change in inventories and Non-invoiced services | 3 | |||
| 3 | Revenues from supplies and services | E1 | |||
| 4000 | Raw materials | CHF | 4 | ||
| 4200 | Expenses for goods for resale | CHF | 4 | ||
| 4400 | Third party expenses | CHF | 4 | ||
| 4500 | Energy consumption for production | CHF | 4 | ||
| 4900 | Reduction of costs | CHF | 4 | ||
| 4 | Costs for material, goods, services and energy | E1 | |||
| E1 | Gross operating result after deducting costs for materials and goods | E2 | |||
| 5000 | Salaries | CHF | 5 | ||
| 5700 | Contribution to old age insurance and unemployment | CHF | 5 | ||
| 5710 | Family equalization fund | CHF | 5 | ||
| 5720 | Contribution to pension funds | CHF | 5 | ||
| 5730 | Contribution to accident insurance | CHF | 5 | ||
| 5740 | Contribution to voluntary daily benefits insurance | CHF | 5 | ||
| 5790 | Source tax | CHF | 5 | ||
| 5800 | Other personnel expenses | CHF | 5 | ||
| 5810 | Training of personnel | CHF | 5 | ||
| 5820 | Travel and entertainment expenses effective | CHF | 5 | ||
| 5830 | Travel and entertainment expense allowance | CHF | 5 | ||
| 5900 | Temporary staff | CHF | 5 | ||
| 5 | Personnel expenses | E2 | |||
| E2 | Gross operating result after deducting personnel expenses | E3 | |||
| 6000 | Rental | CHF | 60 | ||
| 6040 | Cleaning of facilities | CHF | 60 | ||
| 60 | Rental | 6 | |||
| 6100 | Maintenance, repairs and replacement of tangible assets | CHF | 61 | ||
| 6105 | Leasing costs tangible assets | CHF | 61 | ||
| 61 | Maintenance, repairs and replacement of tangible assets | 6 | |||
| 6200 | Repairs | CHF | 62 | ||
| 6210 | Fuel | CHF | 62 | ||
| 6220 | Car insurance | CHF | 62 | ||
| 6260 | Car leasing and rental | CHF | 62 | ||
| 6270 | Car costs - private part | CHF | 62 | ||
| 6282 | Transportation expenses | CHF | 62 | ||
| 62 | Vehicle and transportation expenses | 6 | |||
| 6300 | Insurance for damage of items | CHF | 63 | ||
| 63 | Insurance for damage of items | 6 | |||
| 6402 | Electricity | CHF | 64 | ||
| 6410 | Heating expenses | CHF | 64 | ||
| 6430 | Water | CHF | 64 | ||
| 6460 | Garbage | CHF | 64 | ||
| 64 | Energy and disposal costs | 6 | |||
| 6500 | Office supplies | CHF | 65 | ||
| 6503 | Technical magazines, newspapers, periodicals | CHF | 65 | ||
| 6510 | Telephone / internet | CHF | 65 | ||
| 6511 | Hosting at third-party | CHF | 65 | ||
| 6513 | Postal charges | CHF | 65 | ||
| 6570 | IT charges including leasing | CHF | 65 | ||
| 6580 | Licenses and updates | CHF | 65 | ||
| 6583 | Consumables | CHF | 65 | ||
| 65 | Administrative and IT costs | 6 | |||
| 6600 | Advertising | CHF | 66 | ||
| 6642 | Gifts to customers | CHF | 66 | ||
| 66 | Advertising | 6 | |||
| 6700 | Various costs for the financial year | CHF | 67 | ||
| 67 | Various costs for the financial year | 6 | |||
| 6 | Other operating expenses, depreciation, value adjustments and financial results | E3 | |||
| E3 | Operating result before depreciation and value adjustments, financial results and taxes (EBITDA) | E4 | |||
| 6800 | Depreciation and value adjustments of fixed assets | CHF | 68 | ||
| 68 | Depreciation and value adjustments of fixed assets | E4 | |||
| E4 | Operating result before financial results and taxes (EBIT) | E5 | |||
| 6900 | Costs for bank interest | CHF | 69 | ||
| 6940 | Bank costs | CHF | 69 | ||
| 6949 | Exchange rate loss | CHF | 69 | ||
| 6950 | Financial revenue | CHF | 69 | ||
| 6999 | Exchange rate profit | CHF | 69 | ||
| 69 | Financial costs and revenue | E5 | |||
| E5 | Operating result before taxes (EBT) | E6 | |||
| 7000 | Non-operating revenue | CHF | 7 | ||
| 7010 | Non-operating costs | CHF | 7 | ||
| 7500 | Corporate real estate revenues | CHF | 7 | ||
| 7510 | Corporate real estate costs | CHF | 7 | ||
| 7 | Non-operating items | E6 | |||
| 8000 | Extraneous costs | CHF | 8 | ||
| 8100 | Extraneous revenue | CHF | 8 | ||
| 8500 | Extraordinary, unique costs or costs relating to other accounting periods | CHF | 8 | ||
| 8510 | Extraordinary, unique revenue or revenue relating to other accounting periods | CHF | 8 | ||
| 8 | Results of extraneous, extraordinary or unique character, or for other accounting periods | E6 | |||
| E6 | Profit or loss before taxes | E7 | |||
| 8900 | Direct taxes | CHF | 89 | ||
| 89 | Direct taxes | E7 | |||
| E7 | Annual profit or loss | 29A | |||
| 00 | Difference should be = 0 (blank cell) | ||||
| CLIENTS/DEBTORS | |||||
| 110001 | Company 1 | CHF | DEB1 | ||
| 110002 | Company 2 | CHF | DEB1 | ||
| 110003 | Company 3 | CHF | DEB1 | ||
| DEB1 | Total Clients/Debtors | 110A | |||
| SUPPLIERS/CREDITORS | |||||
| 200001 | Company 1 | CHF | CRE1 | ||
| 200002 | Company 2 | CHF | CRE1 | ||
| 200003 | Company 3 | CHF | CRE1 | ||
| CRE1 | Total suppliers/Creditors | 200A | |||
| COST CENTERS | |||||
| .PAC | Packaging A | CHF | INV | ||
| .RM | Raw materials A | CHF | INV | ||
| .AM | Auxiliairy materials A | CHF | INV | ||
| INV | Total inventories | ||||
| ,MAN1 | Maintenance 1 | CHF | MAN | ||
| ,MAN2 | Maintenance 2 | CHF | MAN | ||
| ,MAN3 | Maintenance 3 | CHF | MAN | ||
| MAN | Total maintenance | ||||
| ;PB1 | Publicity 1 | CHF | PU | ||
| ;PB2 | Publicity 2 | CHF | PU | ||
| PU | Total publicity | ||||
| Ref.Currency | Currency | Text |
|---|---|---|
| CHF | EUR | Euro |
| CHF | USD | US Dollar |
Sole proprietorship | SME | Double-entry multicurrency accounting
In this article
Sole proprietorship | SME | Double-entry multicurrency accounting
Sole proprietorship | SME | Double-entry multicurrency accounting
Template for managing accounts in multiple currencies. In the chart of accounts, in addition to accounts in the base currency, you can set up as many accounts as needed in other currencies, including virtual ones. For each currency, you can define the exchange rate, and every time you record a transaction, the program automatically calculates the equivalent value in the base currency. Exchange rate differences are also handled automatically. You have access to automated checks and controls to avoid exchange rate discrepancies. If you need to present reports and financial statements abroad, you can set up the accounting in a second currency to obtain balances both in the base currency and the secondary one. Open the template from our WebApp or from the program and save the file to your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
The multicurrency model, based on double-entry accounting, allows you to manage accounts in other currencies in addition to the base currency.
Create your file
- Open the template with the Banana Accounting WebApp
- From the menu File > File properties, set the period, your company name and the base currency in any currency you want.
- From the menu File > Save as, save the file. It is useful to include the company name and year in the file name. For example: "Rossi-SA-20xx.ac2".
- In the Exchange rates table, set the foreign currencies always in reference to the base currency and exchange rates. Opening rates are set only the first time you use Banana Accounting. At the beginning of the new year, they will be automatically carried over based on the closing rates entered on 31.12.
WARNING: if you close the browser without saving, you will lose the entered data. Always save the file to your computer.
To reopen the saved file, click on File > Open.
In our Documentation you will find all the insights and topics for multicurrency accounting, including:
Sole proprietorship | SME | Simplified plan | Double-Entry Multi-Currency Accounting
In this article
Sole proprietorship | SME | Simplified plan | Double-Entry Multi-Currency Accounting
Sole proprietorship | SME | Simplified plan | Double-Entry Multi-Currency Accounting
Ideal model for a sole proprietorship with accounts in multiple currencies in addition to the base currency. This file is designed for businesses that use currencies other than their base currency. It includes dedicated columns and an Exchange Rates table where you can set the exchange rate freely. Each time you record a transaction, the program automatically calculates the equivalent value in the base currency. Exchange rate differences are also calculated automatically. You can set up a second currency to present reports and balance sheets abroad, with balances available in both the base currency and the secondary currency. Open the model from our WebApp or directly from the program, and save the file on your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
The multi-currency model based on double-entry accounting, this model allows you to manage accounts in foreign currencies as well as the base currency.
Create your File
- Open the template using the Banana Accounting Plus WebApp.
Use the command File > File Properties to set the period, your company name, and the base currency (you can manage your budget and accounting in any currency).
Use the command File > Save As to save the file. It's helpful to include the company name and year in the file name, e.g., "Rossi-SA-20xx.ac2". - In the Exchange Rates Table, set the foreign currencies always in reference to the base currency and their exchange rates. Opening exchange rates are only set the first time you use Banana Accounting. When transitioning to a new year, these rates will be automatically carried over based on the closing rates entered as of 31.12.
ATTENTION: If you close the browser without saving, the data you entered will be lost. Always save the file on your computer.
To reopen the saved file, click File > Open.
In our Documentation, you will find detailed explanations and topics related to multi-currency accounting, including:
Template preview
Company XX
Accounting 2025
Basic Currency: CHF
Double-entry with foreign currencies
| Group | Account | Description | Currency | Sum In | Gr1 |
|---|---|---|---|---|---|
| BALANCE SHEET | |||||
| ASSETS | |||||
| 1000 | Cash on hand | CHF | 10 | ||
| 1010 | Post office current account | CHF | 10 | ||
| 1020 | Bank account | CHF | 10 | ||
| 1024 | Bank account EUR | EUR | 10 | ||
| 1025 | Bank account USD | USD | 10 | ||
| 1045 | Credit cards / Debit cards | CHF | 10 | ||
| 1090 | Internal transfers | CHF | 10 | ||
| 1091 | Transfer account for salaries | CHF | 10 | ||
| 1099 | Amounts to be clarified | CHF | 10 | ||
| 1100 | Due from clients or debtors | CHF | 10 | ||
| 1176 | Withholding tax | CHF | 10 | ||
| 1191 | Deposits | CHF | 10 | ||
| 1300 | Accrued income and prepaid expenses | CHF | 10 | ||
| 10 | Current assets | 1 | |||
| 1500 | Machinery | CHF | 14 | ||
| 1510 | Office equipment | CHF | 14 | ||
| 1512 | Store fixtures | CHF | 14 | ||
| 1520 | Office machines, information and communication technology | CHF | 14 | ||
| 1530 | Vehicles | CHF | 14 | ||
| 1540 | Tools and equipment | CHF | 14 | ||
| 14 | Fixed assets | 1 | |||
| 1 | TOTAL ASSETS | 00 | 1 | ||
| LIABILITIES | |||||
| 2000 | Accounts payable | CHF | 20 | ||
| 2100 | Short-term interest-bearing debts | CHF | 20 | ||
| 2300 | Accruals and deferred income | CHF | 20 | ||
| 20 | Short-term third party capital | 2 | |||
| 2400 | Due to banks | CHF | 24 | ||
| 2500 | Other long-term debts | CHF | 24 | ||
| 2600 | Provisions | CHF | 24 | ||
| 24 | Long-term third party capital | 2 | |||
| 2800 | Share capital | CHF | 28 | ||
| 2850 | Private account | CHF | 28 | ||
| 2970 | Profit or loss carried forward | CHF | 28 | ||
| 2891 | Annual profit or loss | CHF | 28 | 1 | |
| 28 | Equity | 2 | |||
| 2 | TOTAL LIALIBILITIES | 00 | 1 | ||
| PROFIT & LOSS STATEMENT | |||||
| REVENUES | |||||
| 3000 | Gross revenues from manufactured products | CHF | 3 | ||
| 3200 | Gross revenues from resale of goods | CHF | 3 | ||
| 3400 | Gross revenues from provided services | CHF | 3 | ||
| 3600 | Other revenues | CHF | 3 | ||
| 3710 | Own consumption | CHF | 3 | ||
| 3800 | Discounts | CHF | 3 | ||
| 3810 | Credit/debit card fees | CHF | 3 | ||
| 3 | TOTAL REVENUES | 02 | 1 | ||
| EXPENSES | |||||
| 4000 | Purchases | CHF | 4 | ||
| 4 | Purchases | 4-6 | |||
| 5600 | Salaries (administration) | CHF | 5 | ||
| 5701 | AHV, IV, EO holder | CHF | 5 | ||
| 5710 | Family allowances | CHF | 5 | ||
| 5720 | Contribution to pension funds | CHF | 5 | ||
| 5730 | Contribution to accident insurance | CHF | 5 | ||
| 5740 | Contribution to voluntary daily benefits insurance | CHF | 5 | ||
| 5790 | Source tax | CHF | 5 | ||
| 5820 | Travel expenses | CHF | 5 | ||
| 5830 | Management flat-rate expenses | CHF | 5 | ||
| 5880 | Other personal expenses | CHF | 5 | ||
| 5900 | Temporary staff | CHF | 5 | ||
| 5 | Personnel expenses | 4-6 | 1 | ||
| Financial charges and revenue | |||||
| 6000 | Rental | CHF | 6 | ||
| 6030 | Incidental rent costs | CHF | 6 | ||
| 6100 | Maintenance, repairs and replacement of tangible assets | CHF | 6 | ||
| 6200 | Repairs | CHF | 6 | ||
| 6210 | Fuel | CHF | 6 | ||
| 6220 | Car insurance | CHF | 6 | ||
| 6260 | Car leasing and rental | CHF | 6 | ||
| 6280 | Transport expenses | CHF | 6 | ||
| 6300 | Insurance for damage of items | CHF | 6 | ||
| 6400 | Energy and disposal costs | CHF | 6 | ||
| 6500 | Office equipment | CHF | 6 | ||
| 6503 | Technical magazines, newspapers, periodicals | CHF | 6 | ||
| 6510 | Phone / internet | CHF | 6 | ||
| 6513 | Postages | CHF | 6 | ||
| 6520 | Contributions | CHF | 6 | ||
| 6521 | Donations, grants | CHF | 6 | ||
| 6530 | Book-keeping fees | CHF | 6 | ||
| 6570 | IT costs including leasing | CHF | 6 | ||
| 6574 | Small investments | CHF | 6 | ||
| 6580 | Licenses and updates | CHF | 6 | ||
| 6583 | Consumables | CHF | 6 | ||
| 6600 | Advertising expenses | CHF | 6 | ||
| 6641 | Customer support | CHF | 6 | ||
| 6800 | Depreciation and value adjustments of fixed assets | CHF | 6 | ||
| 6900 | Costs for bank interests | CHF | 6 | ||
| 6940 | Bank charges | CHF | 6 | ||
| 6949 | Exchange rate loss | CHF | 6 | ||
| 6950 | Financial revenues | CHF | 6 | ||
| 6999 | Exchange rate profit | CHF | 6 | ||
| 8900 | Direct taxes | CHF | 6 | ||
| 6 | Other operating expenses | 4-6 | 1 | ||
| 4-6 | TOTAL EXPENSES | 02 | |||
| 02 | Annual profit (-) or loss (+) | 2891 | 1 | ||
| 00 | Difference should be = 0 (blank cell) | ||||
| COST CENTERS | |||||
| .PAC | Packaging A | CHF | INV | ||
| .RAW | Raw materials A | CHF | INV | ||
| .AUX | Auxiliary material A | CHF | INV | ||
| INV | Total inventories | ||||
| ,MAN1 | Maintenance 1 | CHF | MAN | ||
| ,MAN2 | Maintenance 2 | CHF | MAN | ||
| ,MAN3 | Maintenance 3 | CHF | MAN | ||
| MAN | Total maintenance | ||||
| ;PB1 | Publicity 1 | CHF | PU | ||
| ;PB2 | Publicity 2 | CHF | PU | ||
| PU | Total publicity | ||||
| Ref.Currency | Currency | Text |
|---|---|---|
| CHF | EUR | Euro |
| CHF | USD | US Dollar |
General partnerships, SME | Double-entry accounting with Multi-currency
In this article
General partnerships, SME | Double-entry accounting with Multi-currency
General partnerships, SME | Double-entry accounting with Multi-currency
Ideal template for accounting of partnerships with foreign currencies. In the chart of accounts, you can set up an unlimited number of foreign currency accounts, and in the Exchange Rates table, you can freely enter the exchange rates. All calculations for conversion into the base currency and exchange rate differences are automated. Open the model from our WebApp or from the program and save the file on your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
Ideal model for partnership accounting. It includes all the settings and functions needed to:
- Create and print invoices with the Swiss QR code.
- Import data from bank statements.
- Set up Rules to store and automate the completion of transactions imported from bank statements.
- Manage cost centers, customizable according to your needs to track specific details of certain accounts.
- Create budgets and financial forecasts.
- Print all the reports you need: Balance Sheets, Journal, Account Ledgers, VAT Reports, Open Invoices, and much more.
Some functions require a subscription to the Advanced plan of Banana Accounting Plus, such as using the new Rules, Temporary Filter, and Sort Rows features.
Create your File
- Open the template using the Banana Accounting Plus WebApp.
Use the command File > File Properties to set the period, your company name, and the base currency (you can manage your budget and accounting in any currency).
Use the command File > Save As to save the file. It's helpful to include the company name and year in the file name, e.g., "Rossi-SA-20xx.ac2". - In the Exchange Rates Table, set the foreign currencies always in reference to the base currency and their exchange rates. Opening exchange rates are only set the first time you use Banana Accounting. When transitioning to a new year, these rates will be automatically carried over based on the closing rates entered as of 31.12.
ATTENTION: If you close the browser without saving, the data you entered will be lost. Always save the file on your computer.
To reopen the saved file, click File > Open.
In our Documentation, you will find detailed explanations and topics related to multi-currency accounting, including:
Template preview
Company XXX
Accounting 2024
Basic Currency: CHF
Double-entry with foreign currencies
| Group | Account | Description | Currency | Sum In | Gr1 |
|---|---|---|---|---|---|
| BALANCE SHEET | |||||
| ASSETS | |||||
| 1000 | Cash on hand | CHF | 100 | ||
| 1020 | Bank account | CHF | 100 | ||
| 1024 | Bank account Euro | EUR | 100 | ||
| 1025 | Bank account USD | USD | 100 | ||
| 100 | Cash and cash equivalents | 10 | 1 | ||
| 1060 | Bonds and stocks | CHF | 106 | ||
| 106 | Short-term Assets listed in Stock Exchange | 10 | |||
| 1090 | Internal transfers | CHF | 109 | ||
| 1091 | Transfer account for salaries | CHF | 109 | ||
| 1099 | Amounts to be clarified | CHF | 109 | ||
| 109 | Transfer accounts | 10 | |||
| 1100 | Due from Clients or Debtors | CHF | 110 | ||
| 1109 | Provision for Doubtful Debts | CHF | 110 | ||
| 110 | Accounts receivable | 10 | |||
| 1140 | Advances and loans | CHF | 114 | ||
| 1176 | Withholding tax | CHF | 114 | ||
| 1180 | Receivables from social insurances and social security institutions | CHF | 114 | ||
| 1188 | Source tax | CHF | 114 | ||
| 1190 | Various short-term receivables | CHF | 114 | ||
| 1191 | Securities | CHF | 114 | ||
| 114 | Other short-term receivables | 10 | |||
| 1200 | Goods for resale | CHF | 120 | ||
| 1210 | Raw materials | CHF | 120 | ||
| 1220 | Auxiliary material | CHF | 120 | ||
| 1230 | Consumables | CHF | 120 | ||
| 1260 | Finished products | CHF | 120 | ||
| 1270 | In-process products | CHF | 120 | ||
| 1280 | Non-invoiced services | CHF | 120 | ||
| 120 | Inventories | 10 | 1 | ||
| 1300 | Prepaid expenses | CHF | 130 | ||
| 1301 | Accrued income | CHF | 130 | ||
| 130 | Prepaid Expenses | 10 | 1 | ||
| 10 | Current assets | 1 | 1 | ||
| 1400 | Bonds and stocks | CHF | 140 | ||
| 1440 | Loans | CHF | 140 | ||
| 1460 | Loan to partner A | CHF | 140 | ||
| 140 | Financial assets | 14 | |||
| 1480 | Investments | CHF | 148 | ||
| 148 | Investments | 14 | |||
| 1500 | Machinery | CHF | 150 | ||
| 1510 | Office furniture and equipment | CHF | 150 | ||
| 1520 | Office machinery, information and communication technology | CHF | 150 | ||
| 1530 | Motor vehicles | CHF | 150 | ||
| 1540 | Tools and equipment | CHF | 150 | ||
| 150 | Tangible assets | 14 | |||
| 1600 | Commercial buildings | CHF | 160 | ||
| 160 | Tangible fixed asset management | 14 | |||
| 1700 | Patents, know-how, licences, rights and development | CHF | 170 | ||
| 1710 | Brands | CHF | 170 | ||
| 1712 | Models | CHF | 170 | ||
| 1770 | Goodwill | CHF | 170 | ||
| 170 | Intangible fixed assets | 14 | |||
| 1850 | Share capital, rights not paid or non-paid Foundation capital | CHF | 180 | ||
| 180 | Capital or non-paid Foundation capital | 14 | |||
| 14 | Fixed Assets | 1 | |||
| 1 | Total Assets | 00 | |||
| LIABILITIES | |||||
| 2000 | Suppliers or creditors | CHF | 200 | ||
| 2030 | Deposits received | CHF | 200 | ||
| 200 | Suppliers or creditors | 20 | 1 | ||
| 2100 | Due to banks short/term | CHF | 210 | ||
| 2120 | Financial leasing commitments | CHF | 210 | ||
| 2140 | Other onerous debts | CHF | 210 | ||
| 210 | Short-term onorous debts | 20 | |||
| 2206 | Withholding tax | CHF | 220 | ||
| 2208 | Direct taxes | CHF | 220 | ||
| 2210 | Other short-term debts | CHF | 220 | ||
| 2260 | Due to partner A | CHF | 220 | ||
| 2270 | Social insurances and social security institutions | CHF | 220 | ||
| 2279 | Source tax | CHF | 220 | ||
| 220 | Other short-term debts | 20 | |||
| 2300 | Accrued expenses | CHF | 230 | ||
| 2301 | Next year's revenues collected | CHF | 230 | ||
| 2330 | Short-term provisions | CHF | 230 | ||
| 230 | Accruals and deferred income | 20 | |||
| 20 | Short-term third party capital | 2A | |||
| 2400 | Due to banks | CHF | 240 | ||
| 2420 | Financial leasing commitments | CHF | 240 | ||
| 2430 | Debenture loans | CHF | 240 | ||
| 2450 | Loans | CHF | 240 | ||
| 2451 | Mortgage | CHF | 240 | ||
| 240 | Long-term onorous debts | 24 | |||
| 2500 | Other long-term debts (non-onorous) | CHF | 250 | ||
| 250 | Other long-term debts | 24 | |||
| 2600 | Provisions | CHF | 260 | ||
| 260 | Provisions and similar statutory posts | 24 | |||
| 24 | Long-term third party capital | 2A | |||
| 2A | Third party capital | 2 | |||
| 2800 | Equity partner A at the beginning of the year | CHF | 28 | ||
| 2810 | Contributions to equity/equity withdrawals partner A | CHF | 28 | ||
| 2820 | Private account partner A | CHF | 28 | ||
| 2831 | Profit / Loss for the year partner A | CHF | 28 | ||
| 2850 | Equity sponsor A at the beginning of the year | CHF | 28 | ||
| 2860 | Contributions to equity/equity withdrawals sponsor A | CHF | 28 | ||
| 2870 | Private account sponsor A | CHF | 28 | ||
| 2881 | Profit / Loss for the year sponsor A | CHF | 28 | ||
| 297 | Profit/loss for the period | 28 | |||
| 28 | Equity | 2 | |||
| 2 | Total liabilities | 00 | 1 | ||
| PROFIT & LOSS STATEMENT | |||||
| 3000 | Earnings from own products | CHF | 30 | ||
| 3200 | Earnings from resale | CHF | 30 | ||
| 3400 | Earnings from services rendered | CHF | 30 | ||
| 3600 | Other revenues and services | CHF | 30 | ||
| 3710 | Own consumption | CHF | 30 | ||
| 3800 | Decrease in revenues | CHF | 30 | ||
| 3805 | Losses on accounts receivable, credit variation | CHF | 30 | ||
| 30 | Net revenues from supplies and services | 3 | |||
| 3900 | Change in inventories of in-process products | CHF | 39 | ||
| 3901 | Change in inventories of finished products | CHF | 39 | ||
| 3940 | Non-invoiced services variations | CHF | 39 | ||
| 39 | Change in inventories and Non-invoiced services | 3 | |||
| 3 | Revenues from supplies and services | E1 | |||
| 4000 | Raw materials | CHF | 4 | ||
| 4200 | Expenses for goods for resale | CHF | 4 | ||
| 4400 | Third party expenses | CHF | 4 | ||
| 4500 | Energy consumption for production | CHF | 4 | ||
| 4900 | Reduction of costs | CHF | 4 | ||
| 4 | Costs for material, goods, services and energy | E1 | |||
| E1 | Gross operating result after deducting costs for materials and goods | E2 | |||
| 5000 | Salaries | CHF | 5 | ||
| 5700 | Contribution to old age insurance and unemployment | CHF | 5 | ||
| 5710 | Family equalization fund | CHF | 5 | ||
| 5720 | Contribution to pension funds | CHF | 5 | ||
| 5730 | Contribution to accident insurance | CHF | 5 | ||
| 5740 | Contribution to voluntary daily benefits insurance | CHF | 5 | ||
| 5790 | Source tax | CHF | 5 | ||
| 5800 | Other personnel expenses | CHF | 5 | ||
| 5810 | Training of personnel | CHF | 5 | ||
| 5820 | Travel and entertainment expenses effective | CHF | 5 | ||
| 5830 | Travel and entertainment expense allowance | CHF | 5 | ||
| 5900 | Temporary staff | CHF | 5 | ||
| 5 | Personnel expenses | E2 | |||
| E2 | Gross operating result after deducting personnel expenses | E3 | |||
| 6000 | Rental | CHF | 60 | ||
| 6040 | Cleaning of facilities | CHF | 60 | ||
| 60 | Rental | 6 | |||
| 6100 | Maintenance, repairs and replacement of tangible assets | CHF | 61 | ||
| 6105 | Leasing costs tangible assets | CHF | 61 | ||
| 61 | Maintenance, repairs and replacement of tangible assets | 6 | |||
| 6200 | Repairs | CHF | 62 | ||
| 6210 | Fuel | CHF | 62 | ||
| 6220 | Car insurance | CHF | 62 | ||
| 6260 | Car leasing and rental | CHF | 62 | ||
| 6270 | Car costs - private part | CHF | 62 | ||
| 6282 | Transportation expenses | CHF | 62 | ||
| 62 | Vehicle and transportation expenses | 6 | |||
| 6300 | Insurance for damage of items | CHF | 63 | ||
| 63 | Insurance for damage of items | 6 | |||
| 6402 | Electricity | CHF | 64 | ||
| 6410 | Heating expenses | CHF | 64 | ||
| 6430 | Water | CHF | 64 | ||
| 6460 | Garbage | CHF | 64 | ||
| 64 | Energy and disposal costs | 6 | |||
| 6500 | Office supplies | CHF | 65 | ||
| 6503 | Technical magazines, newspapers, periodicals | CHF | 65 | ||
| 6510 | Telephone / internet | CHF | 65 | ||
| 6511 | Hosting at third-party | CHF | 65 | ||
| 6513 | Postal charges | CHF | 65 | ||
| 6570 | IT charges including leasing | CHF | 65 | ||
| 6580 | Licenses and updates | CHF | 65 | ||
| 6583 | Consumables | CHF | 65 | ||
| 65 | Administrative and IT costs | 6 | |||
| 6600 | Advertising | CHF | 66 | ||
| 6642 | Gifts to customers | CHF | 66 | ||
| 66 | Advertising | 6 | |||
| 6700 | Various costs for the financial year | CHF | 67 | ||
| 67 | Various costs for the financial year | 6 | |||
| 6 | Other operating expenses, depreciation, value adjustments and financial results | E3 | |||
| E3 | Operating result before depreciation and value adjustments, financial results and taxes (EBITDA) | E4 | |||
| 6800 | Depreciation and value adjustments of fixed assets | CHF | 68 | ||
| 68 | Depreciation and value adjustments of fixed assets | E4 | |||
| E4 | Operating result before financial results and taxes (EBIT) | E5 | |||
| 6900 | Costs for bank interest | CHF | 69 | ||
| 6940 | Bank costs | CHF | 69 | ||
| 6949 | Exchange rate loss | CHF | 69 | ||
| 6950 | Financial revenue | CHF | 69 | ||
| 6999 | Exchange rate profit | CHF | 69 | ||
| 69 | Financial costs and revenue | E5 | |||
| E5 | Operating result before taxes (EBT) | E6 | |||
| 7000 | Non-operating revenue | CHF | 7 | ||
| 7010 | Non-operating costs | CHF | 7 | ||
| 7500 | Corporate real estate revenues | CHF | 7 | ||
| 7510 | Corporate real estate costs | CHF | 7 | ||
| 7 | Non-operating items | E6 | |||
| 8000 | Extraneous costs | CHF | 8 | ||
| 8100 | Extraneous revenue | CHF | 8 | ||
| 8500 | Extraordinary, unique costs or costs relating to other accounting periods | CHF | 8 | ||
| 8510 | Extraordinary, unique revenue or revenue relating to other accounting periods | CHF | 8 | ||
| 8 | Results of extraneous, extraordinary or unique character, or for other accounting periods | E6 | |||
| E6 | Profit or loss before taxes | E7 | |||
| 8900 | Direct taxes | CHF | 89 | ||
| 89 | Direct taxes | E7 | |||
| E7 | Annual profit or loss | 297 | |||
| 00 | Difference should be = 0 (blank cell) | ||||
| 1 | |||||
| COST CENTERS | |||||
| .PAC | Packaging A | CHF | INV | ||
| .RM | Raw materials A | CHF | INV | ||
| .AM | Auxiliairy materials A | CHF | INV | ||
| INV | Total inventories | ||||
| ,MAN1 | Maintenance 1 | CHF | MAN | ||
| ,MAN2 | Maintenance 2 | CHF | MAN | ||
| ,MAN3 | Maintenance 3 | CHF | MAN | ||
| MAN | Total maintenance | ||||
| ;PB1 | Publicity 1 | CHF | PU | ||
| ;PB2 | Publicity 2 | CHF | PU | ||
| PU | Total publicity | ||||
| Ref.Currency | Currency | Text |
|---|---|---|
| CHF | EUR | Euro |
| CHF | USD | US Dollar |
Tutorial Financial Planning for Accounting Experts
In this article
Tutorial Financial Planning for Accounting Experts
Tutorial Financial Planning for Accounting Experts
Practical guide to precision financial planning for accounting experts. Step-by-step explanations on how to prepare financial planning with the same accuracy and rigor used when recording actual accounting transactions.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebApp Open tutorial in WebAppTemplate documentation
The precision financial planning is a method to build the company’s financial future with the same rigor as real accounting.
In Banana Accounting, forecasting is not separate, but integrated into the same accounting file.
In this tutorial, you will see how to create a complete forecast by entering future transactions and automatically obtaining forecast balance sheet, profit and loss statement, and cash flow. You can also simulate different scenarios.
Introduction video
To see the system in action, watch our video below:
Who this tutorial is for
This tutorial is designed for:
- Accounting experts
- Fiduciary companies
- Consultants and accountants
The goal is to show you how to quickly create a complete financial plan in the same accounting file, including:
- Forecast profit and loss statement
- Forecast balance sheet
- Cash flow evolution
- Comparison between budget and actual results.
You can prepare the financial plan both for your company and for your clients, offering added value to your consulting services that goes beyond accounting management.
Planning structure
With Banana Accounting, you do not need to create anything new. This means you work with:
- the same chart of accounts
- the same Debit/Credit logic
- the same analysis tools
To enter budget transactions, use:
- the Budget table where you enter the transactions you expect during the year:
- enter the transaction only once
- define the frequency
- you can determine that a transaction appears within a period defined by a start and end date.
Chart of Accounts
The accounts you use are those already available in the chart of accounts. In the Accounts table, you can display the Budget column to always have forecast balances available:
- menu Data > Columns setup > enable Budget column
Assets and Liabilities (Balance Sheet)
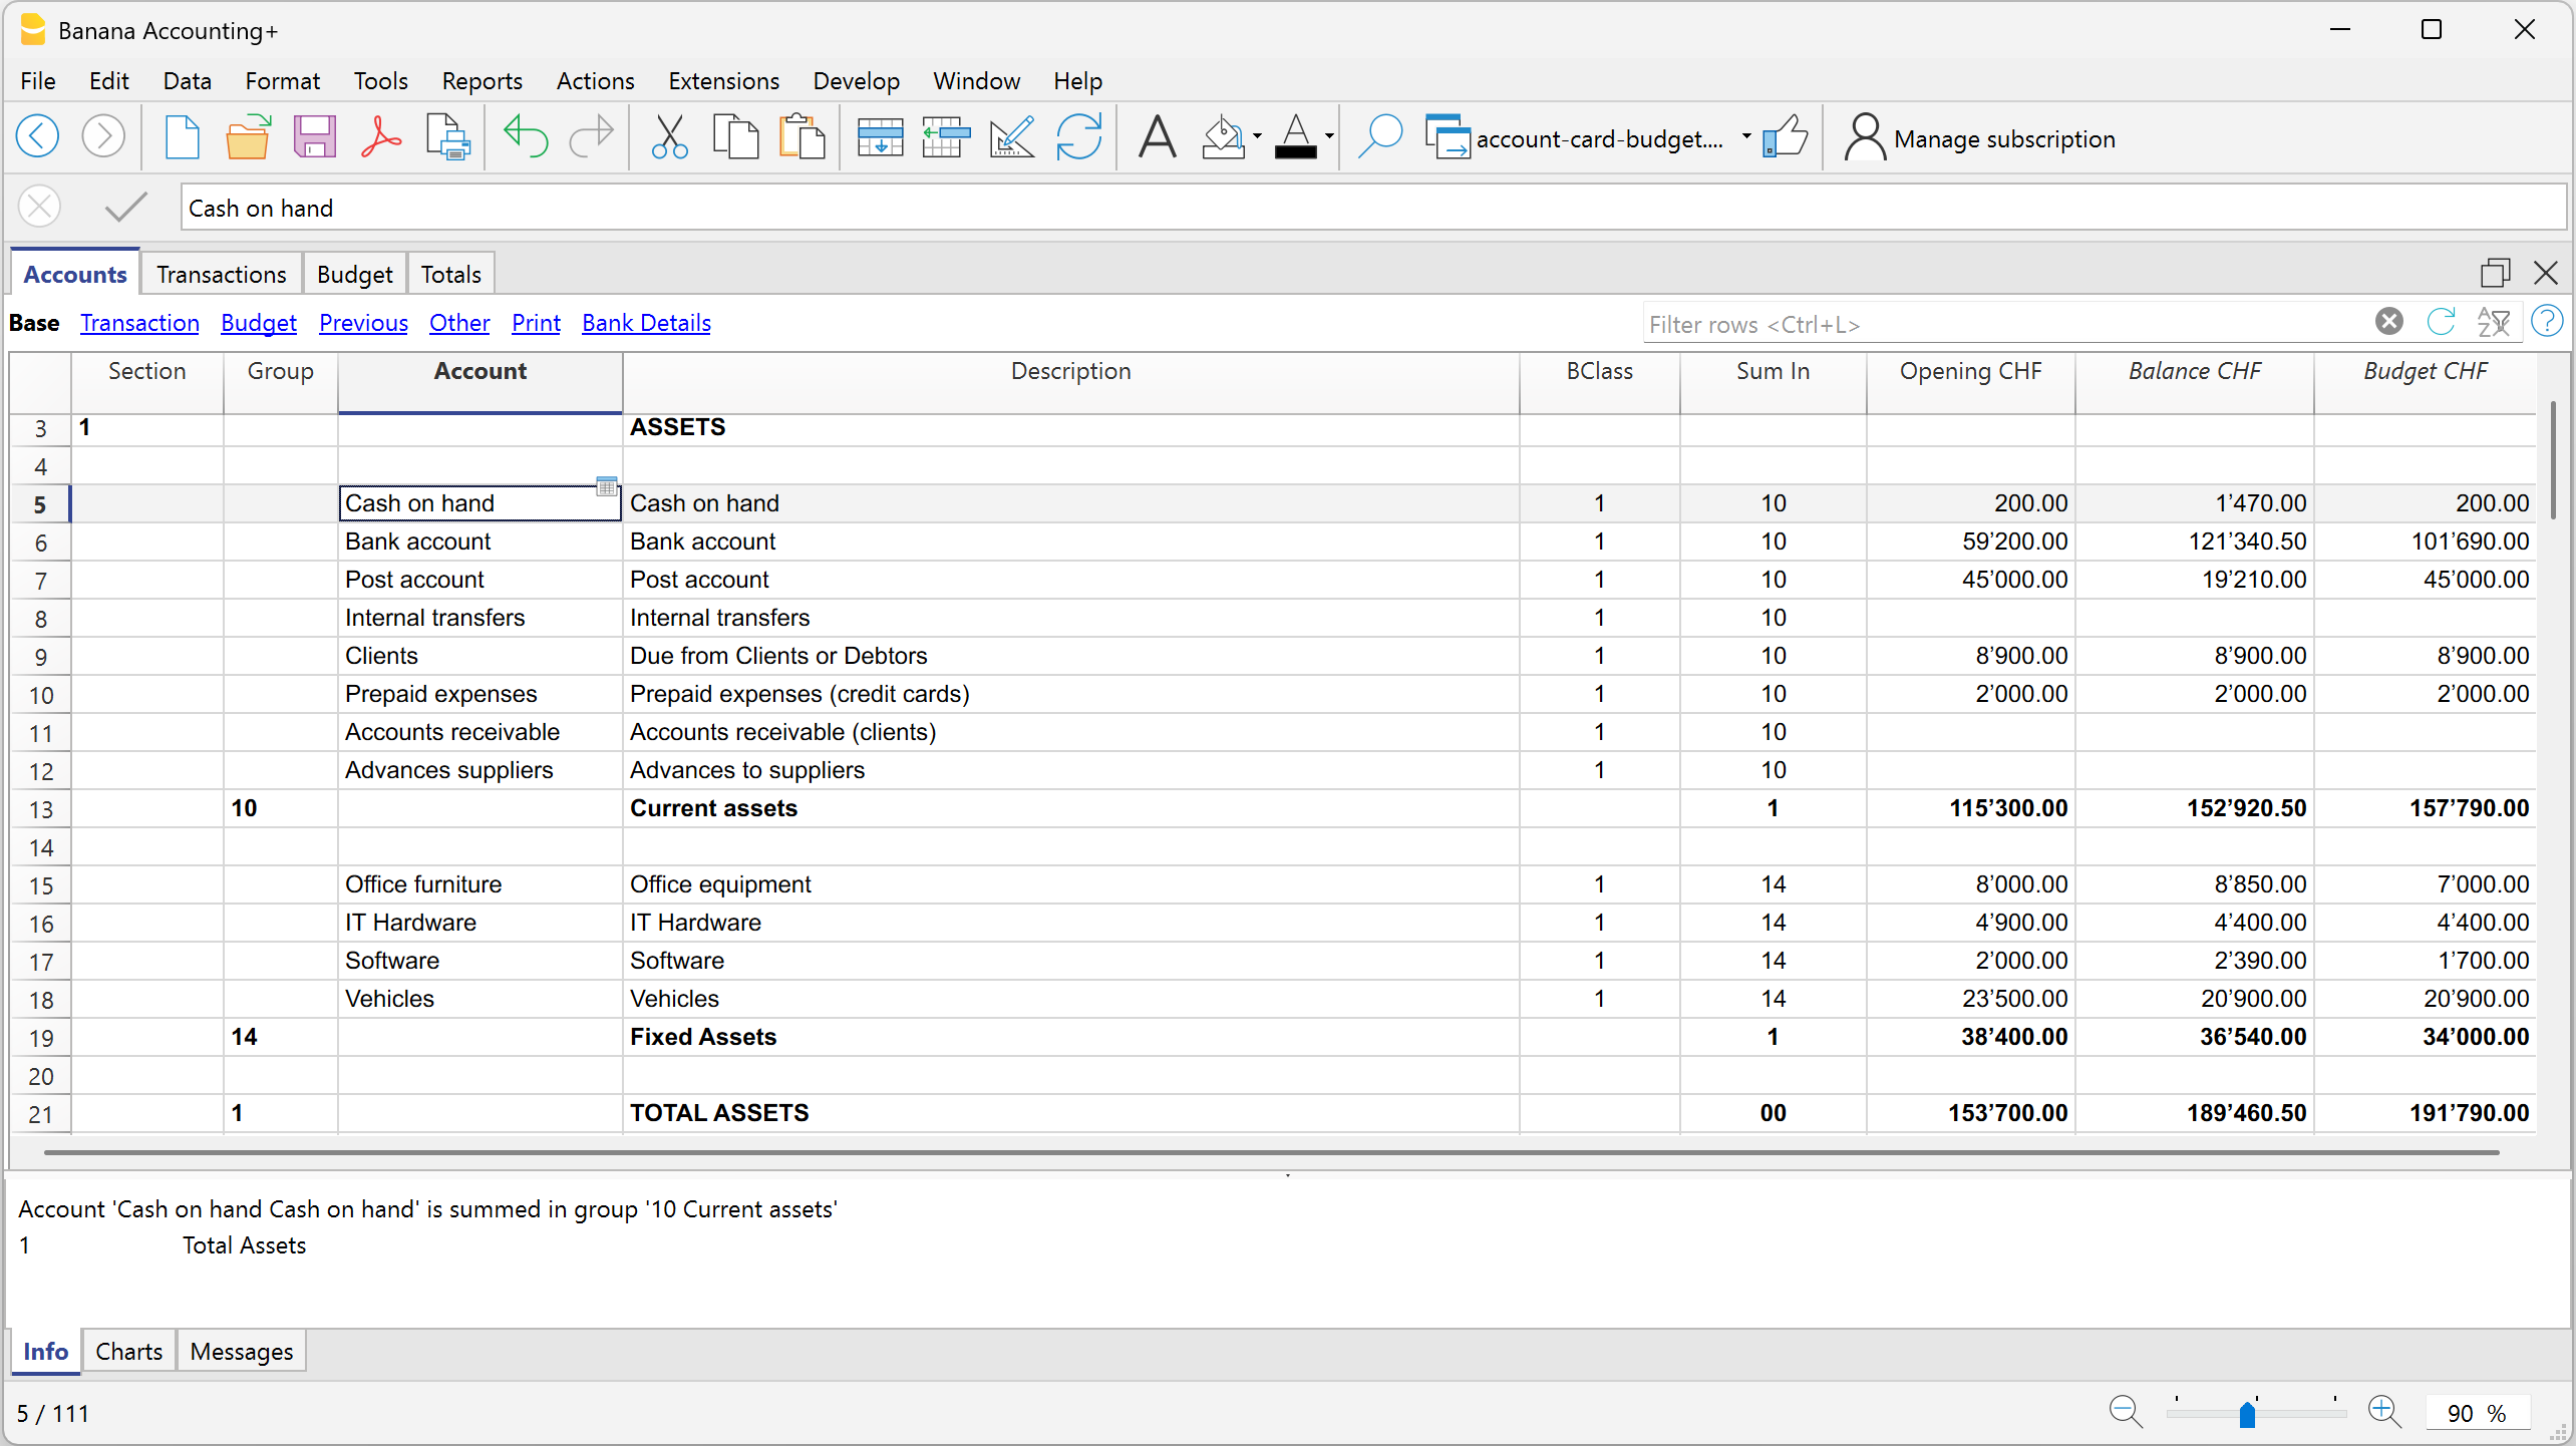
- Costs and Revenue (Profit and Loss Statement)
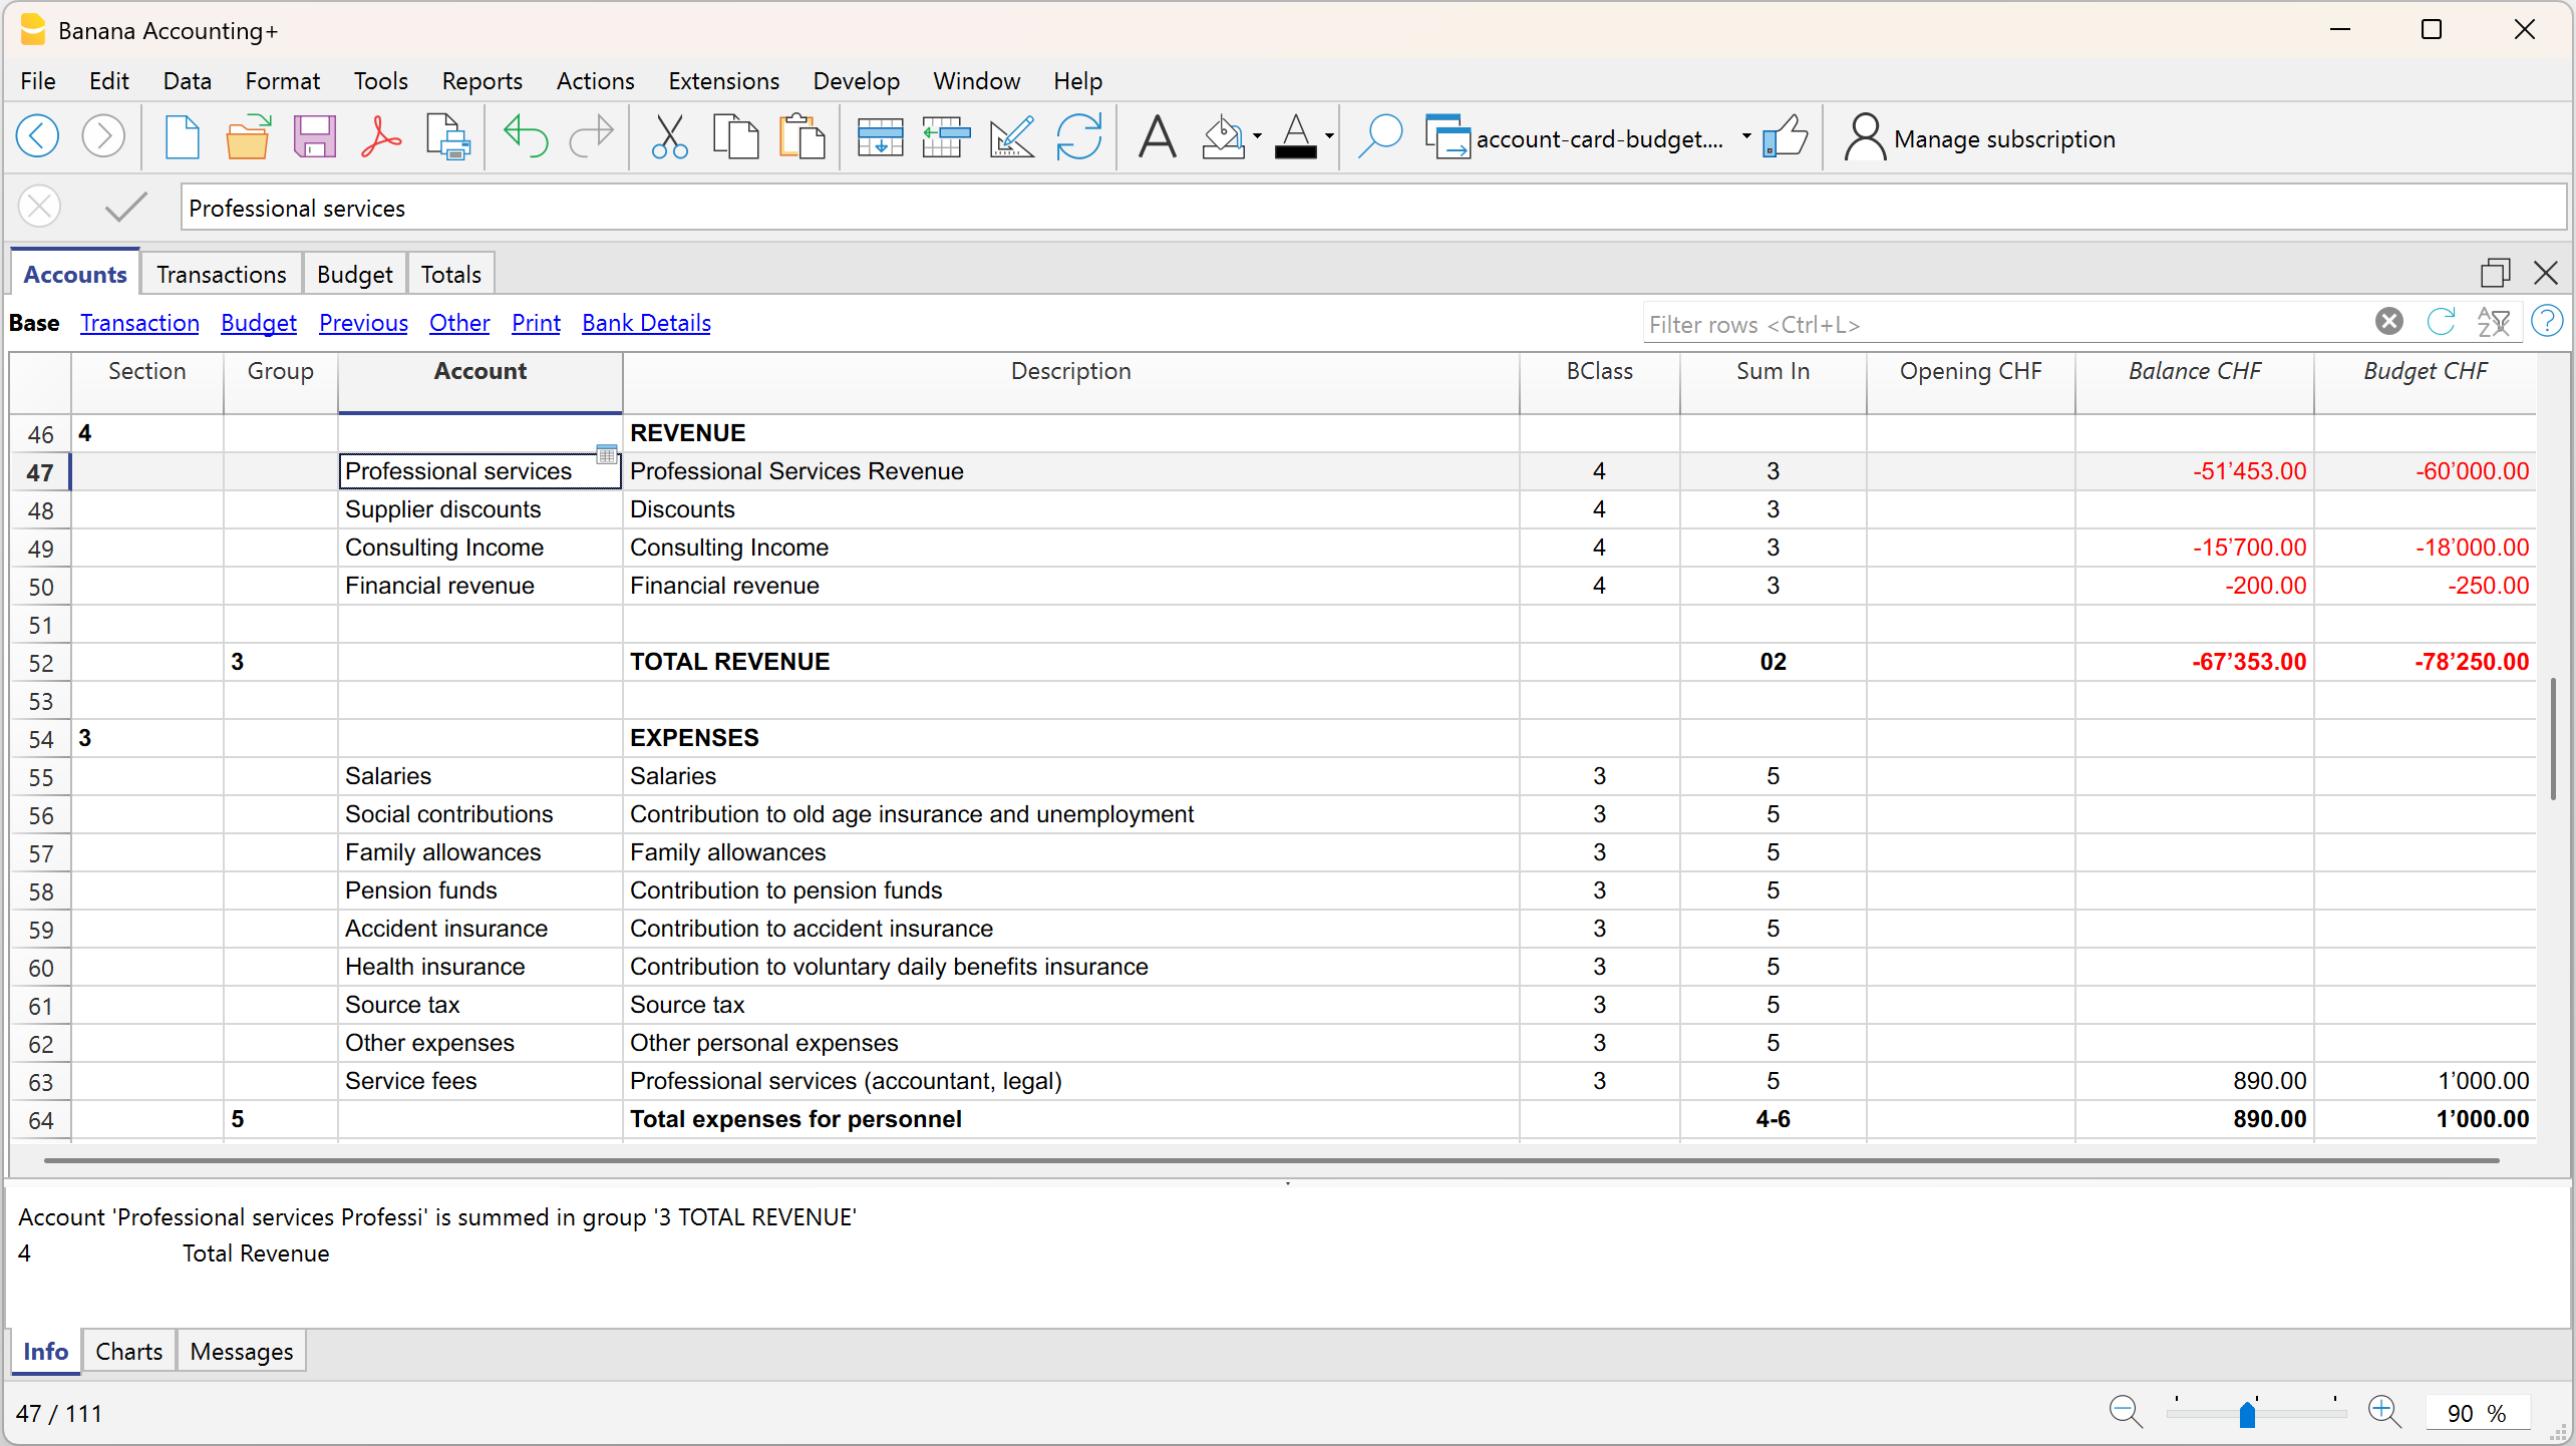
For a more detailed forecast, if not already present, we recommend setting up and using:
Budget Table
The Budget table is the core of the forecasting system, where you enter the transactions you expect during the year or within a defined period.
For each future event, enter the data in the following columns:
- Start date: the date when the transaction begins
- End date: the last date by which the transaction ends (a date one or more years later can also be specified).
If the transaction will always repeat every year, you do not need to enter any date. - Repeat: repetition frequency (day, month, quarter, half-year, year)
- Description: description of the transaction
- Debit / Credit account: accounts available and taken from the chart of accounts
- Amount: transaction amount
If needed, you can also enter VAT code, segments, or cost centers.
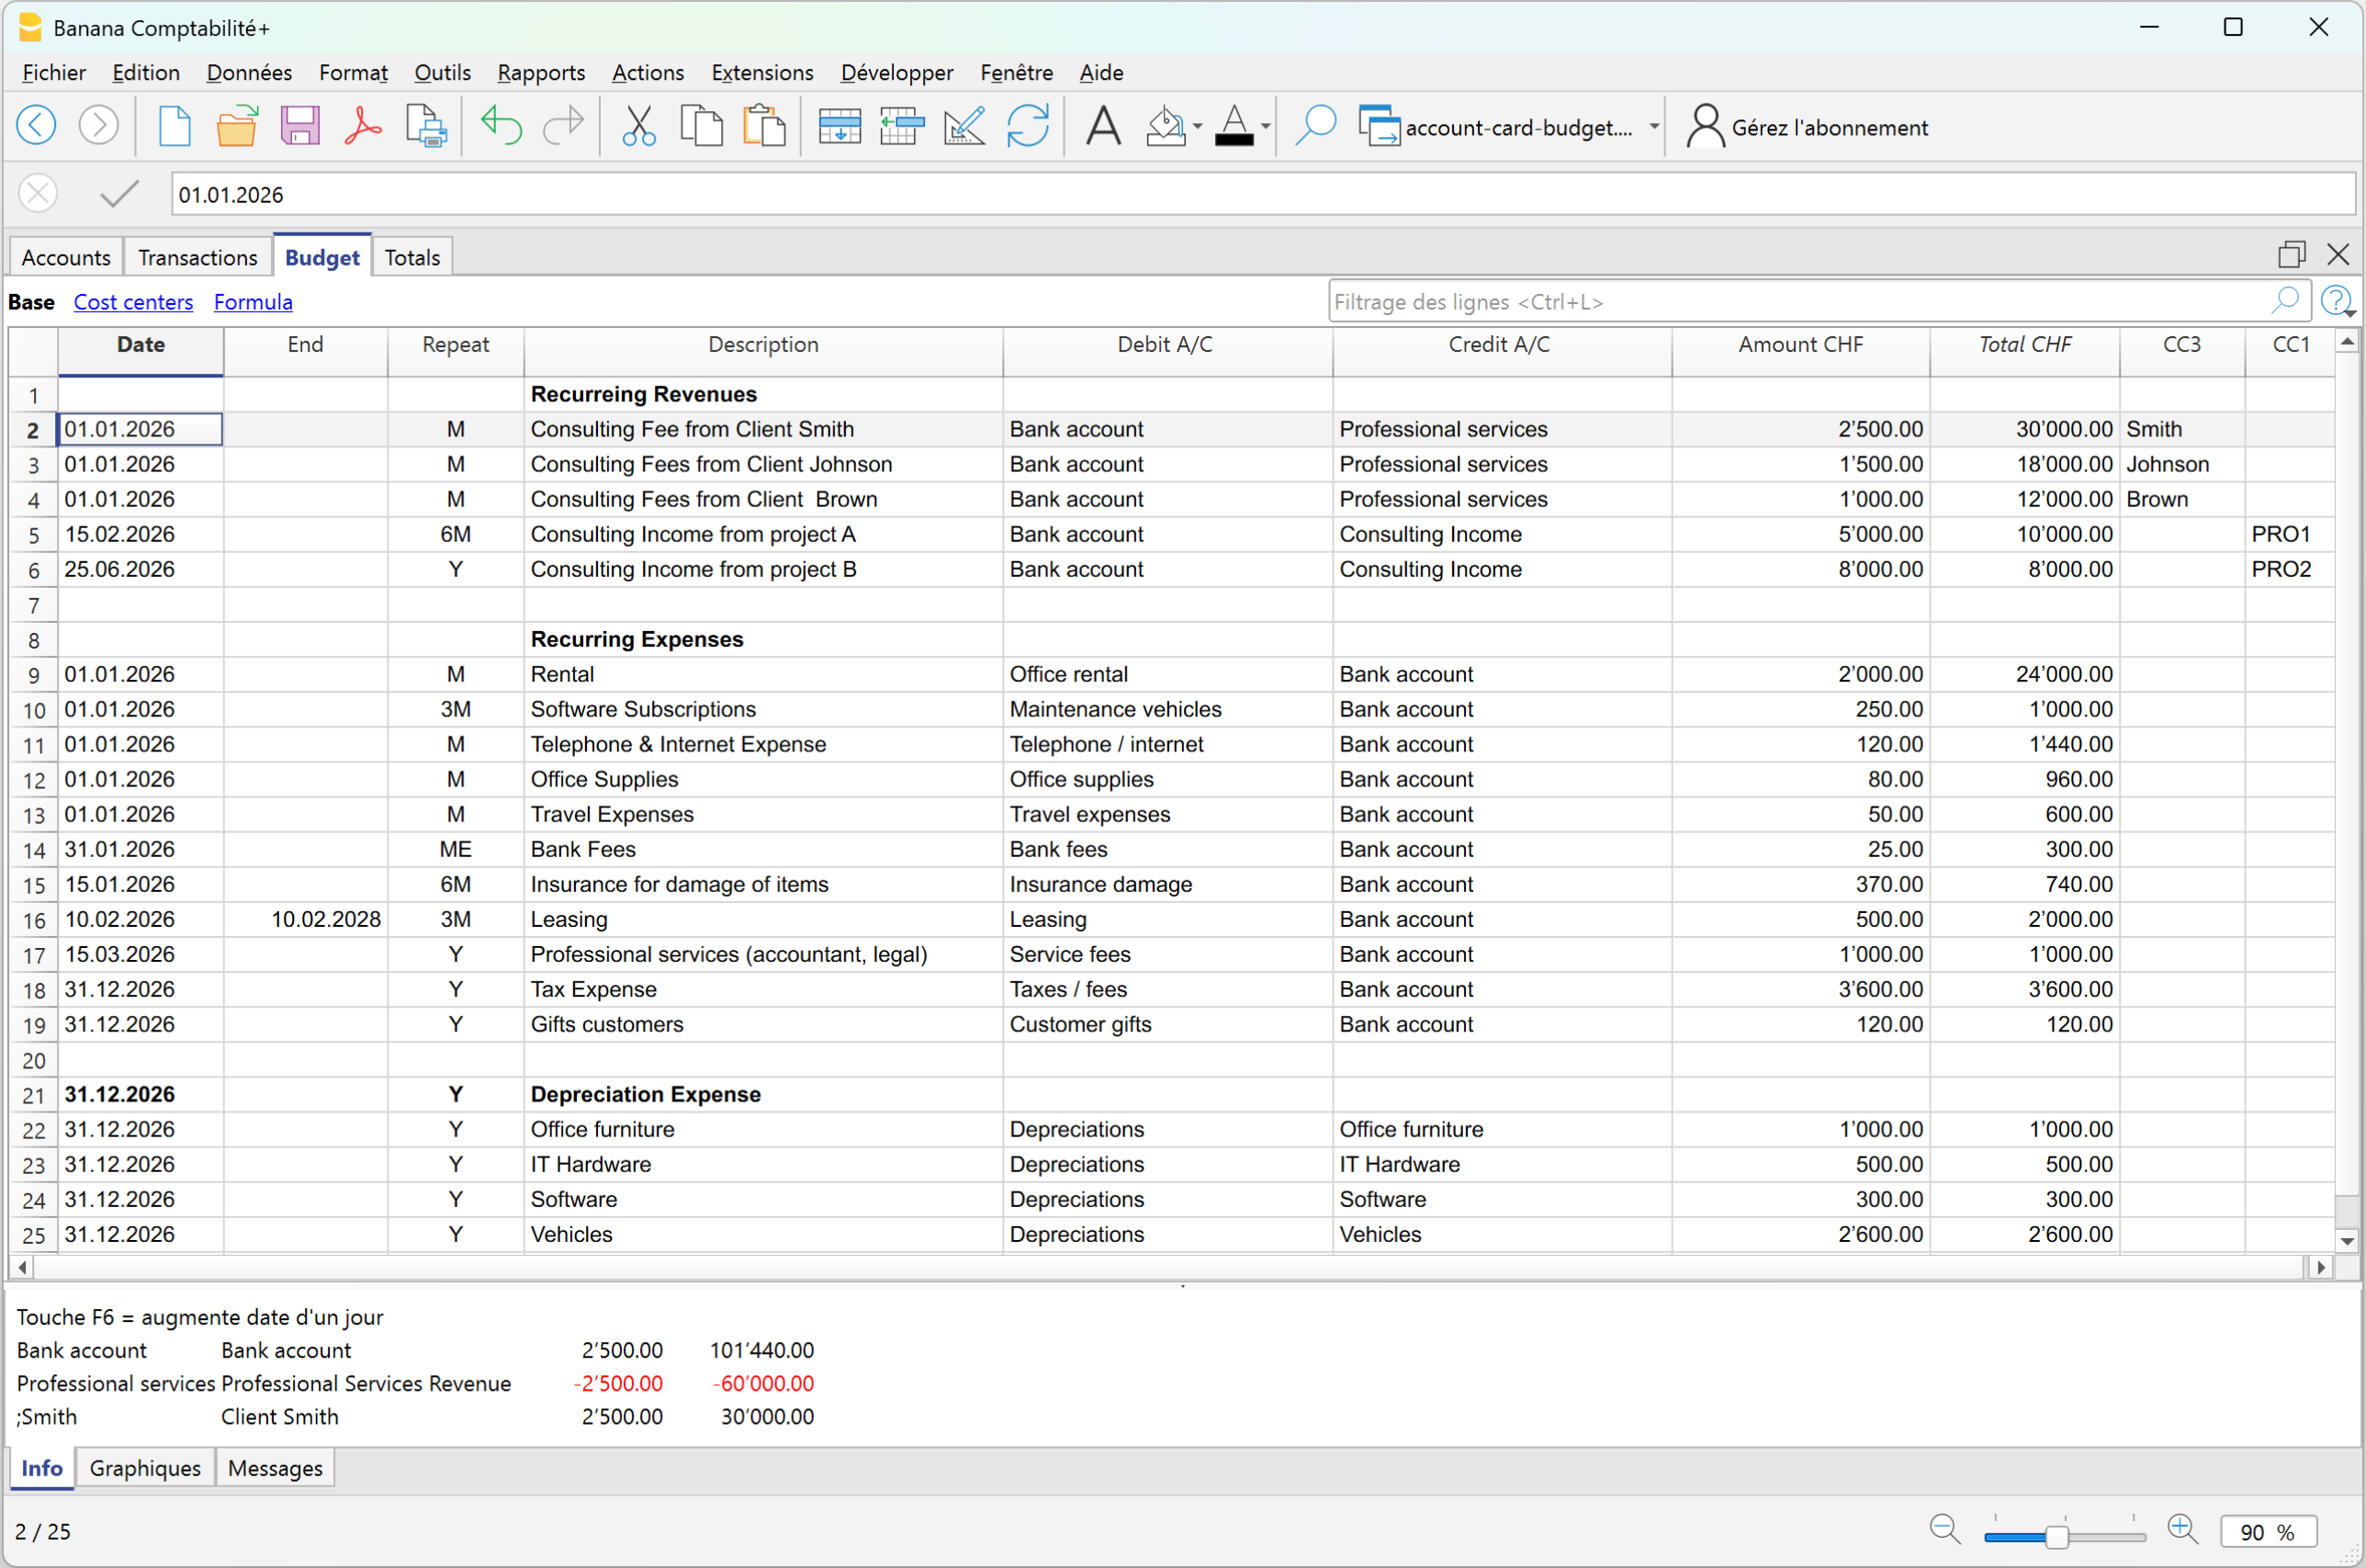
Based on the entered transactions, the program automatically creates all reports, with the same speed and options available in the Enhanced Balance sheet with groups, and reports the balances in the Accounts column, in the Budget view.
Complete forecast reports and comparison with actual data
Forecast reports do not only provide aggregated yearly projections. You can also analyze the data by specific periods: if a cost or revenue occurs only during certain months, the system represents it exactly in the correct periods.
For example: if a cost occurs only in June, July, and August, in the Budget table, by defining the accrual dates, the amount will be assigned exactly to the specific period in the forecast report, without any distribution across other months.
To obtain the forecast balance sheet and profit and loss statement:
- From the menu Reports > Enhanced Balance sheet with groups > in the section Chart of Accounts > Columns, enable Budget
In the Enhanced Balance sheet with groups, if you display the actual, budget, and Budget difference columns, you immediately get an overall view:
Balance Sheet with actual balances, budget balances, and differences
Forecasting in Banana Accounting is not a separate document, but integrates with accounting data and evolves together with real accounting.
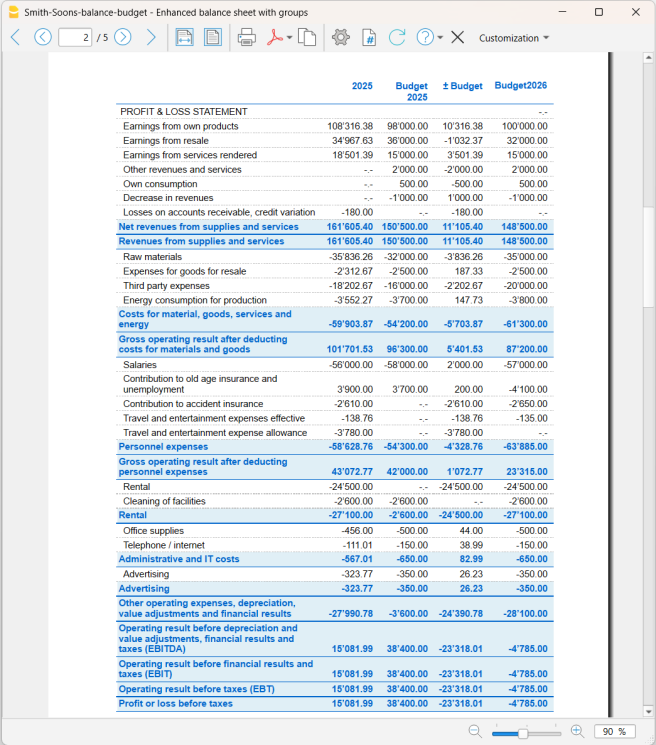
Profit and Loss Statement with actual balances, budget balances, and differences
With this report presentation, you can evaluate whether the company will be profitable and identify possible issues in advance.
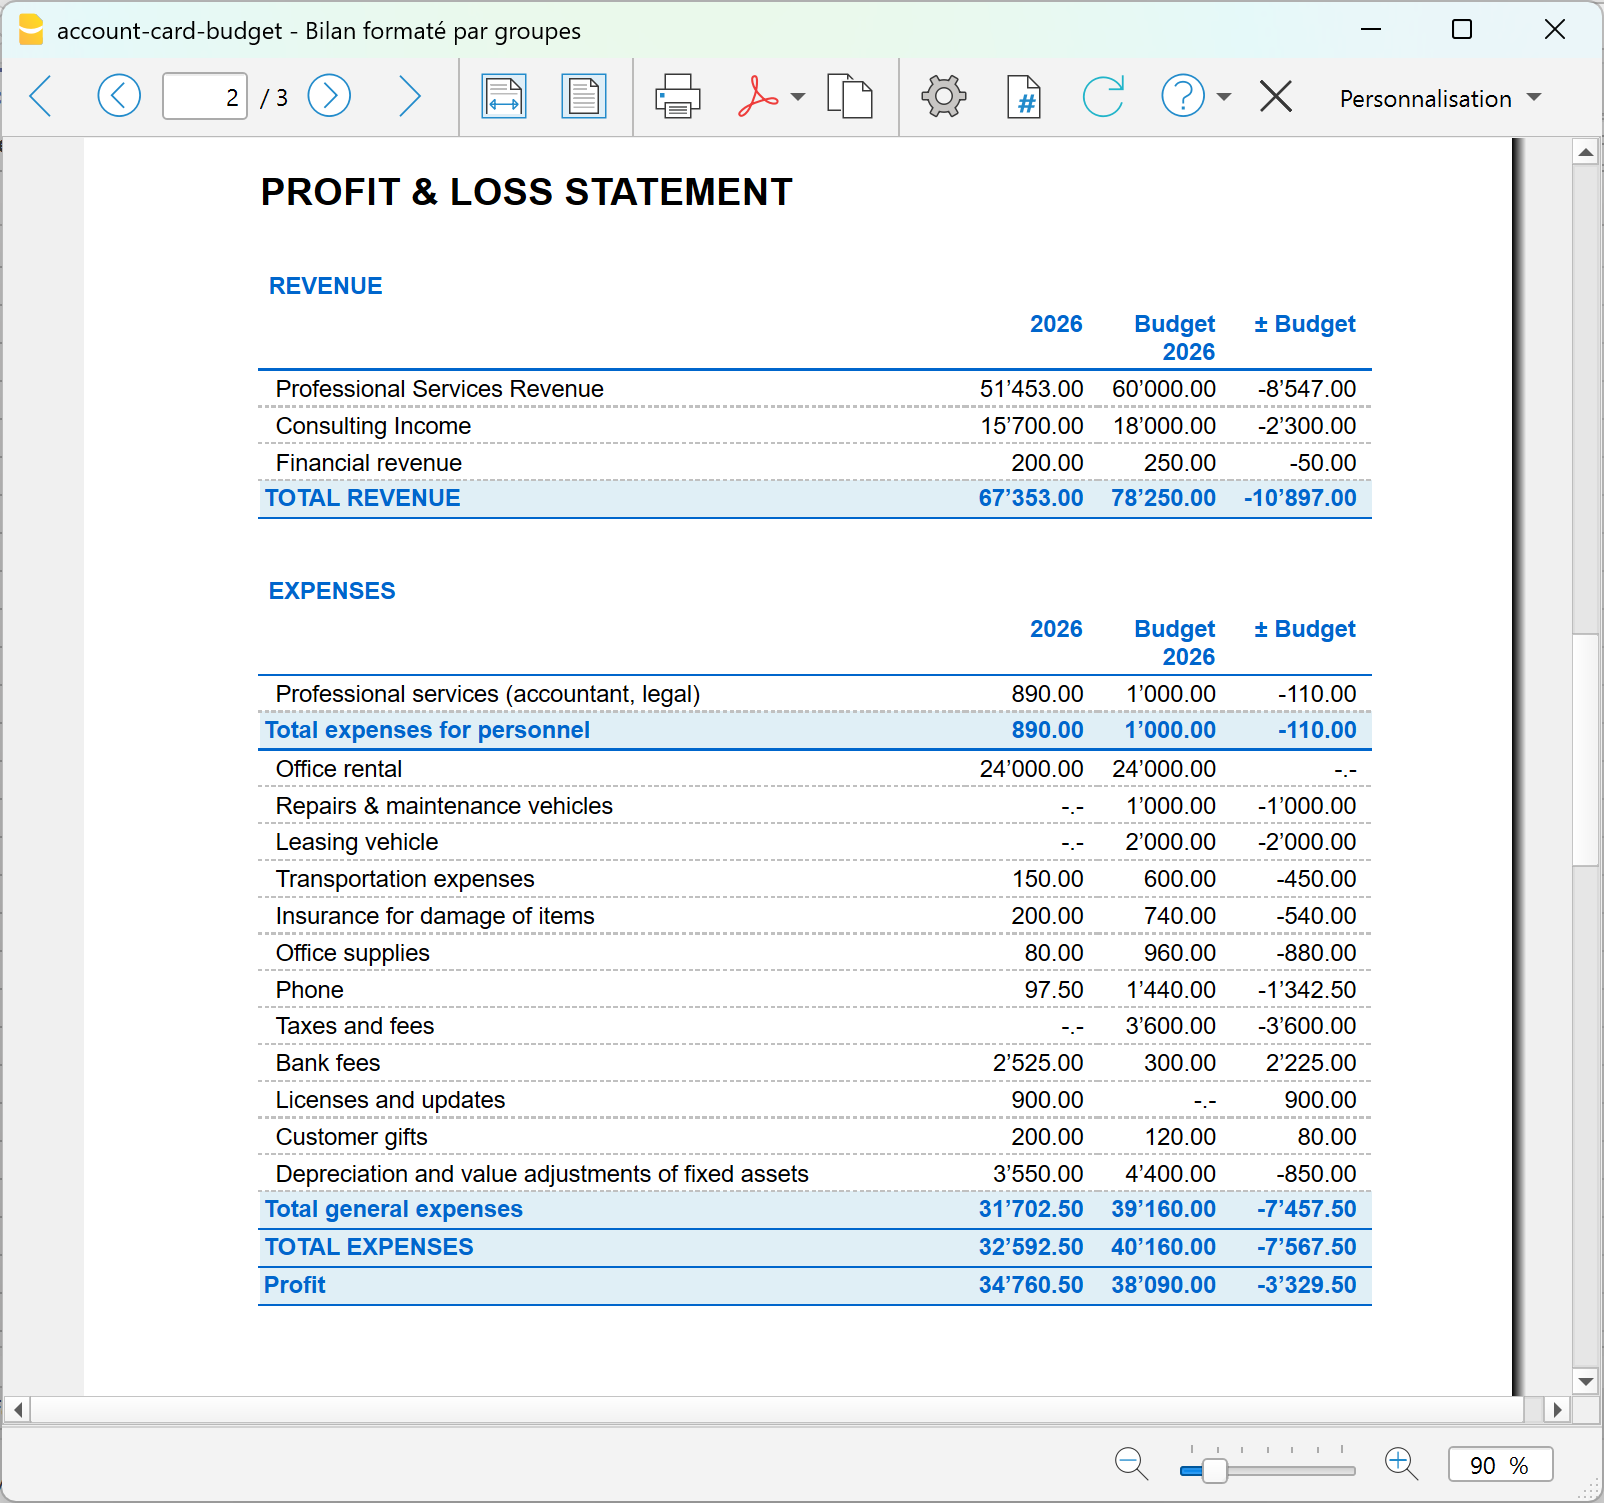
Comparison of actual vs budget account card
With Banana Accounting financial forecasting, you can go beyond traditional forecasting. With the new Account card: Current vs/Budget extension (Beta version), you can compare an account card with both actual transactions and budget transactions.
This is a completely new feature that allows you to:
- analyze in detail the actual transactions compared to the budgeted ones
- easily identify variances shown in the Differences column.
- progressively improve your planning capabilities.
Advantage: customer account card with actual and budget data
With Banana Accounting, for each customer you have a complete account card that integrates:
- actual data → issued invoices and real payments received
- forecast data → future invoices and expected payments
With Banana, the customer account card does not only show what has happened, but also what will happen, with all management details already integrated. In one single view, you can see the past, present, and future.
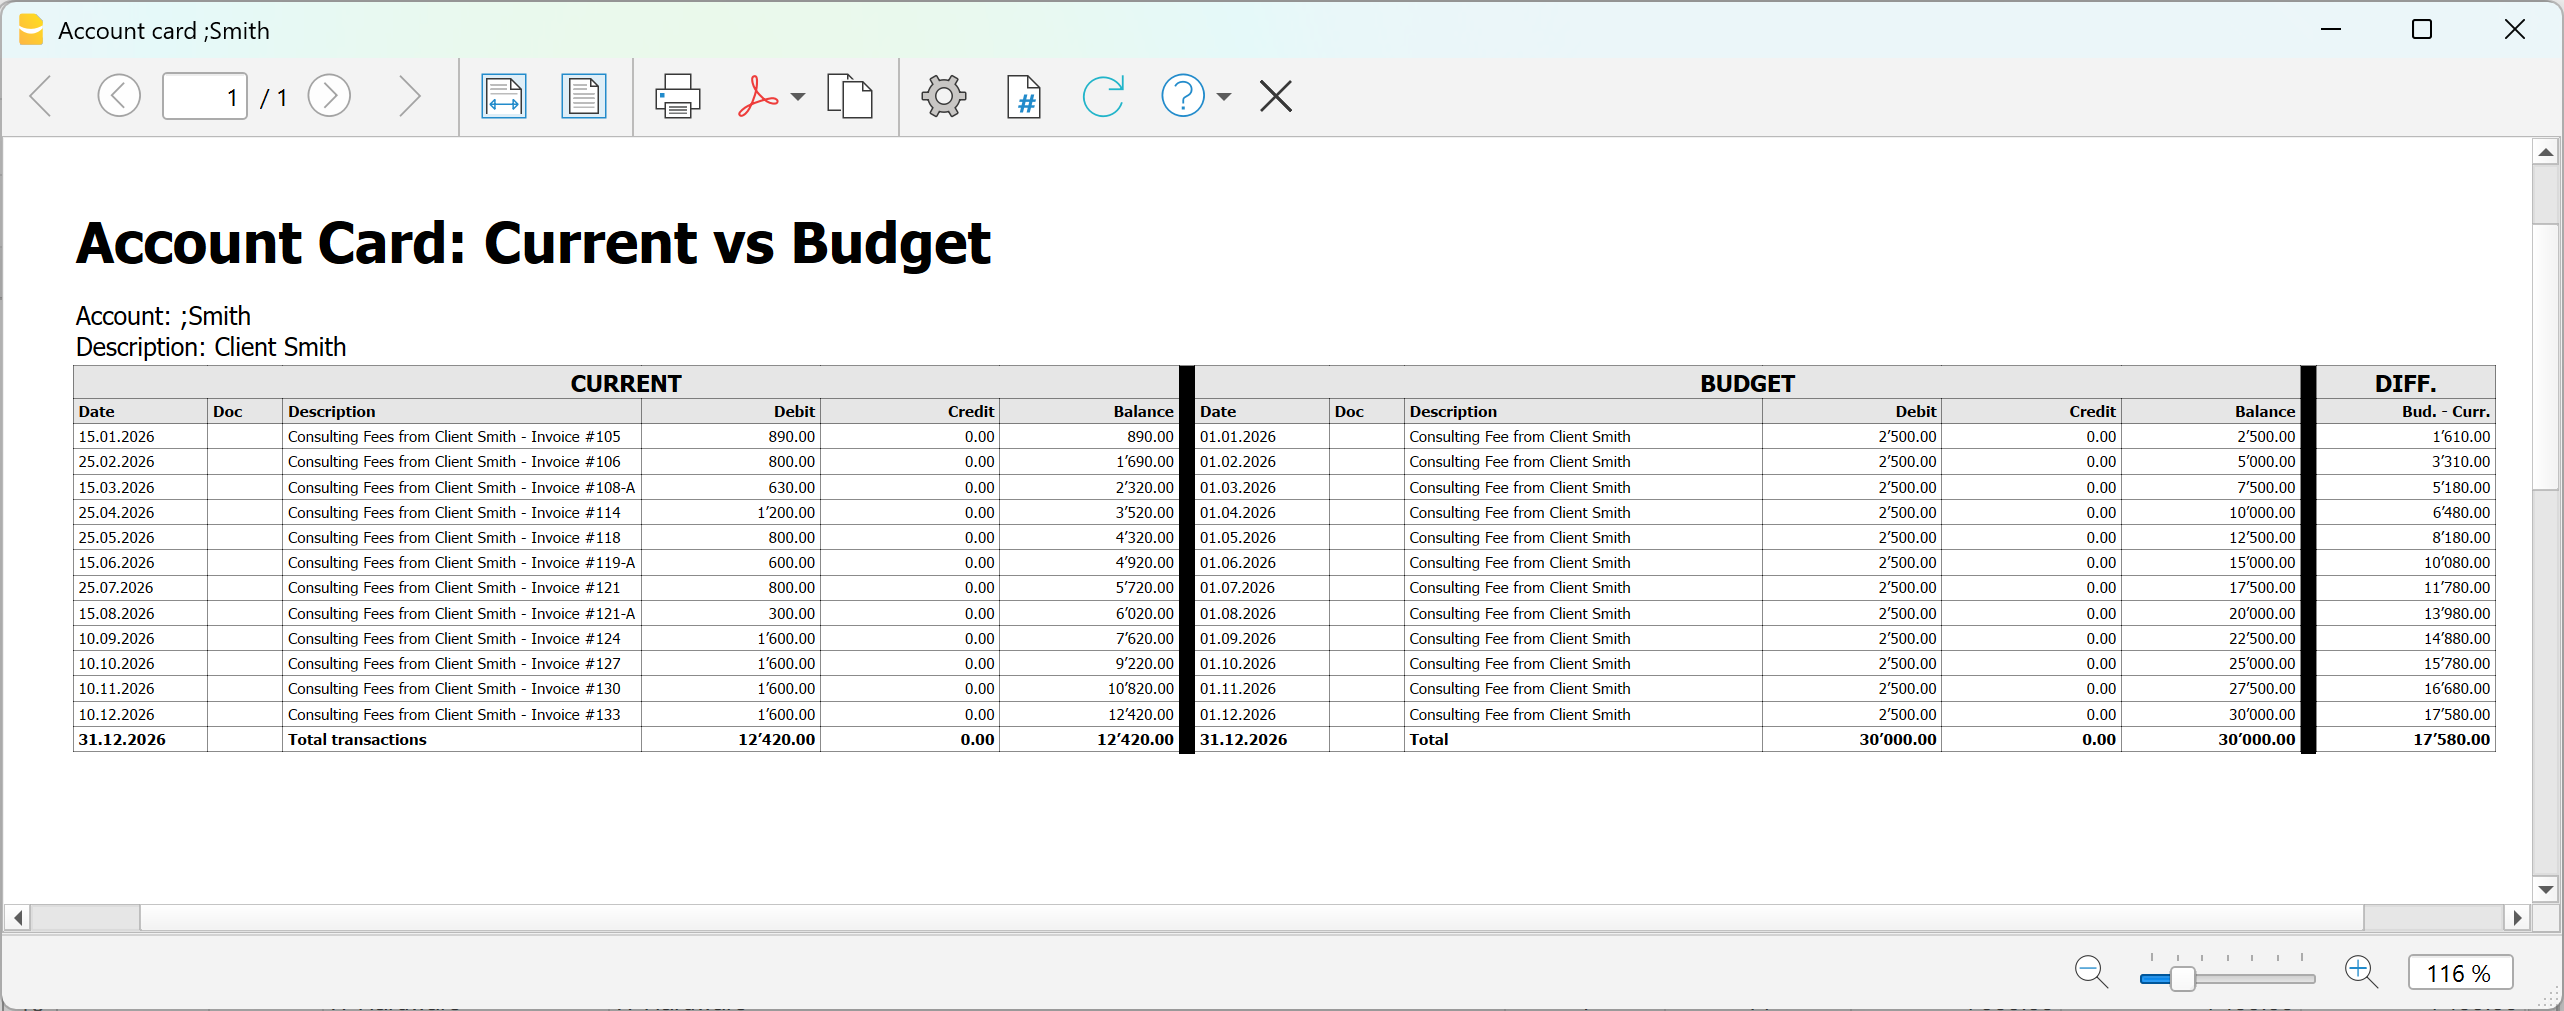
Using the new extension dedicated to the account card, which compares actual and budget transactions, you can analyze in detail:
- Customer
- Project
- Cost center
- Segment
To display the comparison between actual and budget data for an account, you need to:
- Install the Account card current vs budget extension (Beta version)
- From the menu Extensions > Manage extensions > Accout card: current vs budget (Beta version)
- In the dialog window that opens:
Double-click on Account and select from the account list the account (or category), cost center- Two account cards related to the same account are displayed side by side
- In the last column of the budget account card, the Difference column is displayed, highlighting line by line the difference in amounts between actual and budget data.
Summary
With precision financial planning, you can:
- enter detailed forecasts transaction by transaction
- automatically obtain all reports
- monitor liquidity and profitability
- compare forecasts and actual results
- progressively improve decision-making
It is not just about creating a budget, but about using an integrated system to plan and manage the financial future with professional accounting tools.
Pianificazione finanziaria separata dalla contabilità
In this article
Pianificazione finanziaria separata dalla contabilità
Pianificazione finanziaria separata dalla contabilità
La pianificazione finanziaria separata dalla contabilità permette di creare previsioni economiche, finanziarie e patrimoniali in modo indipendente dalla contabilità generale. Consente di simulare ricavi, costi, investimenti e finanziamenti, valutarne gli effetti sulla liquidità e sull'utile e confrontare scenari alternativi. La pianificazione può essere annuale o pluriennale e offre una visione dell'evoluzione futura dell'impresa a supporto delle decisioni aziendali. Si rivolge a medio e grandi imprese e a figure specializzate che devono preparare delle pianificazioni molto dettagliate e avanzate.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebApp Open tutorial in WebAppTemplate documentation
Questo tutorial mostra, con un esempio pratico, come creare e gestire una pianificazione economica, finanziaria e patrimoniale in un file separato dalla contabilità, inserendo nella tabella Preventivo i movimenti previsionali e analizzandone i risultati.
Maggiori info alla pagina della nostra Documentazione: Pianificazione separata dalla contabilità.
Come impostare il file della pianificazione
Per creare il file di pianificazione puoi:
- partire da uno dei modelli predefiniti di contabilità in partita doppia di Banana Contabilità, anche con IVA o multimoneta
- utilizzare come base il piano contabile della tua attività, se disponi già di una struttura contabile
- impostare il periodo di pianificazione, la moneta base e le altre proprietà necessarie.
Nel nostro esempio viene preparata la pianificazione finanziaria di uno studio fiduciario già avviato.
Partendo dalla situazione esistente e formulando ipotesi sull'evoluzione dei clienti e delle consulenze, sugli investimenti e sull'eventuale assunzione di un nuovo collaboratore, viene elaborata una previsione per valutare l'evoluzione futura della liquidità, del risultato d'esercizio e della situazione patrimoniale.
Per creare il file:
- Dal menu File > Nuovo, seleziona la tipologia di contabilità e il modello più adatto alle tue esigenze.
- Dal menu File > Proprietà file > Dati base, inserisci i dati della pianificazione, come nome dell'azienda, periodo e moneta base.
- Se utilizzi una contabilità multimoneta o con IVA, verifica le relative impostazioni. Nei modelli predefiniti i conti necessari, come quelli per le differenze di cambio e l'IVA, sono già predisposti.
Se nel file della contabilità la tabella Preventivo non è visibile, puoi aggiungerla dal menu Strumenti > Aggiungi Tabella Preventivo.
La tabella Registrazioni rimane comunque disponibile. Se non viene utilizzata, puoi nasconderla dal menu Dati > Disponi tabelle, impostando la tabella Registrazioni come non visibile.
Le registrazioni inserite nella tabella Preventivo vengono utilizzate per calcolare automaticamente i valori previsionali dei conti e ottenere report economici, finanziari e patrimoniali.
Struttura della pianificazione
La pianificazione viene gestita in un unico file dedicato e si basa sulla logica della partita doppia, consentendo di simulare contabilmente l'evoluzione futura dell'impresa.
Il file utilizza principalmente due tabelle:
- la tabella Conti, che definisce la struttura contabile e mostra i valori risultanti dalla pianificazione;
- la tabella Preventivo, nella quale vengono inserite le registrazioni previsionali e le ipotesi su cui si basa la pianificazione.
Come creare una pianificazione
Per creare la pianificazione, imposta nella tabella Conti la situazione patrimoniale iniziale e inserisci nella tabella Preventivo le operazioni future previste. Banana calcola automaticamente gli effetti delle registrazioni sulla situazione economica, finanziaria e patrimoniale.
Tabella Conti
Se hai scelto uno dei modelli predefiniti, la tabella Conti contiene già i conti necessari per iniziare la pianificazione.
Puoi personalizzare il piano contabile aggiungendo o eliminando conti e gruppi di totalizzazione in funzione delle tue esigenze. Per maggiori informazioni consulta la pagina Tabella Conti.
I saldi effettivi alla data di inizio della pianificazione possono essere riportati nella colonna Apertura e utilizzati come situazione patrimoniale iniziale da cui sviluppare le previsioni.
Per i conti dello Stato patrimoniale, i valori del Preventivo partono quindi dai saldi iniziali di apertura.
Per i conti del Conto economico, invece, prima dell'inserimento delle registrazioni previsionali i valori del Preventivo sono a zero.
Tabella Preventivo
La tabella Preventivo è il cuore della pianificazione. Qui vengono registrate le operazioni previsionali utilizzando la logica della partita doppia.
Puoi pianificare, ad esempio:
- ricavi e relativi incassi
- acquisti e pagamenti
- salari e altri costi d'esercizio
- investimenti e ammortamenti
- nuovi finanziamenti
- rimborsi di finanziamenti e relativi interessi
- altre operazioni previste.
La tabella permette inoltre di gestire facilmente le operazioni ricorrenti. Non è necessario inserire manualmente una registrazione per ogni ricorrenza: attraverso le colonne Data inizio, Data fine e Ripeti puoi definire la periodicità dell'operazione, ad esempio giornaliera, mensile, trimestrale, semestrale o annuale.
Banana calcola automaticamente le ricorrenze e i relativi valori complessivi. In questo modo la pianificazione diventa dinamica e i report previsionali tengono conto automaticamente della periodicità delle operazioni.
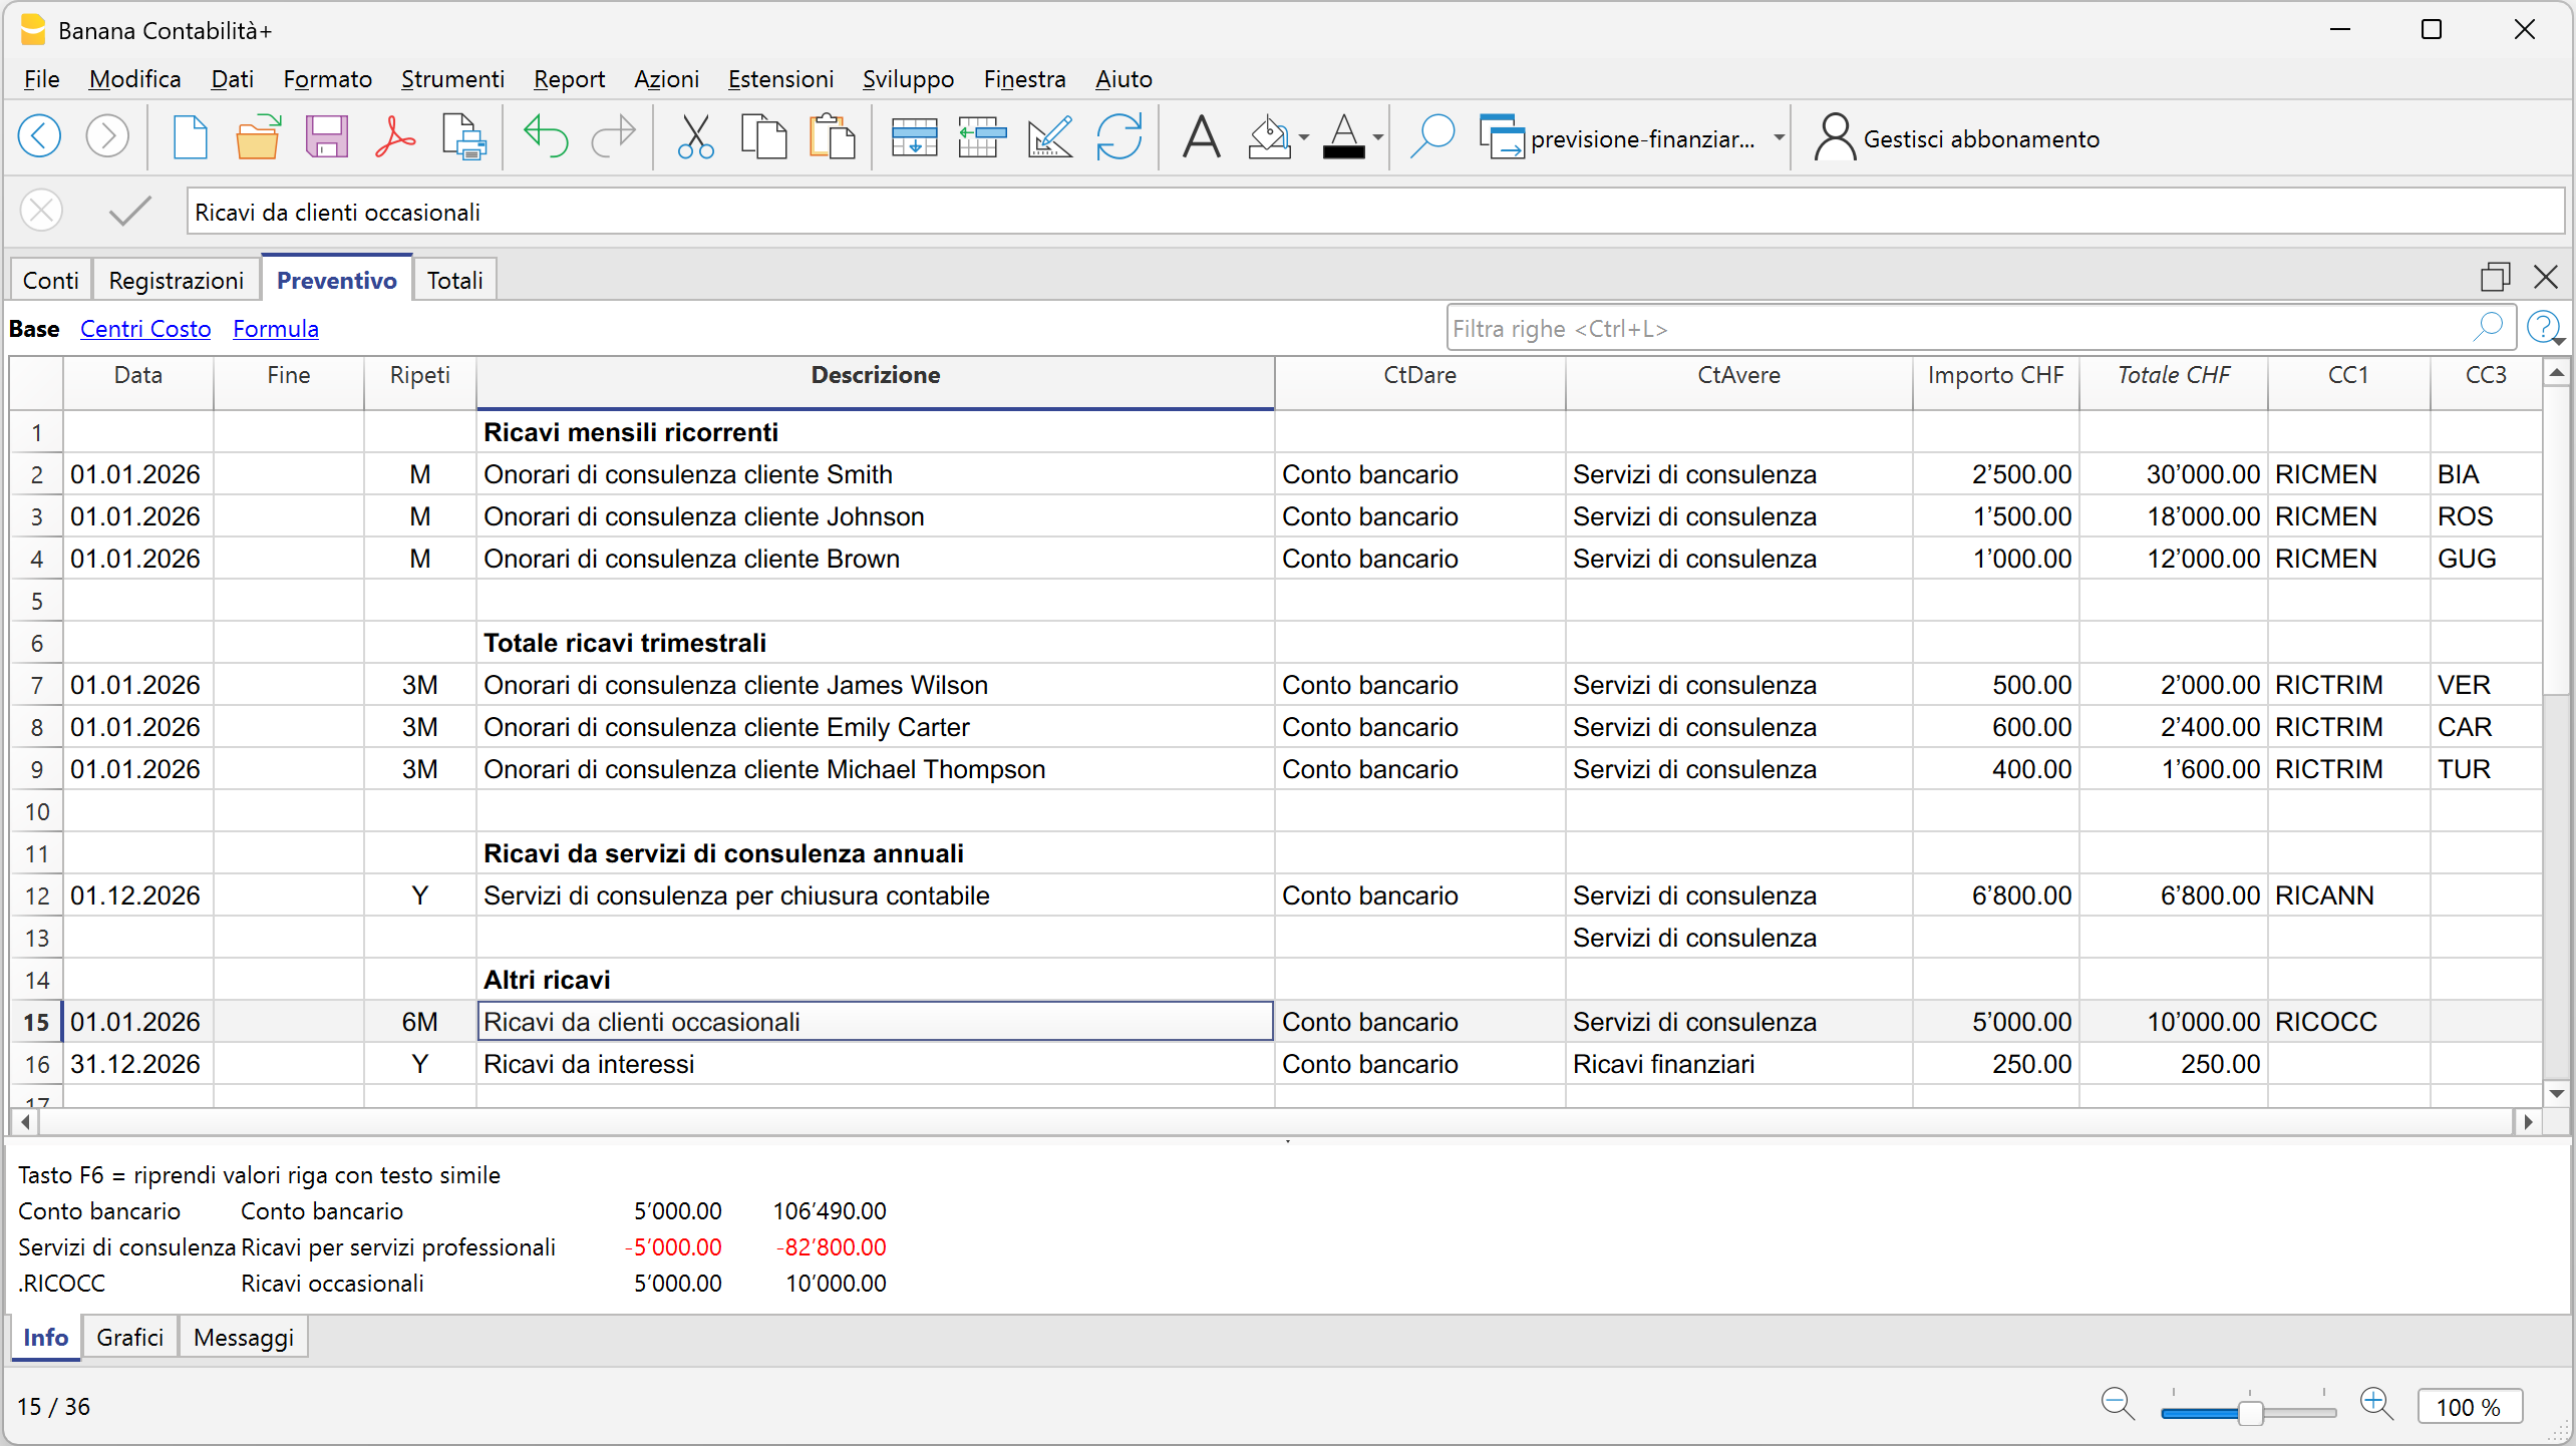
Effetti della pianificazione
Ogni registrazione inserita nella tabella Preventivo produce automaticamente i relativi effetti economici, finanziari e patrimoniali.
Una registrazione previsionale può quindi incidere contemporaneamente sulla liquidità, sui conti dello Stato patrimoniale, sui ricavi e sui costi del Conto economico e, di conseguenza, sull'utile o sulla perdita prevista.
Non è necessario predisporre formule separate per collegare questi elementi: gli effetti derivano automaticamente dalle registrazioni in partita doppia.
Nell'esempio puoi osservare come cambiano gli importi nelle colonne Preventivo e Differenza preventivo dopo l'inserimento delle operazioni previsionali.
Impatto sullo Stato patrimoniale e sulla liquidità
Dopo l'inserimento delle prime registrazioni previsionali, la liquidità prevista passa dal valore iniziale di CHF 104'400.00 a CHF 197'890.00.
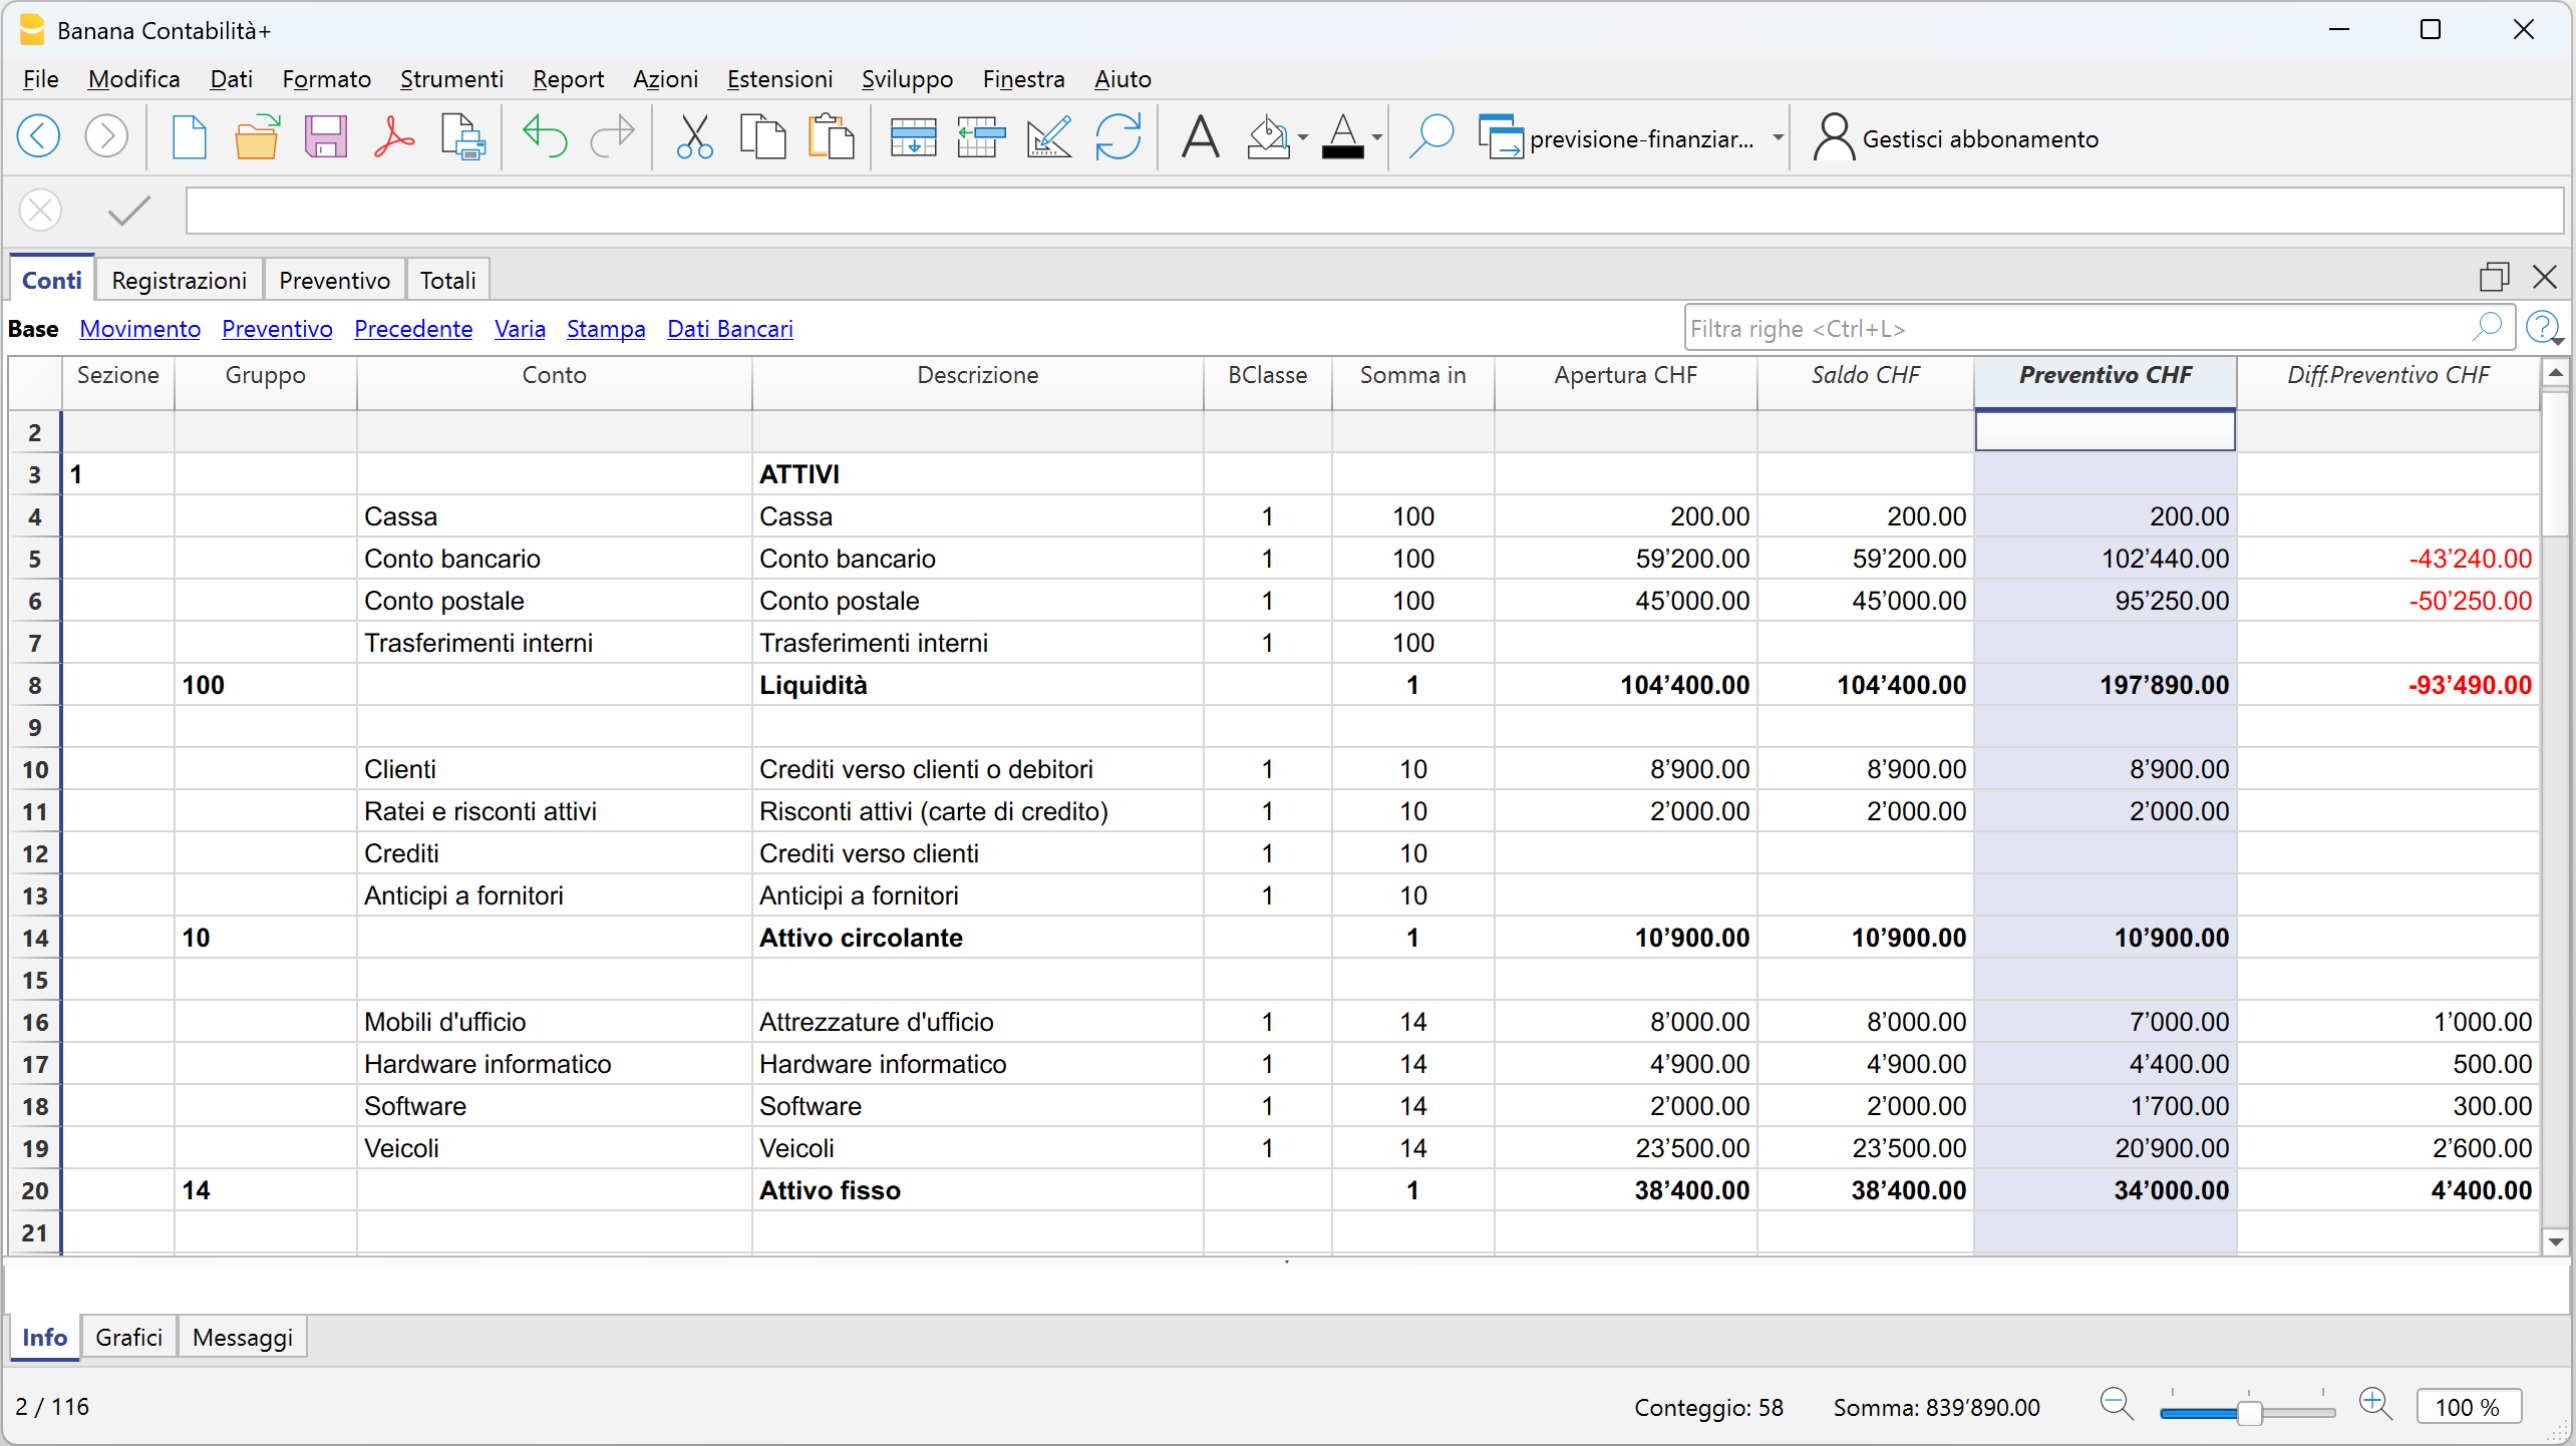
Impatto sul Conto economico
Il Conto economico viene aggiornato automaticamente sulla base delle registrazioni previsionali e determina l'utile o la perdita prevista.
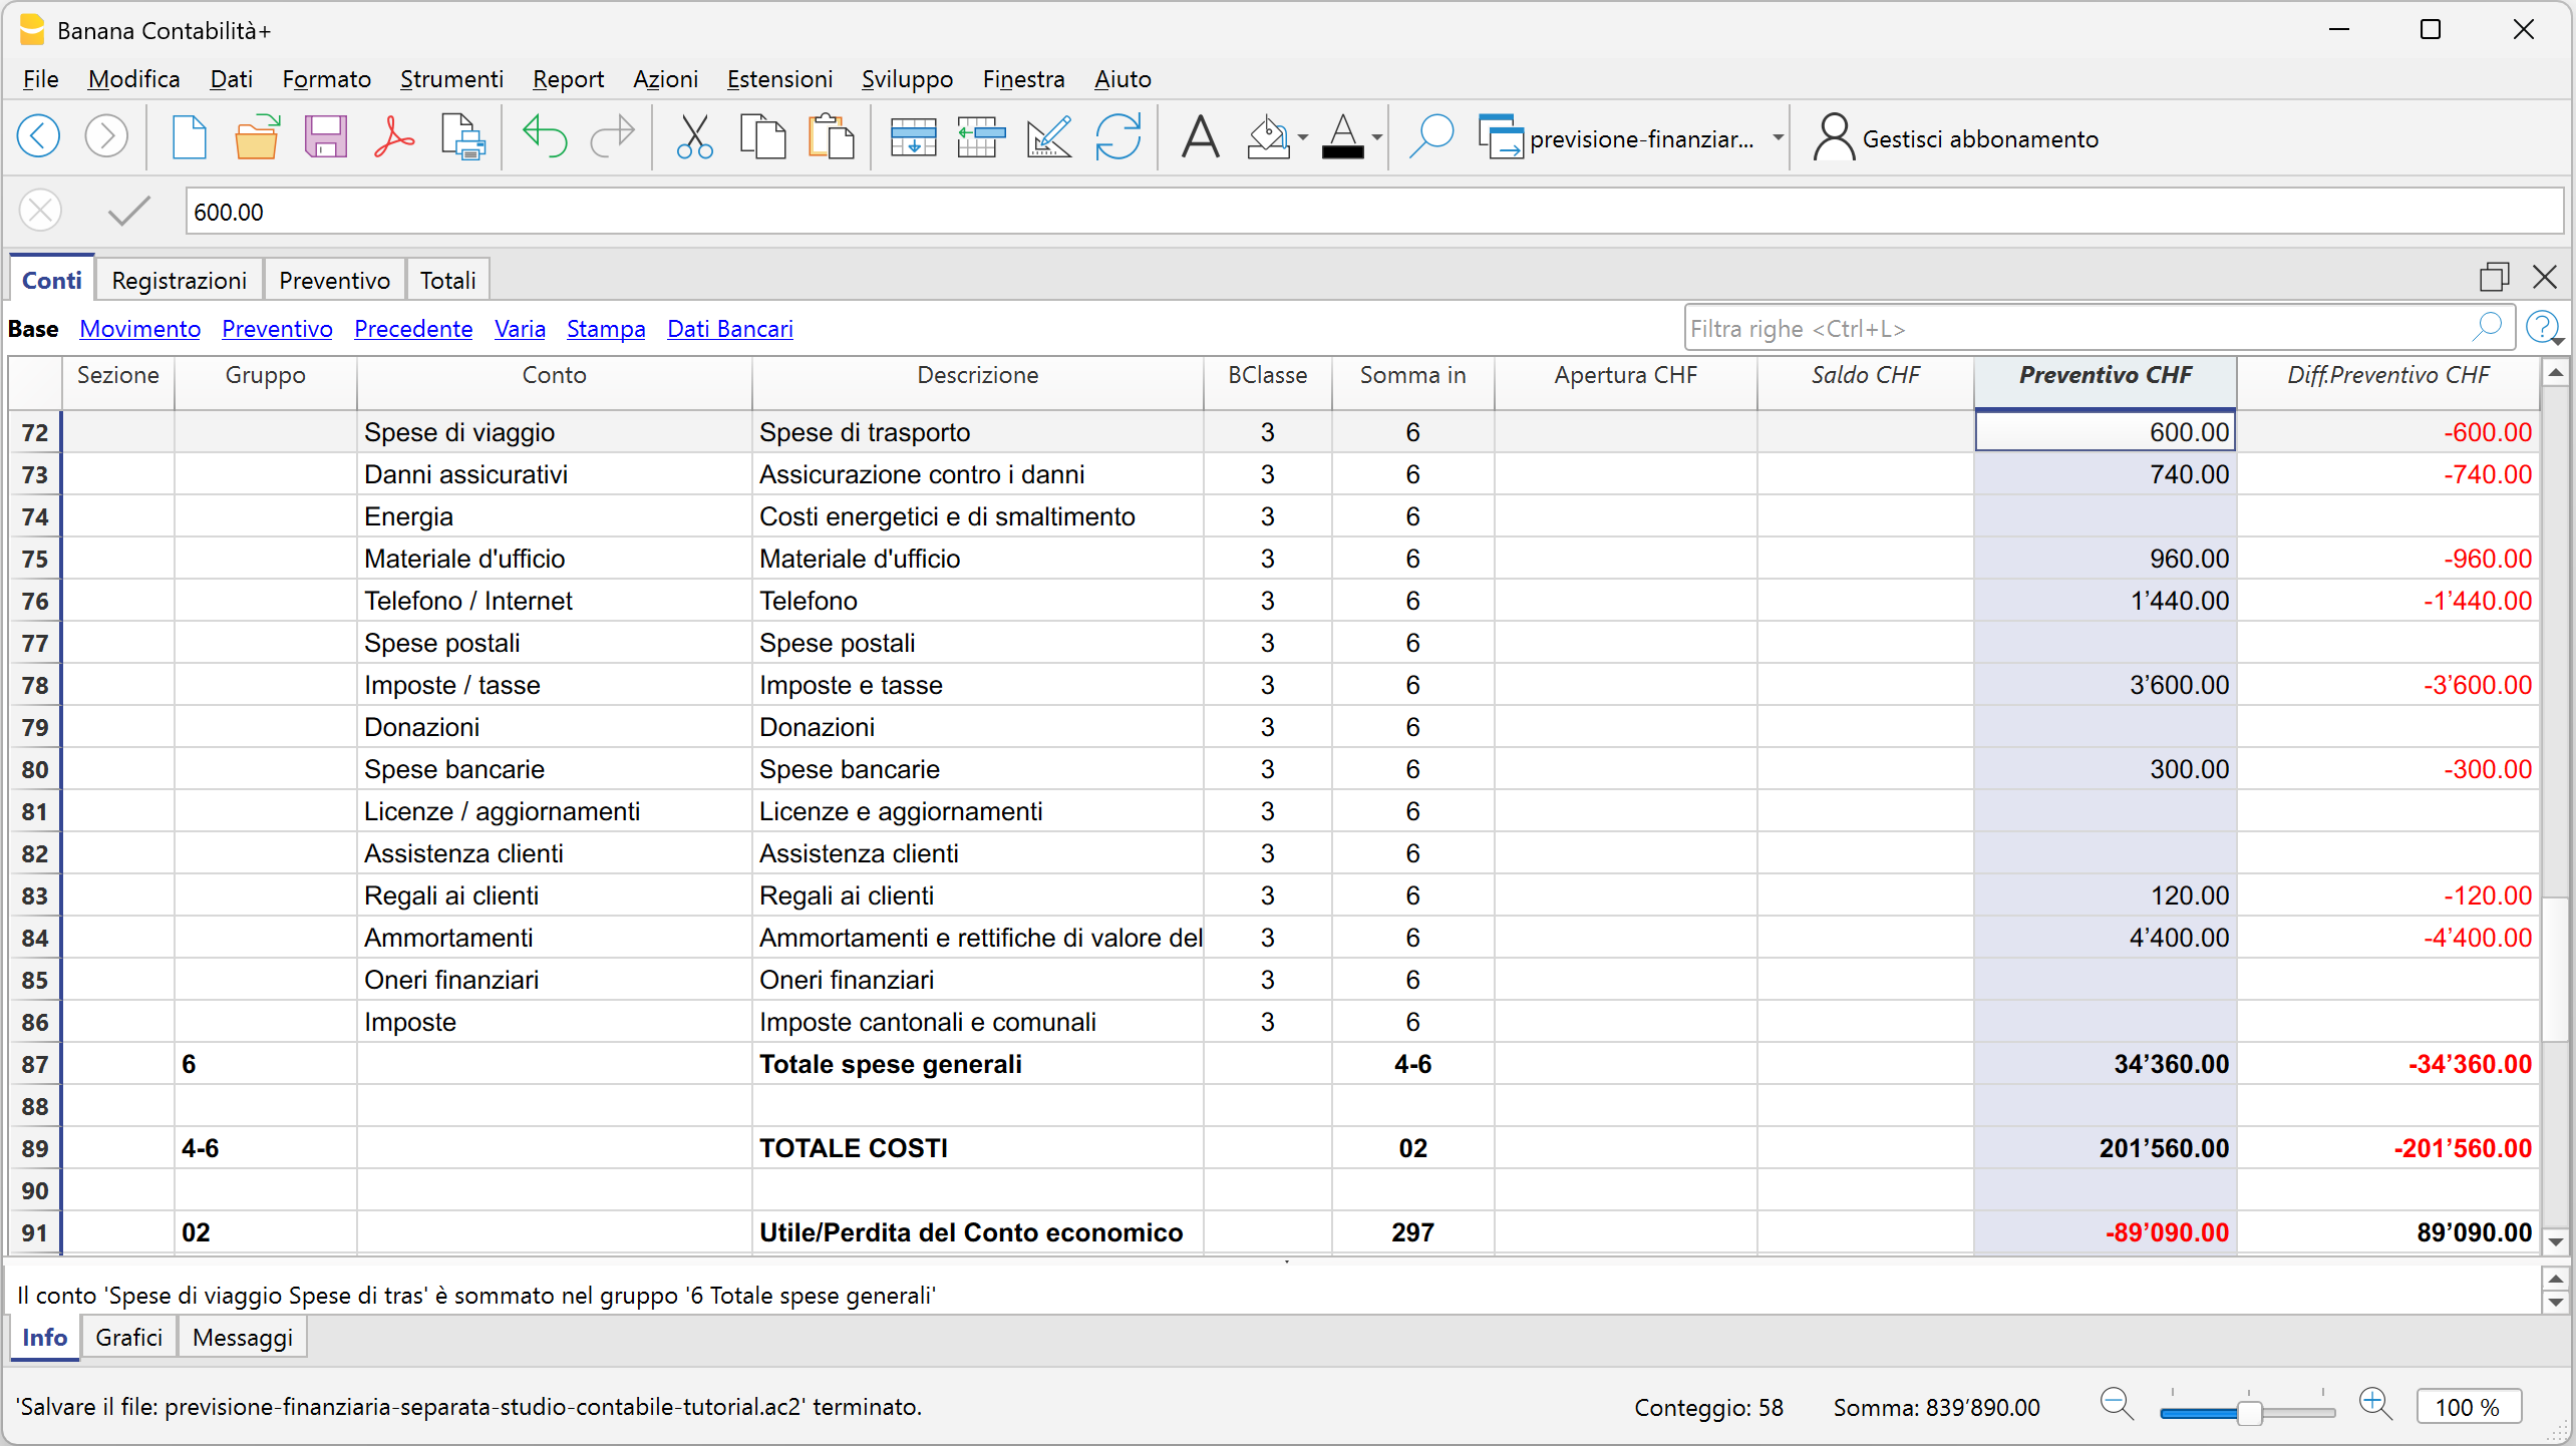
Modificare ipotesi e simulare scenari
Una volta creata la pianificazione di base, puoi modificare le ipotesi e simulare scenari alternativi per confrontarne i risultati con quelli della pianificazione iniziale.
Puoi aggiungere nuove registrazioni previsionali, modificare quelle esistenti oppure utilizzare quantità, prezzi, variabili e formule per verificare come il cambiamento di determinate ipotesi influisce sui risultati complessivi.
Quando un dato viene modificato, Banana ricalcola automaticamente gli effetti collegati, permettendo di verificare immediatamente l'impatto sulla liquidità, sul risultato d'esercizio e sulla situazione patrimoniale.
Ipotesi: aumento delle consulenze del 10%
Supponiamo di voler valutare gli effetti di un aumento del 10% delle consulenze.
Nella tabella Preventivo puoi utilizzare quantità, prezzi unitari, variabili e formule:
- visualizza le colonne Quantità, Prezzo unitario e Formula
- inserisci i valori nelle colonne Quantità e Prezzo unitario
- definisci una variabile per lo scenario di base, ad esempio a = 1
- modifica la variabile per simulare un aumento del 10%, ad esempio a = 1.1
- nella colonna Formula inserisci la formula che utilizza la variabile.
Modificando la variabile, Banana ricalcola automaticamente le registrazioni previsionali interessate e i relativi risultati.
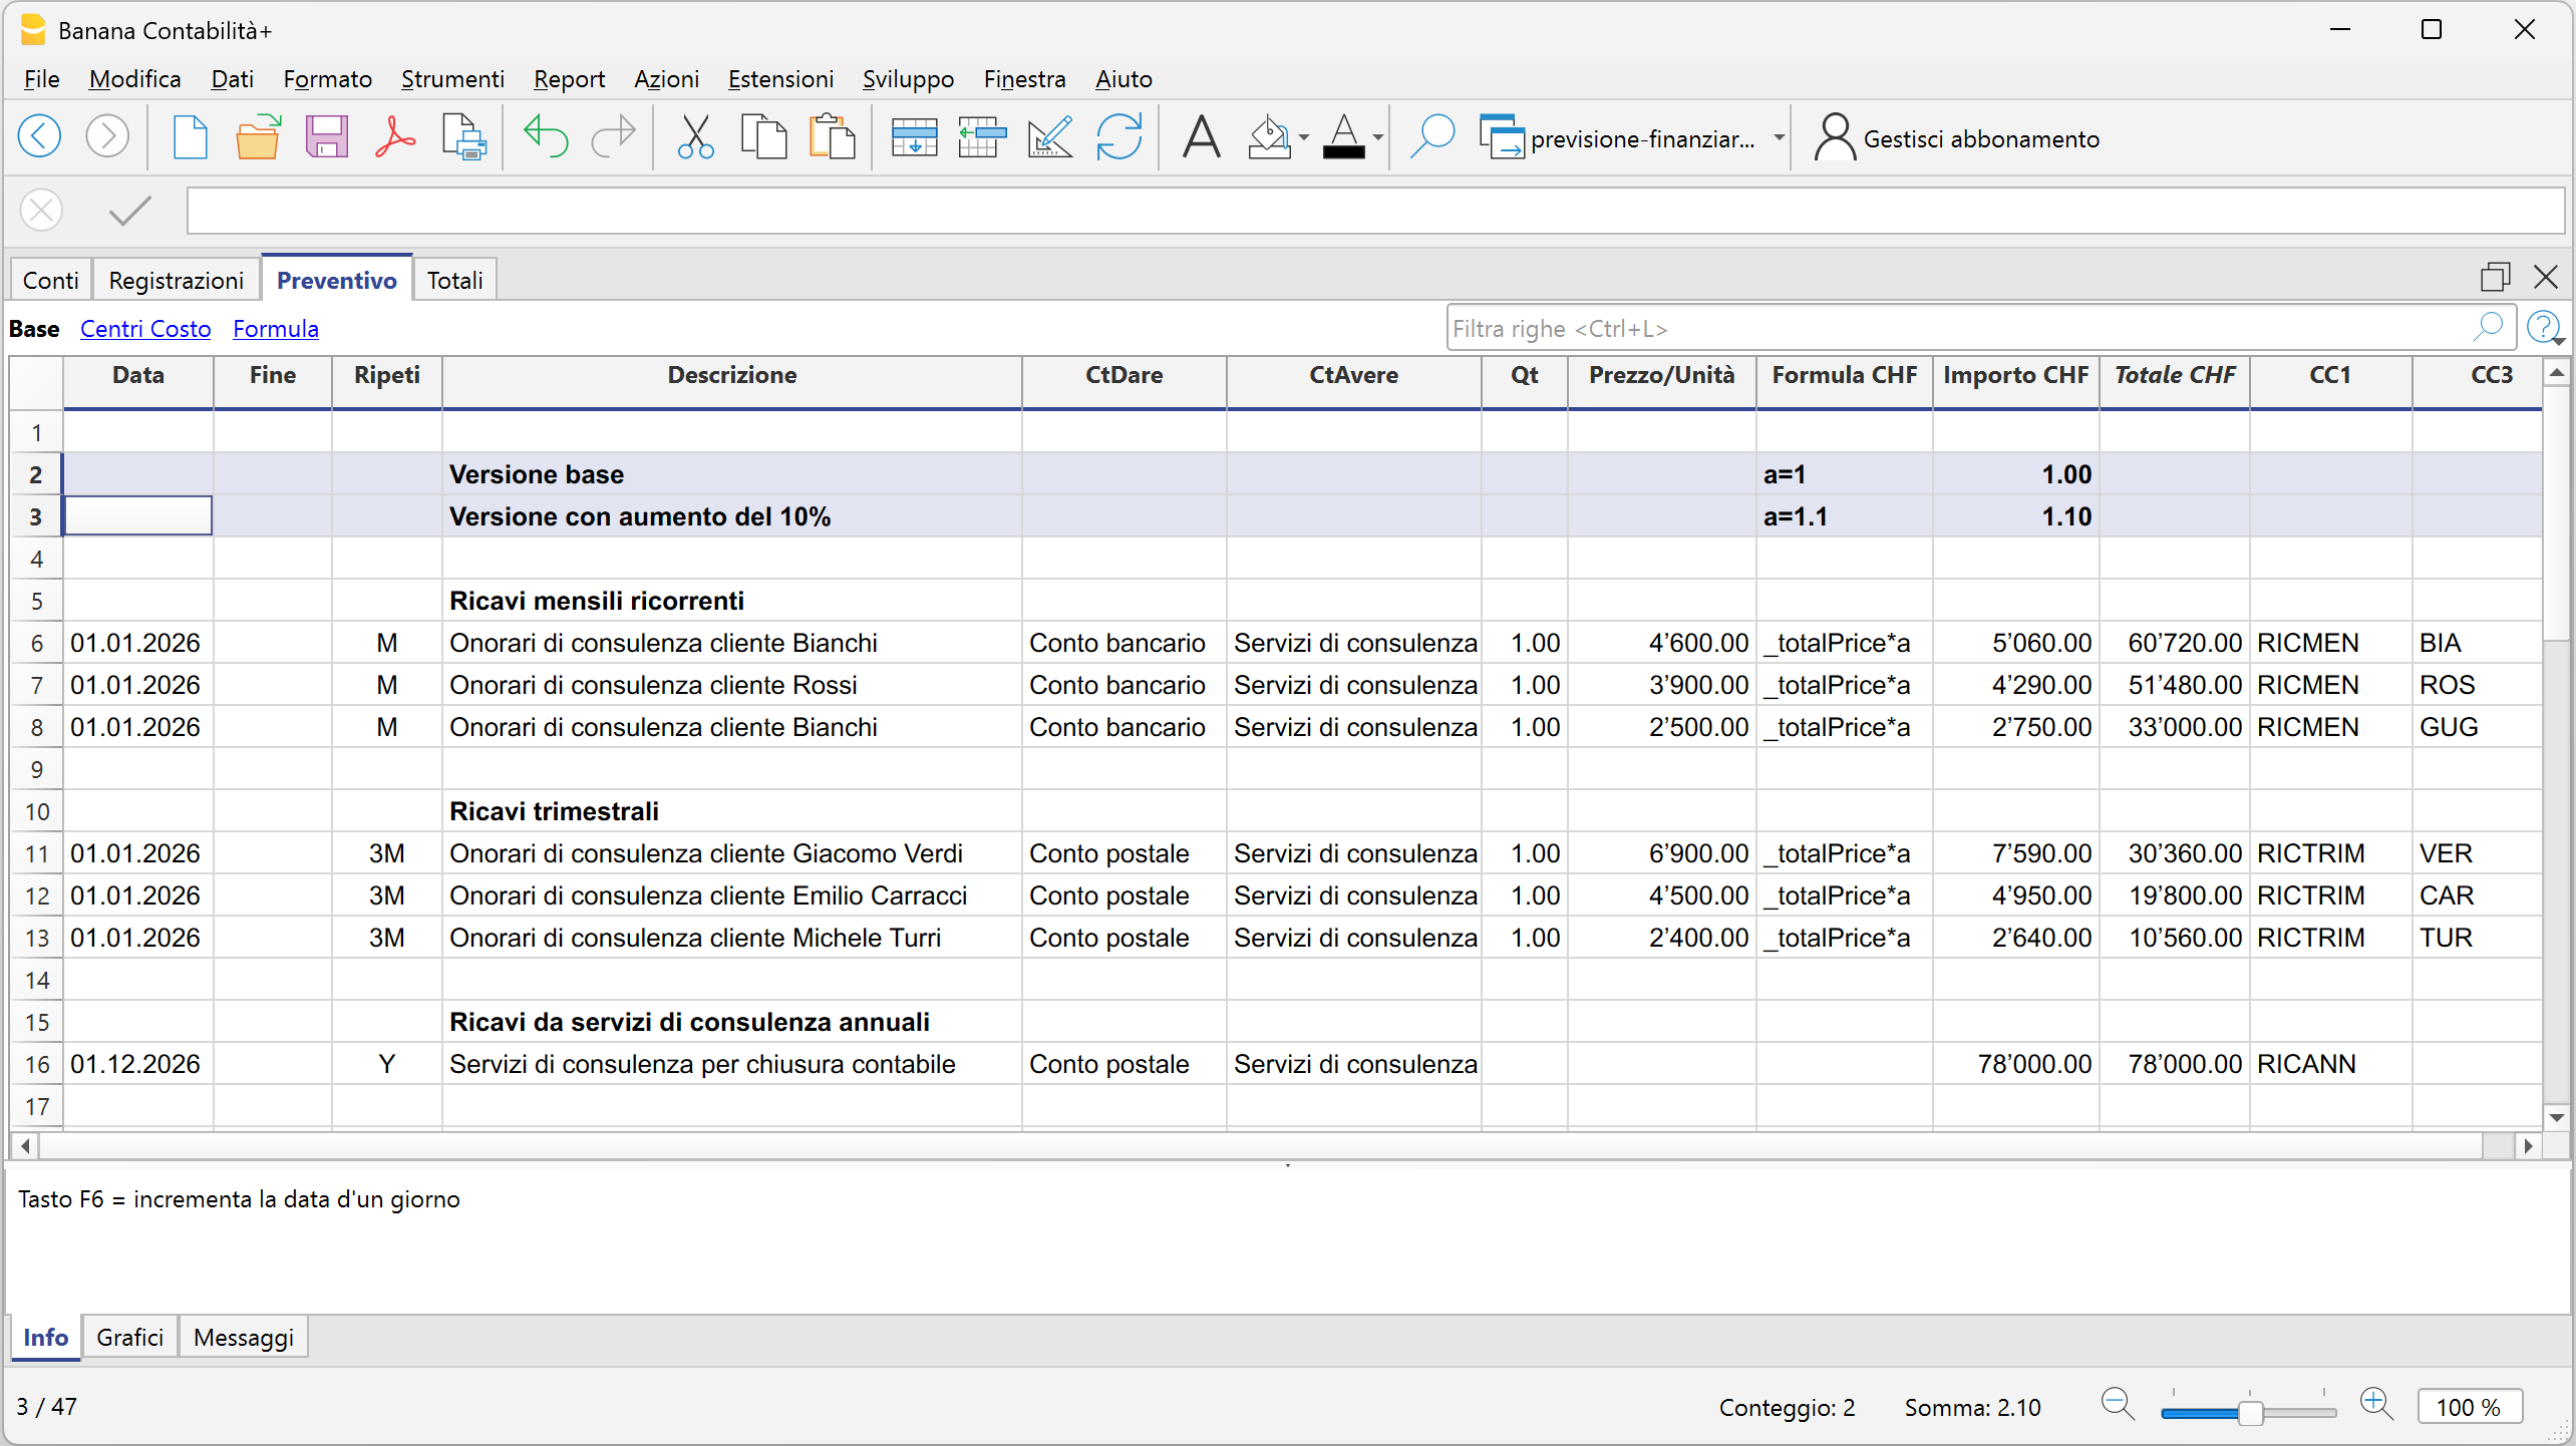
Ipotesi: assunzione di un nuovo collaboratore dal 01.07.2026
Per valutare l'impatto dell'assunzione di un nuovo collaboratore, nella tabella Preventivo vengono aggiunte le registrazioni previsionali necessarie con data di inizio 01.07.2026.
Oltre al salario devono essere considerate anche le relative componenti, come i contributi e gli altri costi del personale previsti.
Banana permette così di verificare l'impatto della nuova assunzione sui costi del personale, sul risultato d'esercizio e sulla liquidità.
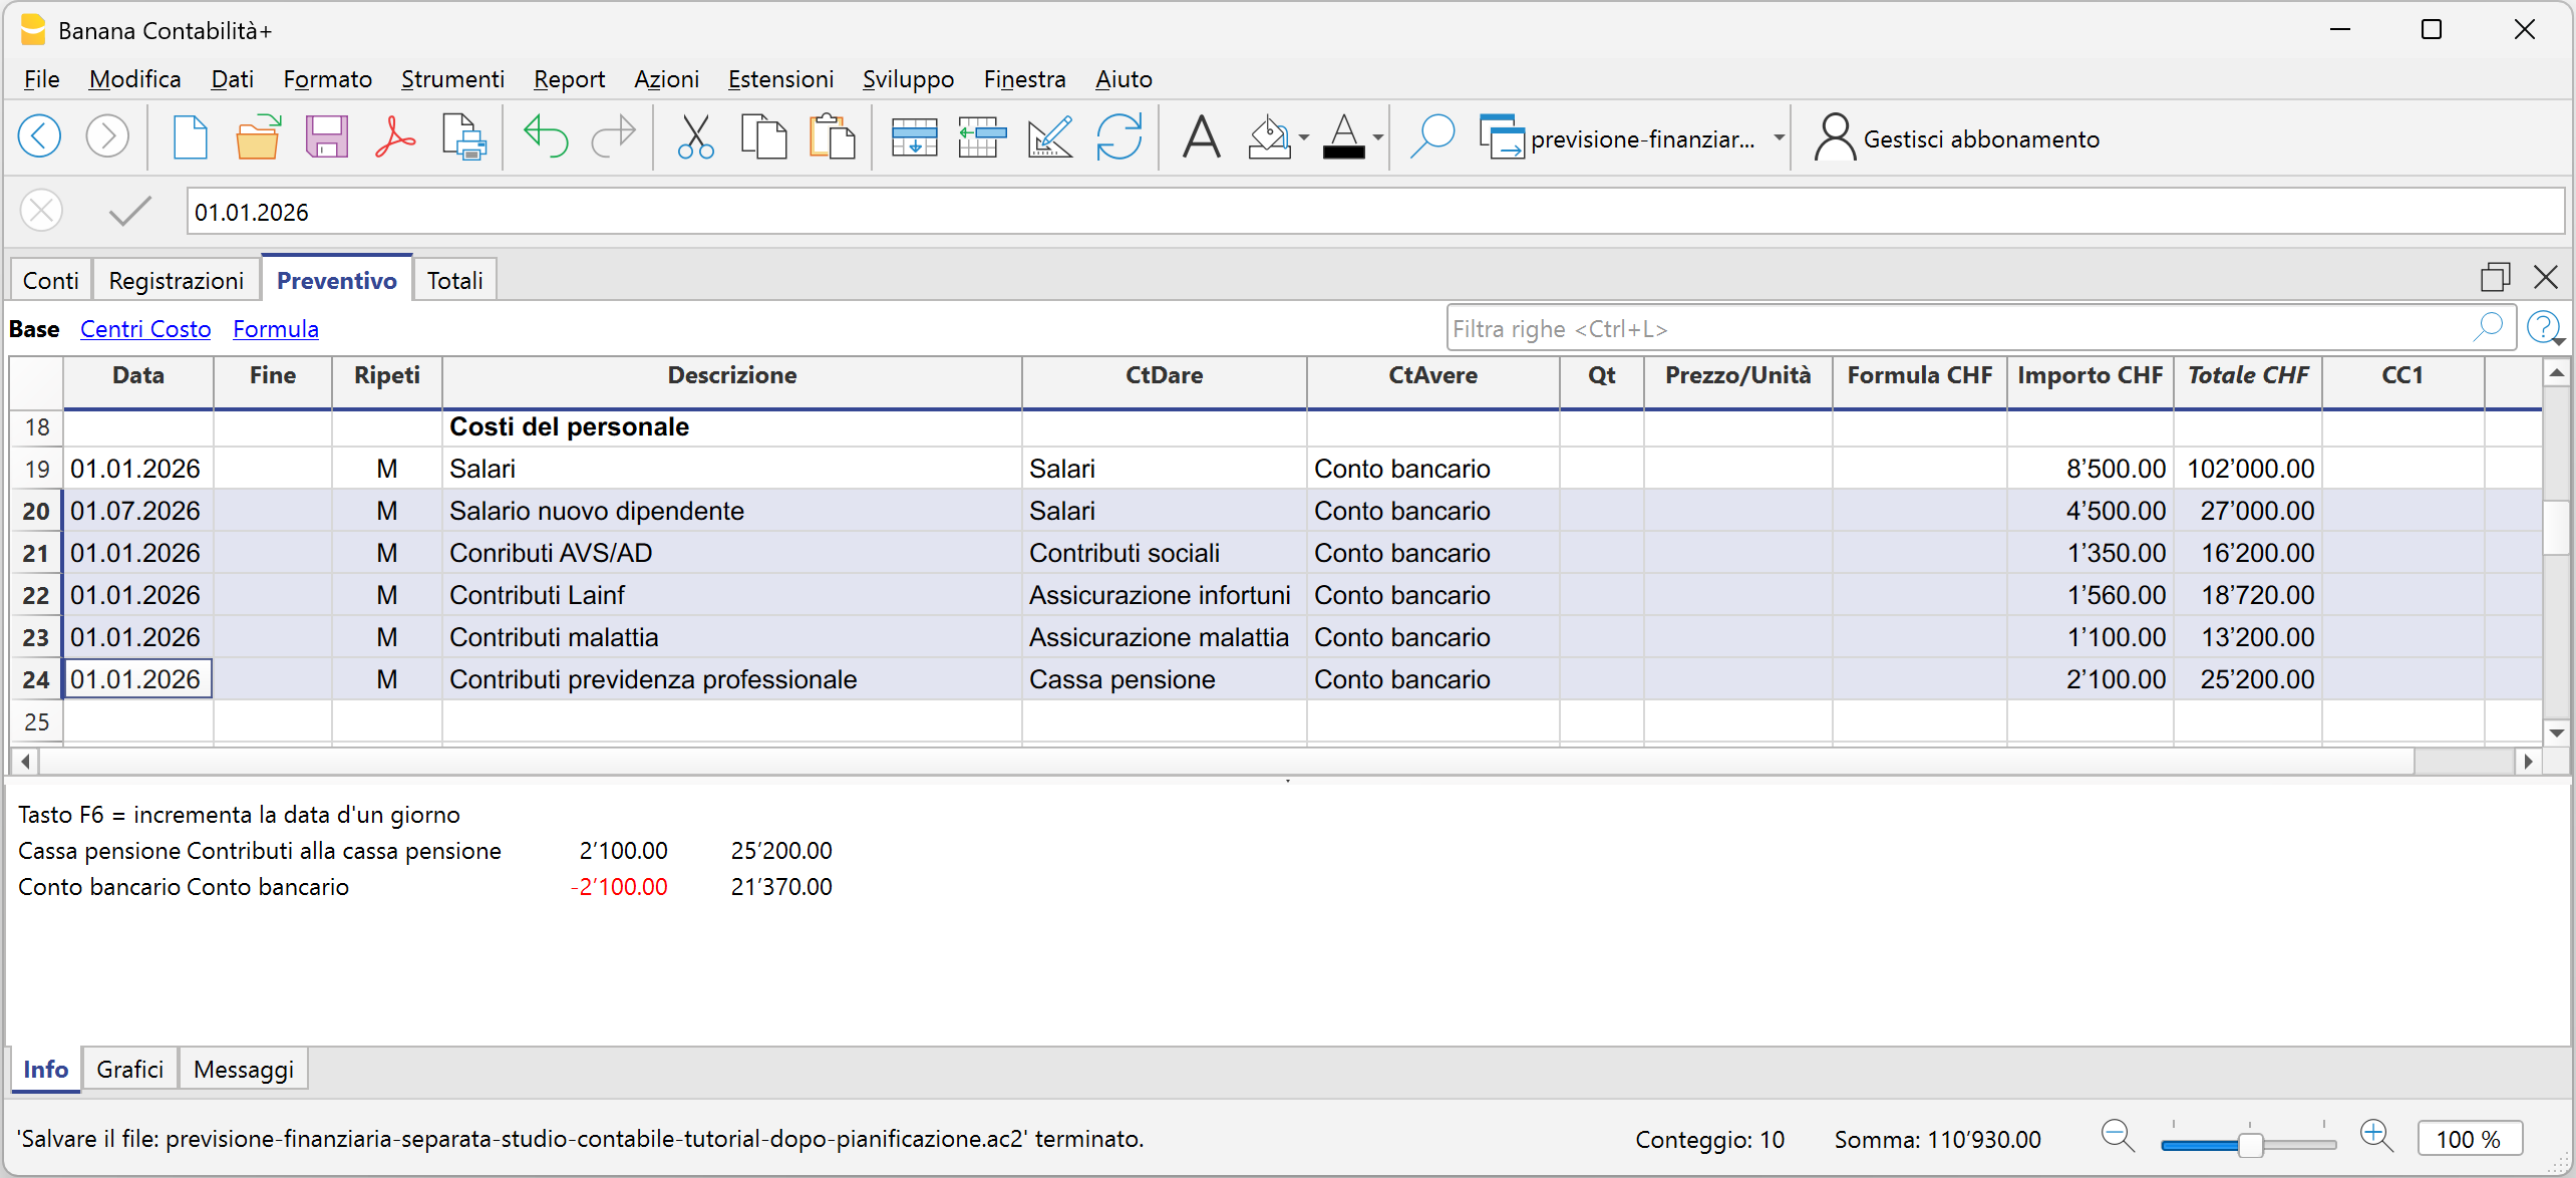
Ipotesi: investimento in nuovo hardware finanziato con un prestito bancario
Supponiamo di pianificare l'acquisto di nuovo hardware per CHF 10'000, finanziato tramite un prestito bancario con un tasso d'interesse del 2.10%.
Nella tabella Preventivo vengono inserite le registrazioni previsionali relative all'investimento e al finanziamento, indicando la data prevista dell'operazione, nell'esempio 01.08.2026.
Per completare la previsione vengono inoltre considerati gli interessi sul finanziamento. Al 31.12 è possibile utilizzare una formula o una variabile per calcolare gli interessi relativi ai cinque mesi da agosto a dicembre e registrare il relativo costo previsto.
In questo modo è possibile valutare contemporaneamente l'impatto dell'operazione sugli investimenti, sull'indebitamento, sugli interessi, sulla liquidità e sul risultato d'esercizio.

Effetti delle ipotesi nei report previsionali
I dati inseriti nella tabella Preventivo possono essere utilizzati per ottenere i principali report economici, finanziari e patrimoniali previsionali.
Dal menu Report > Bilancio abbellito con gruppi, nella sezione relativa ai conti puoi attivare Bilancio e Conto economico e, nella sezione Colonne, selezionare i dati del Preventivo.
Puoi così ottenere lo Stato patrimoniale previsionale e il Conto economico previsionale e verificare gli effetti delle ipotesi inserite nella pianificazione.
Nell'esempio, tutte le variazioni previsionali ipotizzate, aumento del 10% delle vendite, assunzione di un nuovo dipendente e investimento finanziato con un prestito bancario, modificano i risultati della pianificazione rispetto a quelli previsti inizialmente. I relativi effetti si riflettono sullo Stato patrimoniale e sul Conto economico, determinando nuovi valori previsti per la liquidità e l'utile d'esercizio.
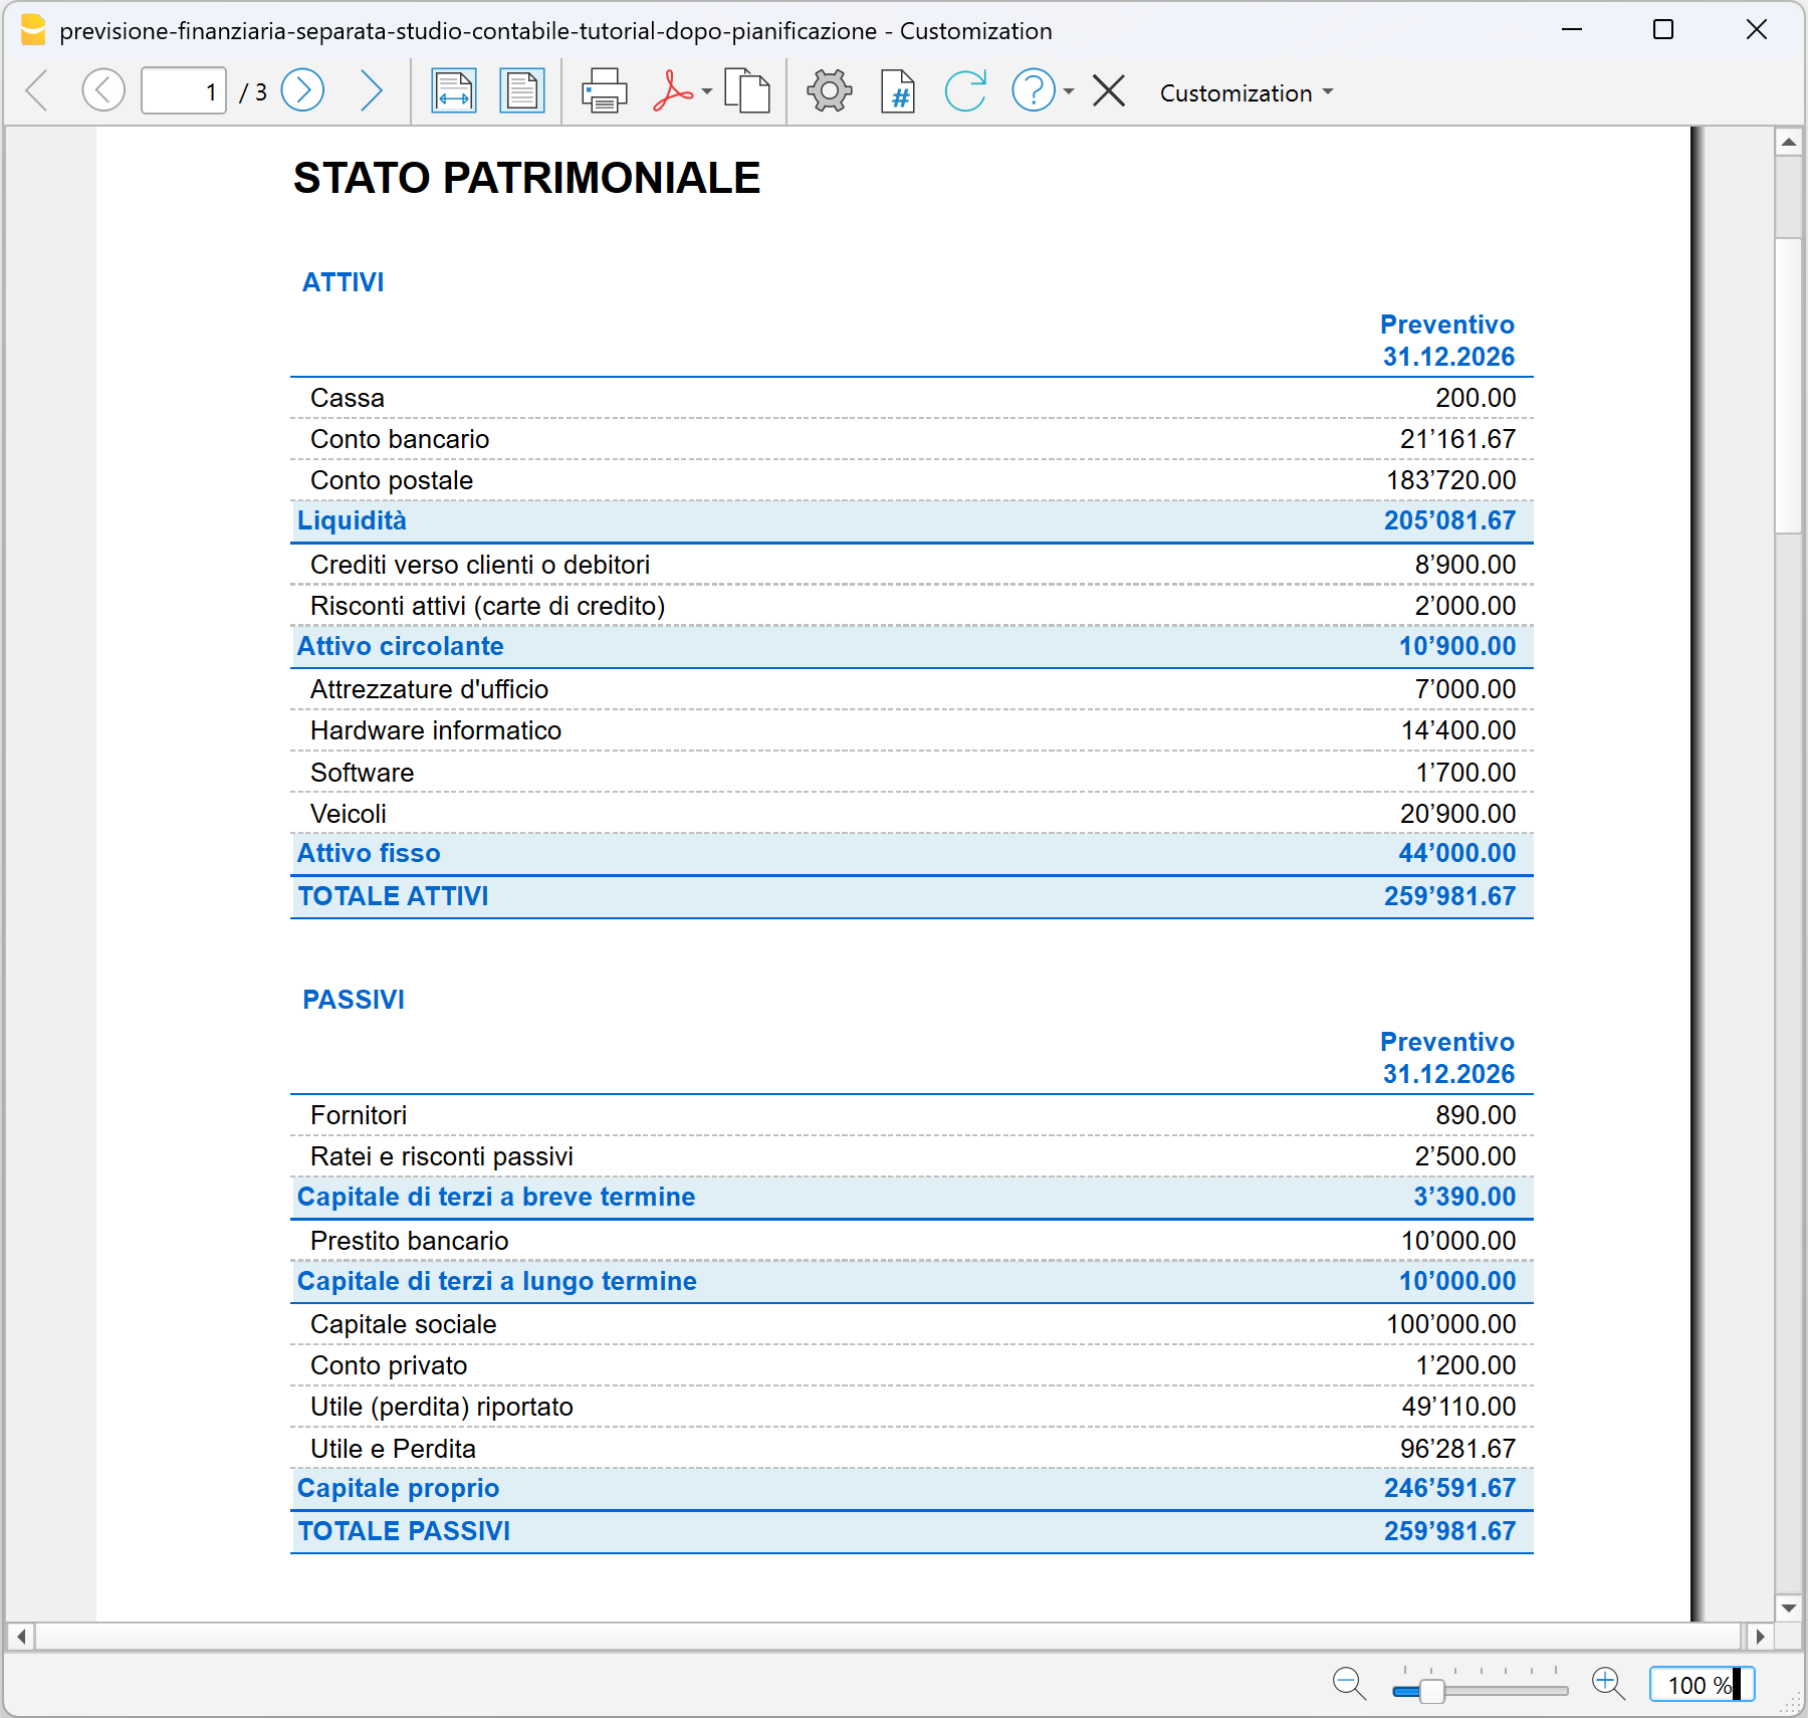
Nello stesso scenario, il Conto economico previsionale permette di confrontare i ricavi e l'utile previsto con quelli della pianificazione di base.
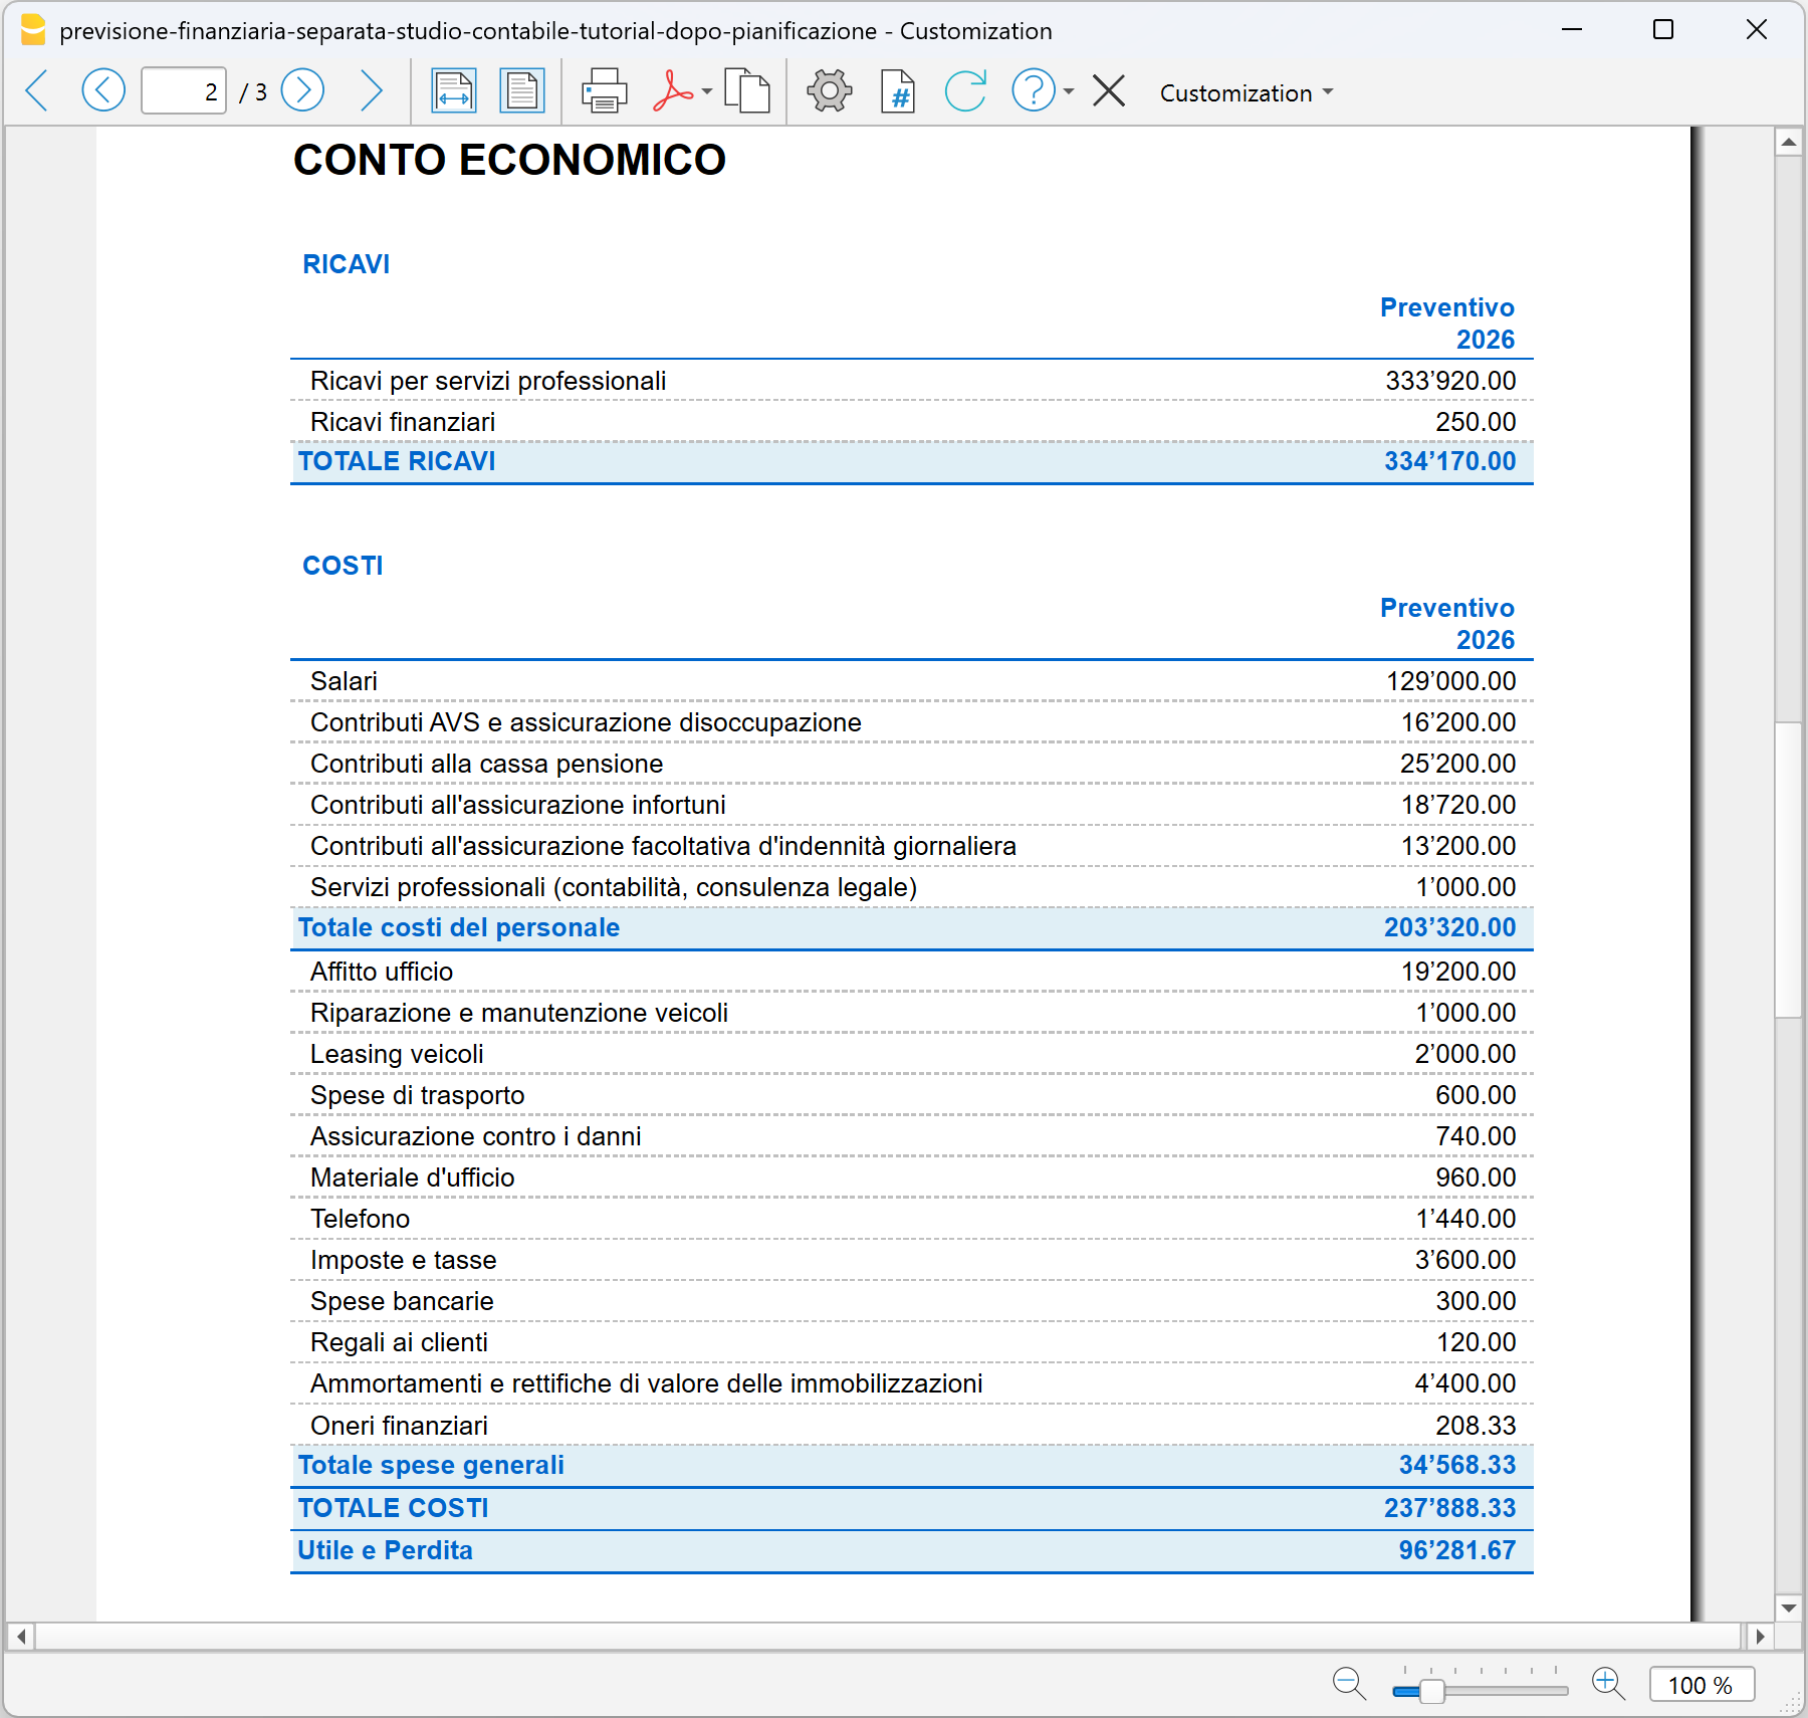
Proiezioni pluriennali
Con Banana Contabilità puoi estendere la pianificazione su più esercizi e creare proiezioni pluriennali.
Per impostare una pianificazione pluriennale, nella tabella Preventivo occorre inserire il movimento previsionale per ciascun anno della pianificazione. Per ogni movimento vengono indicate la relativa data di inizio e di fine periodo, fino a raggiungere la data finale prevista dalla pianificazione.
Gli importi possono essere modificati di anno in anno per tenere conto delle variazioni previste. Ad esempio, puoi prevedere un aumento dei ricavi, una variazione dei costi, nuovi investimenti o una diversa evoluzione dei finanziamenti.
Una volta inserite le previsioni per i diversi esercizi, puoi ottenere report pluriennali e analizzare, anno per anno, l'evoluzione prevista del Conto economico, dello Stato patrimoniale, della liquidità, degli investimenti, dei finanziamenti e dell'indebitamento.
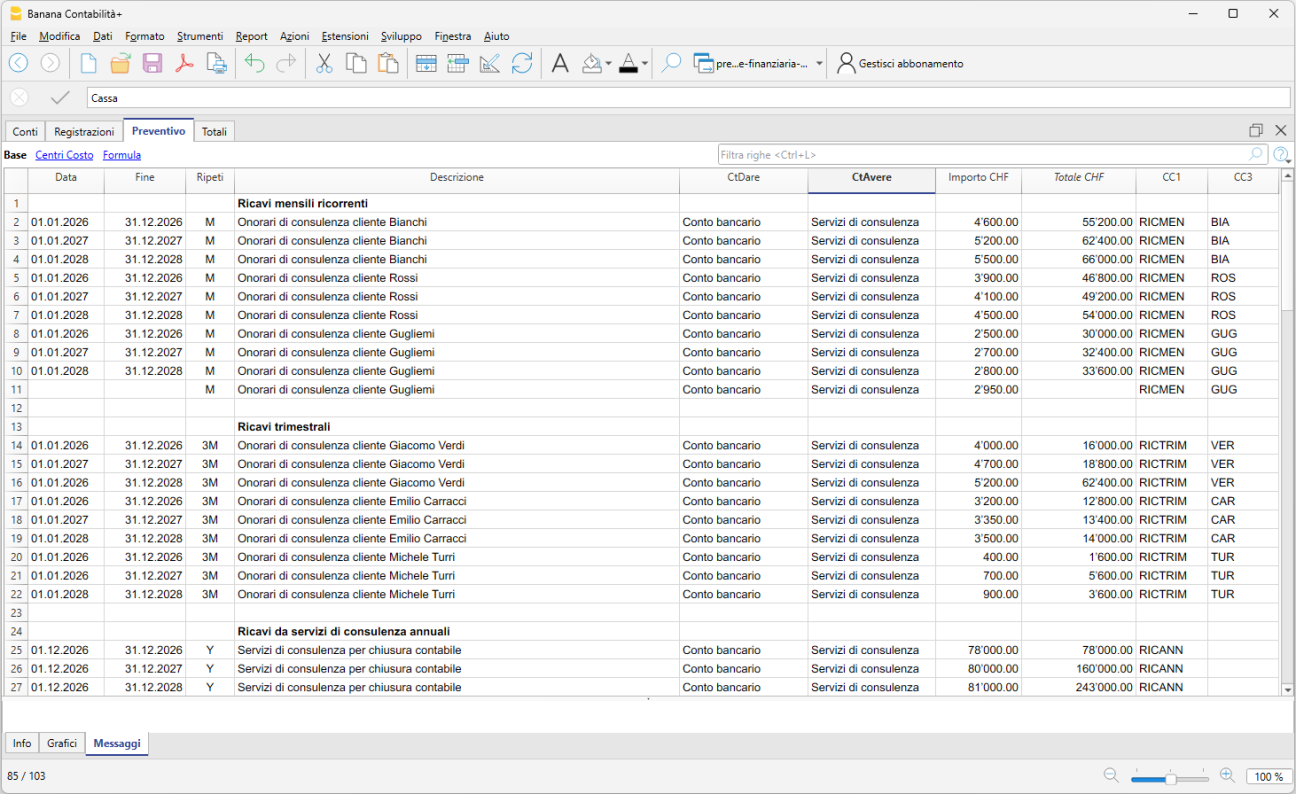
Analizzare i risultati della pianificazione
Una volta completata la pianificazione, puoi analizzare i risultati per l'intero periodo oppure suddividerli per anno. Questo permette di confrontare l'evoluzione prevista della situazione patrimoniale e del Conto economico nel corso di più esercizi.
Per visualizzare e stampare i report:
- dal menu Report > Bilancio abbellito con gruppi
- nella sezione Intestazione e piè di pagina, inserisci l'intestazione della pianificazione
- nella sezione Colonne, attiva la voce Preventivo, sia per il Bilancio sia per il Conto economico
- nella sezione Periodo, seleziona Tutto il periodo
- nella sezione Suddivisione, seleziona Anno
- fai clic su OK.
Esempio di pianificazione pluriennale per lo Stato patrimoniale
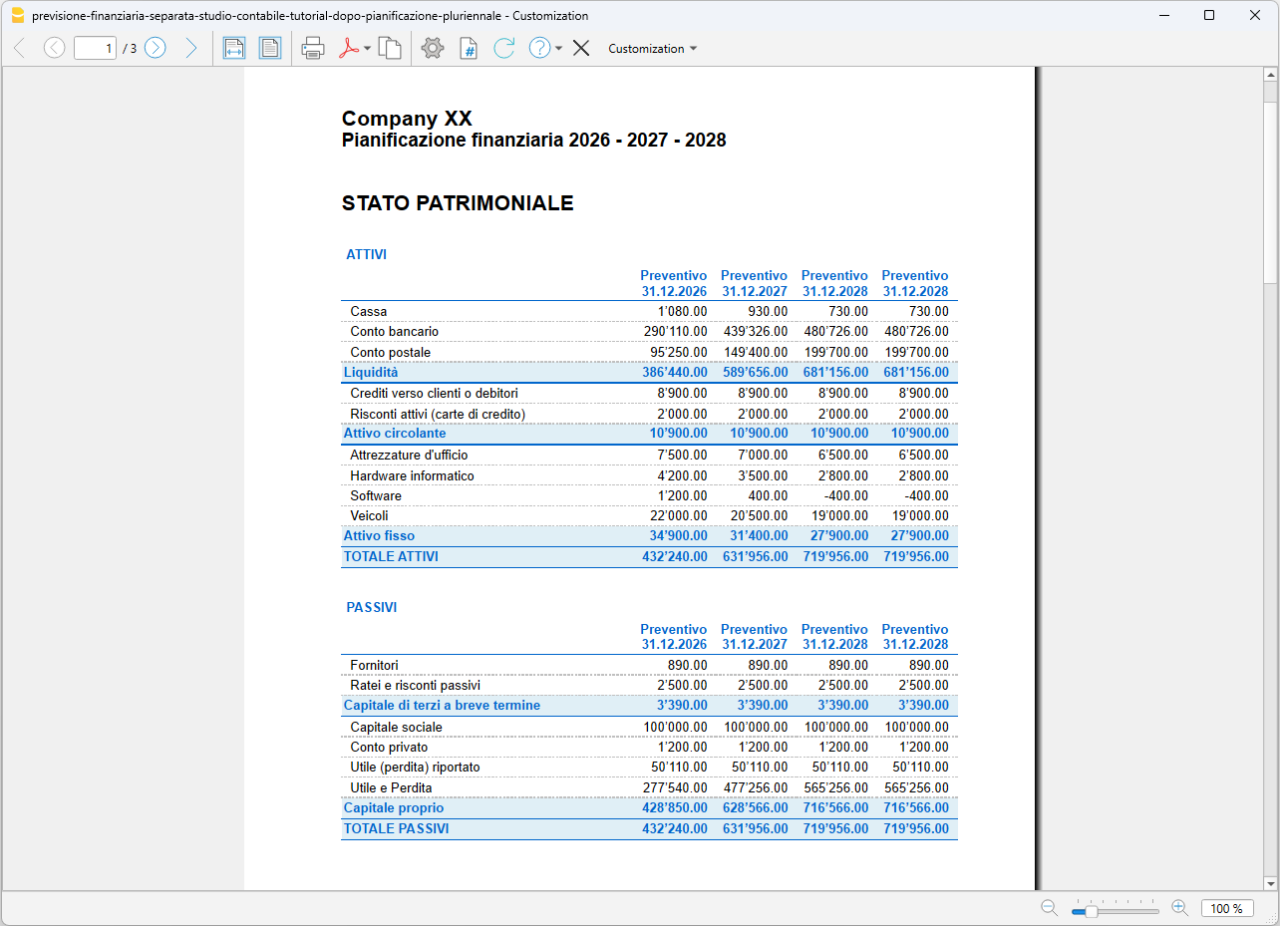
Esempio di pianificazione pluriennale per il Conto economico
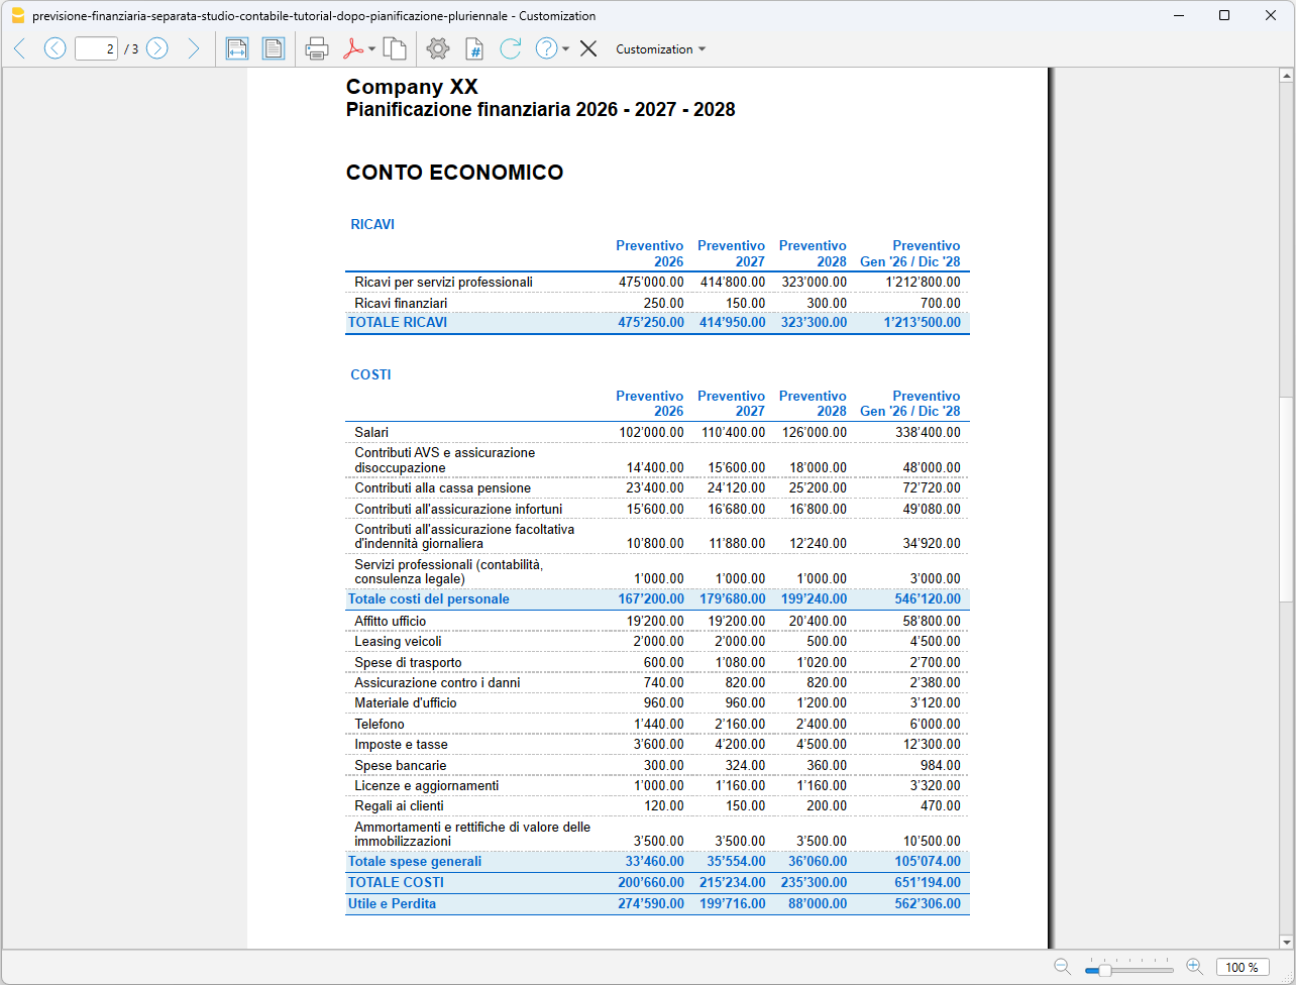
In particolare, puoi verificare:
- se la liquidità prevista è sufficiente durante il periodo di pianificazione
- come evolvono ricavi, costi e risultato d'esercizio
- l'impatto degli investimenti sulla liquidità e sulla situazione patrimoniale
- l'evoluzione dei finanziamenti e dell'indebitamento
- come cambia il patrimonio netto
- se le ipotesi formulate risultano economicamente e finanziariamente sostenibili.
Modificando le ipotesi e le registrazioni nella tabella Preventivo, Banana ricalcola automaticamente i risultati della pianificazione. Puoi così confrontare scenari alternativi e valutarne gli effetti sulla liquidità, sul risultato d'esercizio e sulla situazione patrimoniale, utilizzando i risultati previsionali come supporto alle decisioni aziendali.
Business Templates Switzerland with VAT
Our VAT management templates are included for free in the Banana Accounting Plus program.
The chart of accounts is based on the SME system (Swiss SME chart of accounts - Sterchi, Mattle, Helbing), compliant with the Swiss Code of Obligations (articles 957-963b CO).
VAT Features
All VAT templates include the necessary columns and functions to manage VAT. Calculations and all reports are automated.
To record VAT, simply enter the VAT code in the transaction. The VAT codes table is predefined and updated according to the new 2024 VAT regulations.
At the end of the period, based on transactions with VAT codes, the program calculates the VAT Summary by account, code, and percentage. It generates a paper facsimile of the VAT Report and the XML file for submitting VAT data to the AFC.
For VAT management with the new rates, you can find detailed information on the VAT Management page.
Some features require a subscription to the Advanced plan of Banana Accounting Plus, such as generating the VAT Report facsimile or XML file, using the new Rules, Filter, and Temporary Row Sorting functions. See all features of the Advanced plan.
VAT Accounts in Banana Accounting
The liabilities section includes two specific VAT accounts:
- Account 2201 VAT Report (corresponding to the automatic VAT account). Already configured.
- Account 2200 VAT Due (corresponding to the VAT Treasury account).
However, it is possible to set specific VAT accounts in assets and liabilities, but at the end of the period, various entries are needed to reverse the previous VAT and VAT due into the VAT Treasury account. Therefore, it is recommended to use the default VAT account, **2201 VAT Report**. More details can be found on the page Setting Up VAT Accounts.
Chart of Accounts with VAT on a Cash Basis
The templates for cash-based VAT have customer and supplier sub-ledgers set as Cost and Profit Centers (CC3). VAT is calculated by entering the VAT code at the time of payment and receipt of invoices, with counterpart accounts always being revenue or expense accounts.
Chart of Accounts with VAT on an Accrual Basis
The accrual-based VAT accounting templates have customer and supplier sub-ledgers linked to the balance sheet. All sub-ledger accounts appear in reports and balance sheets. In this case, VAT is calculated by entering the VAT code when issuing an invoice to the customer or receiving an invoice from the supplier.
VAT and Multi-Currency
Among the VAT templates, you can choose models that also manage foreign currencies with VAT.
The chart of accounts includes accounts for exchange rate differences, set in the File > File Properties menu. These templates include the Exchange Rates table, where foreign currencies are set with reference to the base currency, along with exchange rates and opening rates. In the Transactions table, there are columns for viewing amounts in both foreign currency and converted national currency, as well as a column that retrieves the exchange rate entered in the Exchange Rates table.
Company | Cash Manager | VAT
In this article
Company | Cash Manager | VAT
Company | Cash Manager | VAT
Model for managing the cash register of a small business with VAT management. You can insert links to cash receipts in PDF format to keep everything perfectly organized and always accessible with a click. Balances are always updated and visible at any time. Open the model from our WebApp or from the program and save the file onto your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
To manage cash inflows and outflows of a small business. The file can also complement the main accounting file: all cash transactions are recorded separately, and at the end of each quarter (or any chosen period), the totals of categories and accounts are imported into the main accounting file.
Entering VAT codes allows VAT amounts to be automatically recorded in the VAT account.
Create your file
- Open the template with the Banana Accounting Plus WebApp
- Using the command File > File Properties, set the period, your company name, and the base currency (you can create budgets and accounting in any currency).
- Using the command File > Save As, save the file. It is helpful to include the company name and year in the filename. For example, "Cash_Rossi-SA-20xx.ac2".
WARNING: If you close the browser without saving, you will lose the entered data. Always save the file on your computer.
To reopen the saved file, click on File > Open.
Also, see Organizing accounting files locally, on a network, and in the cloud.
More information is available on the following pages:
Template preview
Shop XXX
Accounting 2024
Basic Currency: CHF
Cash Manager with VAT/Sales tax
| Group | Account | Description | Sum In |
|---|---|---|---|
| 1000 | Cash on hand | ||
| Group | Category | Description | Sum In |
|---|---|---|---|
| OPERATING RESULT | |||
| INCOME | |||
| 3000 | Income from sales | 3 | |
| 3090 | Discounts on sales | 3 | |
| 3400 | Income from services | 3 | |
| 3620 | Various Income | 3 | |
| 3809 | VAT flat tax rate | 3 | |
| 3 | TOTAL INCOME | 00 | |
| EXPENSES | |||
| 4000 | Purchases | 4 | |
| 4090 | Discounts | 4 | |
| 5000 | Salaries | 4 | |
| 5070 | Social contributions | 4 | |
| 5482 | Representation expenses | 4 | |
| 6000 | Rent | 4 | |
| 6040 | Cleaning expenses | 4 | |
| 6100 | Upkeep | 4 | |
| 6210 | Fuel | 4 | |
| 6220 | Insurances | 4 | |
| 6264 | Rental charges | 4 | |
| 6400 | Electricity | 4 | |
| 6410 | Gas | 4 | |
| 6420 | Heating | 4 | |
| 6430 | Water | 4 | |
| 6500 | Office supplies | 4 | |
| 6510 | Telephone & fax | 4 | |
| 6640 | Transportation | 4 | |
| 6840 | Postage | 4 | |
| 2200 | VAT due | 4 | |
| 2201 | Automatic VAT | 4 | |
| 4 | TOTAL EXPENSES | 00 | |
| 00 | TOTAL OPERATING RESULT | ||
| VAT Code | Description | %VAT |
|---|---|---|
| Explanations | ||
| V = Sales (200) | ||
| VS = Discount sales and services (235) | ||
| B = Acquisition tax (38x) | ||
| M = Expenses for material and services (400) | ||
| I = Investments and other operating expenses (405) | ||
| K = Corrections (410, 415, 420) | ||
| Z = Not considered (910) | ||
| VAT codes information (do not modify) | ||
| id=vatcodes-che-2024.20230614 | ||
| Last update: 14.06.2023 | ||
| VAT Due | ||
| V0 | Exempt services (220) | |
| V0-E | Export services abroad (221) | |
| V0-T | Transfers in the reporting procedure (225) | |
| V0-N | Non-taxable services (230) | |
| Decrease of income from services, see discounts | ||
| V0-D | Various (280) | |
| V77 | Sales and services 7.7% | 7.70 |
| V81 | Sales and services 8.1% | 8.10 |
| V77-B | Sales and services 7.7% (chosen) | 7.70 |
| V81-B | Sales and services 8.1% (chosen) | 8.10 |
| V25-N | Sales and services 2.5% | 2.50 |
| V26 | Sales and services 2.6% | 2.60 |
| V37 | Sales and services 3.7% | 3.70 |
| V38 | Sales and services 3.8% | 3.80 |
| VS77 | Discount Sales and services 7.7% | 7.70 |
| VS81 | Discount Sales and services 8.1% | 8.10 |
| VS25-N | Discount Sales and services 2.5% | 2.50 |
| VS26 | Discount Sales and services 2.6% | 2.60 |
| VS37 | Discount Sales and services 3.7% | 3.70 |
| VS38 | Discount Sales and services 3.8% | 3.80 |
| Taxable turnover (299) | ||
| F1 | 1. Flat tax rate 2024 | |
| F2 | 2. Flat tax rate 2024 | |
| FS1 | Discount Sales and services 1. Flat tax rate 2024 | |
| FS2 | Discount Sales and services 2. Flat tax rate 2024 | |
| F3 | 1. Flat tax rate 2018 | |
| F4 | 2. Flat tax rate 2018 | |
| FS3 | Discount Sales and services 1. Flat tax rate 2018 | |
| FS4 | Discount Sales and services 2. Flat tax rate 2018 | |
| Total Flat tax rate (322-333) | ||
| B77 | Acquisition tax 7.7% (With VAT/Sales tax) | 7.70 |
| B77-1 | Acquisition tax 7.7% (Without VAT/Sales tax) | 7.70 |
| B77-2 | Acquisition tax 7.7% (VAT/Sales tax amount) | 7.70 |
| B81 | Acquisition tax 8.1% (With VAT/Sales tax) | 8.10 |
| B81-1 | Acquisition tax 8.1% (Without VAT/Sales tax) | 8.10 |
| B81-2 | Acquisition tax 8.1% (VAT/Sales tax amount) | 8.10 |
| Total Tax on purchases (382-383) | ||
| Total VAT Due (399) | ||
| Recoverable VAT | ||
| M0 | Exempt material- and service expenses | |
| I0 | Exempt investment and operating expenses | |
| M77 | Purchase of material and services 7.7% (With VAT/Sales tax) | 7.70 |
| M77-1 | Purchase of material and services 7.7% (Without VAT/Sales tax) | 7.70 |
| M77-2 | Purchase of material and services 7.7% (VAT/Sales tax amount) | 7.70 |
| M81 | Purchase of material and services 8.1% (With VAT/Sales tax) | 8.10 |
| M81-1 | Purchase of material and services 8.1% (Without VAT/Sales tax) | 8.10 |
| M81-2 | Purchase of material and services 8.1% (VAT/Sales tax amount) | 8.10 |
| M25 | Purchase of material and services 2.5% | 2.50 |
| M26 | Purchase of material and services 2.6% | 2.60 |
| M37 | Purchase of material and services 3.7% | 3.70 |
| M38 | Purchase of material and services 3.8% | 3.80 |
| Investment and operating expenses | ||
| I77 | Investment and operating expenses 7.7% | 7.70 |
| I77-1 | Investment and operating expenses 7.7% (Without VAT/Sales tax) | 7.70 |
| I77-2 | Investment and operating expenses 7.7% (VAT/Sales tax amount) | 7.70 |
| I81 | Investment and operating expenses 8.1% | 8.10 |
| I81-1 | Investment and operating expenses 8.1% (Without VAT/Sales tax) | 8.10 |
| I81-2 | Investment and operating expenses 8.1% (VAT/Sales tax amount) | 8.10 |
| I25 | Investment and operating expenses 2.5% | 2.50 |
| I26 | Investment and operating expenses 2.6% | 2.60 |
| I37 | Investment and operating expenses 3.7% | 3.70 |
| I38 | Investment and operating expenses 3.8% | 3.80 |
| Corrections and adjustments | ||
| K77-A | Subsequent adjustment of prior tax 7.7% (410) | 7.70 |
| K81-A | Subsequent adjustment of prior tax 8.1 % (410) | 8.10 |
| K77-B | Corrections of prior tax 7.7% (415) | 7.70 |
| K81-B | Corrections of prior tax 8.1% (415) | 8.10 |
| K77-C | Reductions of the deduction of prior tax 7.7% (420) | 7.70 |
| K81-C | Reductions of the deduction of prior tax 8.1% (420) | 8.10 |
| F1050 | Tax computation according to form Nr. 1050 | |
| F1055 | Tax computation according to form Nr. 1055 | |
| Total Recoverable VAT (479) | ||
| Total VAT payable (500) or VAT credit (510) | ||
| Other financial flows | ||
| Z0-A | Subsidies, tourist taxes collected by the tourism offices, contributions to the institutions responsible for the elimination of waste and for the supply of water (let. a - c) | |
| Z0 | Gifts, dividends, compensation for damages etc. | |
| Not considered | ||
| Final total for control | ||
Cash Manager for professional practice | VAT
In this article
Cash Manager for professional practice | VAT
Cash Manager for professional practice | VAT
Model for managing cash inflows and outflows, including the new 2024 VAT management. You can attach scanned PDF receipts directly to the transaction. Open the model from our WebApp or from the program and save the file on your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
The model provides a simple and fast way to manage cash transactions. All data is always well-organized, and for each expense entry, you can attach a PDF receipt, ensuring complete and documented control of expenses.
You can periodically integrate cash data into the accounting file to maintain a complete bookkeeping system, allowing you to generate full VAT reports exclusively within the accounting file.
Automated professional reports provide all the details of income and expenses for each account and category.
Create your file
- Open the template with the Banana Accounting Plus WebApp
- Using the command File > File Properties, set the period, your company name, and the base currency (you can create budgets and bookkeeping in any currency).
- Using the command File > Save As, save the file. It is useful to include the company name and year in the filename. For example, "Cash_Rossi-SA-20xx.ac2".
WARNING: If you close the browser without saving, you will lose the entered data. Always save the file on your computer.
To reopen the saved file, click on File > Open.
Also, see Organizing accounting files locally, on a network, and in the cloud.
More information is available on the following pages:
Income / Expense accounting with descriptive accounts and categories
In this article
Income / Expense accounting with descriptive accounts and categories
Income / Expense accounting with descriptive accounts and categories
Ideal template for those who have no accounting knowledge and need to manage their company's bookkeeping. The accounting data is entered into tables with a column structure, similar to Excel. To make the work even more intuitive, the accounts and the income and expense categories are descriptive rather than numerical. Calculations are performed automatically, with no need to create formulas or filters, and you get professional results such as the balance sheet, the income and expense report, and the determination of the financial result. Open the template with our WebApp, or download the file from the program and save it under a new name.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open tutorial in WebAppCompany | Income & Expense Accounting | VAT
In this article
Company | Income & Expense Accounting | VAT
Company | Income & Expense Accounting | VAT
This template is designed to allow quick and easy recording of all your company's income and expenses, even without specific accounting knowledge. Thanks to an intuitive interface, data entry is simple and accessible to everyone, facilitating clear and comprehensive financial management. With just a few clicks, you can print balance sheets and income and expense reports. You can also manage cash flow forecasting and track your business performance. Open the template from our WebApp or the program and save the file to your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
This template, while having a simple and essential setup, still allows you to manage accounting professionally.
- You can customize accounts and categories at any time, adapting them to your specific needs.
- The Accounts and Categories tables provide an immediate overview of the balances for each account and category, allowing you to maintain full control of your financial situation.
- By setting up the customer ledger, you have the possibility to issue invoices to your customers with the added advantage of having them automatically recorded in accounting.
- The VAT Codes table is updated with the new 2024 VAT rates.
- To speed up the entry of transactions, you can use bank data import with Rules: for each imported transaction, you enter a text (Rule) completing all other registration elements (contra account, VAT code, cost center...); in subsequent imports, the program automatically completes the registration whenever it finds the key text in the import entry, significantly reducing work time and minimizing errors.
- If you need to create invoices, simply set up the CC3 profit center in the Accounts table.
Some features require a subscription to the Advanced plan of Banana Accounting Plus, such as generating the facsimile or XML file of the VAT Report, using the new Rules, Filter, and Temporary Sort functions. See all the features of the Advanced plan.
Create your file
- Open the template with the Banana Accounting Plus WebApp
- Using the command File > File Properties, set the period, your company name, and the base currency (you can create budgets and bookkeeping in any currency).
- Using the command File > Save As, save the file. It is useful to include the company name and year in the filename. For example, "Cash_Rossi-SA-20xx.ac2".
WARNING: If you close the browser without saving, you will lose the entered data. Always save the file on your computer.
To reopen the saved file, click on File > Open.
Also, see Organizing accounting files locally, on a network, and in the cloud.
More information is available on the following pages:
Template preview
Company XX
Accounting 2024
Basic Currency: CHF
Income & Expense accounting with VAT/Sales tax
| Group | Account | Description | Sum In |
|---|---|---|---|
| ESTATE | |||
| 1000 | Cash on hand | 1 | |
| 1010 | Post office current account | 1 | |
| 1020 | Bank account | 1 | |
| 1100 | Credits | 1 | |
| 1176 | Withholding tax | 1 | |
| 1510 | Office furniture and equipment | 1 | |
| 1520 | Office machinery, information and communication technology | 1 | |
| 2000 | Current liabilities short term | 1 | |
| 2200 | VAT Due | 1 | |
| 2201 | VAT according to VAT report | 1 | |
| 2400 | Liabilities long term | 1 | |
| 1 | NET ESTATE | ||
| Group | Category | Description | Sum In |
|---|---|---|---|
| OPERATING RESULT | |||
| INCOME | |||
| 3000 | Income from sales | 3 | |
| 3090 | Discounts | 3 | |
| 3400 | Earnings from services rendered | 3 | |
| 3680 | Other income | 3 | |
| 3809 | VAT flat tax rate | 3 | |
| 3 | TOTAL INCOME | 00 | |
| EXPENSES | |||
| 4000 | Purchase goods for resale | 4 | |
| 4090 | Discounts | 4 | |
| 5000 | Salaries | 4 | |
| 5700 | Contribution to old age insurance and unemployment | 4 | |
| 5820 | Travel and entertainment expenses effective | 4 | |
| 6000 | Rental | 4 | |
| 6100 | Cost of maintenance | 4 | |
| 6210 | Gas and oil expense | 4 | |
| 6264 | Vehicle rentals | 4 | |
| 6300 | Insurances | 4 | |
| 6402 | Electricity | 4 | |
| 6410 | Heating expenses | 4 | |
| 6430 | Water | 4 | |
| 6460 | Garbage | 4 | |
| 6500 | Office supplies | 4 | |
| 6510 | Telephone | 4 | |
| 6513 | Shipping expenses | 4 | |
| 6640 | Travel expenses | 4 | |
| 6800 | Depreciation and value adjustments of fixed assets | 4 | |
| 6900 | Financial costs | 4 | |
| 8900 | Taxes | 4 | |
| 4 | TOTAL EXPENSES | 00 | |
| 00 | OPERATING RESULT | ||
| VAT Code | Description | %VAT |
|---|---|---|
| Explanations | ||
| V = Sales (200) | ||
| VS = Discount sales and services (235) | ||
| B = Acquisition tax (38x) | ||
| M = Expenses for material and services (400) | ||
| I = Investments and other operating expenses (405) | ||
| K = Corrections (410, 415, 420) | ||
| Z = Not considered (910) | ||
| VAT codes information (do not modify) | ||
| id=vatcodes-che-2024.20230614 | ||
| Last update: 14.06.2023 | ||
| VAT Due | ||
| V0 | Exempt services (220) | |
| V0-E | Export services abroad (221) | |
| V0-T | Transfers in the reporting procedure (225) | |
| V0-N | Non-taxable services (230) | |
| Decrease of income from services, see discounts | ||
| V0-D | Various (280) | |
| V77 | Sales and services 7.7% | 7.70 |
| V81 | Sales and services 8.1% | 8.10 |
| V77-B | Sales and services 7.7% (chosen) | 7.70 |
| V81-B | Sales and services 8.1% (chosen) | 8.10 |
| V25-N | Sales and services 2.5% | 2.50 |
| V26 | Sales and services 2.6% | 2.60 |
| V37 | Sales and services 3.7% | 3.70 |
| V38 | Sales and services 3.8% | 3.80 |
| VS77 | Discount Sales and services 7.7% | 7.70 |
| VS81 | Discount Sales and services 8.1% | 8.10 |
| VS25-N | Discount Sales and services 2.5% | 2.50 |
| VS26 | Discount Sales and services 2.6% | 2.60 |
| VS37 | Discount Sales and services 3.7% | 3.70 |
| VS38 | Discount Sales and services 3.8% | 3.80 |
| Taxable turnover (299) | ||
| F1 | 1. Flat tax rate 2024 | |
| F2 | 2. Flat tax rate 2024 | |
| FS1 | Discount Sales and services 1. Flat tax rate 2024 | |
| FS2 | Discount Sales and services 2. Flat tax rate 2024 | |
| F3 | 1. Flat tax rate 2018 | |
| F4 | 2. Flat tax rate 2018 | |
| FS3 | Discount Sales and services 1. Flat tax rate 2018 | |
| FS4 | Discount Sales and services 2. Flat tax rate 2018 | |
| Total Flat tax rate (322-333) | ||
| B77 | Acquisition tax 7.7% (With VAT/Sales tax) | 7.70 |
| B77-1 | Acquisition tax 7.7% (Without VAT/Sales tax) | 7.70 |
| B77-2 | Acquisition tax 7.7% (VAT/Sales tax amount) | 7.70 |
| B81 | Acquisition tax 8.1% (With VAT/Sales tax) | 8.10 |
| B81-1 | Acquisition tax 8.1% (Without VAT/Sales tax) | 8.10 |
| B81-2 | Acquisition tax 8.1% (VAT/Sales tax amount) | 8.10 |
| Total Tax on purchases (382-383) | ||
| Total VAT Due (399) | ||
| Recoverable VAT | ||
| M0 | Exempt material- and service expenses | |
| I0 | Exempt investment and operating expenses | |
| M77 | Purchase of material and services 7.7% (With VAT/Sales tax) | 7.70 |
| M77-1 | Purchase of material and services 7.7% (Without VAT/Sales tax) | 7.70 |
| M77-2 | Purchase of material and services 7.7% (VAT/Sales tax amount) | 7.70 |
| M81 | Purchase of material and services 8.1% (With VAT/Sales tax) | 8.10 |
| M81-1 | Purchase of material and services 8.1% (Without VAT/Sales tax) | 8.10 |
| M81-2 | Purchase of material and services 8.1% (VAT/Sales tax amount) | 8.10 |
| M25 | Purchase of material and services 2.5% | 2.50 |
| M26 | Purchase of material and services 2.6% | 2.60 |
| M37 | Purchase of material and services 3.7% | 3.70 |
| M38 | Purchase of material and services 3.8% | 3.80 |
| Investment and operating expenses | ||
| I77 | Investment and operating expenses 7.7% | 7.70 |
| I77-1 | Investment and operating expenses 7.7% (Without VAT/Sales tax) | 7.70 |
| I77-2 | Investment and operating expenses 7.7% (VAT/Sales tax amount) | 7.70 |
| I81 | Investment and operating expenses 8.1% | 8.10 |
| I81-1 | Investment and operating expenses 8.1% (Without VAT/Sales tax) | 8.10 |
| I81-2 | Investment and operating expenses 8.1% (VAT/Sales tax amount) | 8.10 |
| I25 | Investment and operating expenses 2.5% | 2.50 |
| I26 | Investment and operating expenses 2.6% | 2.60 |
| I37 | Investment and operating expenses 3.7% | 3.70 |
| I38 | Investment and operating expenses 3.8% | 3.80 |
| Corrections and adjustments | ||
| K77-A | Subsequent adjustment of prior tax 7.7% (410) | 7.70 |
| K81-A | Subsequent adjustment of prior tax 8.1 % (410) | 8.10 |
| K77-B | Corrections of prior tax 7.7% (415) | 7.70 |
| K81-B | Corrections of prior tax 8.1% (415) | 8.10 |
| K77-C | Reductions of the deduction of prior tax 7.7% (420) | 7.70 |
| K81-C | Reductions of the deduction of prior tax 8.1% (420) | 8.10 |
| F1050 | Tax computation according to form Nr. 1050 | |
| F1055 | Tax computation according to form Nr. 1055 | |
| Total Recoverable VAT (479) | ||
| Total VAT payable (500) or VAT credit (510) | ||
| Other financial flows | ||
| Z0-A | Subsidies, tourist taxes collected by the tourism offices, contributions to the institutions responsible for the elimination of waste and for the supply of water (let. a - c) | |
| Z0 | Gifts, dividends, compensation for damages etc. | |
| Not considered | ||
| Final total for control | ||
Company | Customer/Supplier Ledger
In this article
Company | Customer/Supplier Ledger
Company | Customer/Supplier Ledger
The file is a tutorial with a SME chart of accounts and includes sample transactions for business accounting managed based on revenue. The Customer/Supplier Ledger is set up with the total of all accounts reflected in the Customers group from the ledger in the balance sheet. In addition to the use of VAT codes with the rates from 2024, there are also transactions for creating invoices. In Banana Accounting, a simple command is enough to generate and print invoices while simultaneously recording VAT and registering the invoices in the accounting system. Open the tutorial with the Banana Accounting WebApp, or from the program, and save the file to your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open tutorial in WebAppTemplate documentation
The tutorial is based on an Income and Expense accounting system, which is very intuitive and easy to manage. You can use the tutorial to explore many features:
- Create and print invoices for your clients
- Check due dates
- Send reminders
- Manage VAT with the new rates from 2024
- Speed up transaction entry with automatic import and the use of Rules
- Print reports, account statements, journal, and other summaries
Some functions require a subscription to the Advanced plan of Banana Accounting Plus, such as generating a facsimile or XML file of the VAT Report, using new features like Rules, Temporary Row Filtering, and Sorting. See all features of the Advanced plan.
Create your file
- Open the template with the Banana Accounting WebApp
- Using the File > File Properties command, set the period, your company name, and the base currency (you can create a budget and manage accounting in any currency you prefer).
- With the File > Save As command, save the file. It is useful to include your studio name and the year in the file name. For example, "Studio-Rossi-SA-20xx.ac2".
WARNING: If you close the browser without saving, you will lose the entered data. Always save the file on your computer.
In our Documentation, you will find explanations on various topics to help you manage your accounting effectively:
- Videos
- Income/Expense
- Accounts
- Categories
- Transactions
- Swiss VAT Management
- Invoicing
- New Year
- Budget Transactions
- Printing
Self-employed professional | Income & Expense Accounting | VAT
In this article
Self-employed professional | Income & Expense Accounting | VAT
Self-employed professional | Income & Expense Accounting | VAT
Discover the "Income and Expenses for Freelancers with VAT" template in Banana Accounting, designed to simplify accounting management for self-employed professionals.This tool allows you to easily record income, expenses, and calculate VAT, providing a clear overview of your financial situation. Thanks to this template, freelancers and self-employed professionals can meet their tax obligations in an intuitive and accurate way, optimizing the time spent on accounting while maintaining precise control over their business. Generate balance sheets, income and expense reports (both annual and periodic), account statements, and journals. Open the template from our WebApp or directly from the program and save the file on your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
This application technically uses the same mechanism as double-entry accounting but with the advantage that you don't need to know the basics of Debit and Credit, allowing you to manage accounting quickly and easily.
- In the Accounts Table, you will find the accounts to manage your resources (liquidity, equipment, customers...),
- In the Categories Table, you have all income and expenses categorized for each item.
To enter records quickly:
- Import transactions from your e-bank statements, postal accounts, or credit cards.
- Set up Rules to complete imported transactions
- Get reports and professional printouts after each transaction.
If you need to create invoices, simply set up the customer ledger with the CC3, and you will be able to print:
VAT management is simple. Just enter the VAT code for each relevant transaction. The VAT Codes Table is already updated with the new 2024 VAT rates.
Some functions require a subscription to the Advanced plan of Banana Accounting Plus, such as generating the facsimile or XML file of the VAT Report, using new Rules features, Temporary Row Filtering, and Sorting. See all the features of the Advanced plan.
Further details and additional information are available on the following web pages:
Create your file
- Open the template with the Banana Accounting WebApp
- Using the File > File Properties command, set the period, your company name, and the base currency (you can create a budget and manage accounting in any currency you prefer).
- With the File > Save As command, save the file. It is useful to include your studio name and the year in the file name. For example, "Studio-Rossi-SA-20xx.ac2".
WARNING: If you close the browser without saving, you will lose the entered data. Always save the file on your computer.
In our Documentation, you will find explanations on various topics to help you manage your accounting effectively:
- Videos
- Income/Expense
- Accounts
- Categories
- Transactions
- Swiss VAT Management
- Invoicing
- New Year
- Budget Transactions
- Printing
Template preview
Professional Studio XX
Accounting 2024
Basic Currency: CHF
Income & Expense accounting with VAT/Sales tax
| Group | Account | Description | Sum In |
|---|---|---|---|
| ESTATE | |||
| 1000 | Cash | 1 | |
| 1010 | Post office current account | 1 | |
| 1020 | Bank current account | 1 | |
| 1100 | Credits | 1 | |
| 1176 | Withholding tax | 1 | |
| 1510 | Office furniture | 1 | |
| 1520 | Office machines | 1 | |
| 2000 | Current liabilities short term | 1 | |
| 2200 | VAT Due | 1 | |
| 2201 | VAT according to VAT report | 1 | |
| 2400 | Due to banks long-term | 1 | |
| 1 | NET ESTATE |
| Group | Category | Description | Sum In |
|---|---|---|---|
| OPERATING RESULT | |||
| INCOME | |||
| 3400 | Services/Honoraria | 3 | |
| 3407 | Commissions | 3 | |
| 3680 | Various income | 3 | |
| 3809 | VAT flat tax rate | 3 | |
| 3 | TOTAL INCOME | 00 | |
| EXPENSES | |||
| 4090 | Discounts | 4 | |
| 5000 | Salaries employees | 4 | |
| 5700 | Contribution to old age insurance and unemployment | 4 | |
| 5800 | Other personnel expenses | 4 | |
| 6000 | Rental | 4 | |
| 6100 | Cleaning and Upkeep | 4 | |
| 6210 | Fuel | 4 | |
| 6280 | Shipping charges | 4 | |
| 6300 | Insurances | 4 | |
| 6402 | Electricity | 4 | |
| 6410 | Heating expenses | 4 | |
| 6430 | Water | 4 | |
| 6460 | Garbage | 4 | |
| 6500 | Office supplies | 4 | |
| 6510 | Telephone | 4 | |
| 6640 | Transportation | 4 | |
| 6800 | Depreciation and value adjustments of fixed assets | 4 | |
| 6900 | Financial costs | 4 | |
| 8900 | Direct taxes | 4 | |
| 4 | TOTAL EXPENSES | 00 | |
| 00 | TOTAL OPERATING RESULT | ||
| VAT Code | Description | %VAT |
|---|---|---|
| Explanations | ||
| V = Sales (200) | ||
| VS = Discount sales and services (235) | ||
| B = Acquisition tax (38x) | ||
| M = Expenses for material and services (400) | ||
| I = Investments and other operating expenses (405) | ||
| K = Corrections (410, 415, 420) | ||
| Z = Not considered (910) | ||
| VAT codes information (do not modify) | ||
| id=vatcodes-che-2024.20230614 | ||
| Last update: 14.06.2023 | ||
| VAT Due | ||
| V0 | Exempt services (220) | |
| V0-E | Export services abroad (221) | |
| V0-T | Transfers in the reporting procedure (225) | |
| V0-N | Non-taxable services (230) | |
| Decrease of income from services, see discounts | ||
| V0-D | Various (280) | |
| V77 | Sales and services 7.7% | 7.70 |
| V81 | Sales and services 8.1% | 8.10 |
| V77-B | Sales and services 7.7% (chosen) | 7.70 |
| V81-B | Sales and services 8.1% (chosen) | 8.10 |
| V25-N | Sales and services 2.5% | 2.50 |
| V26 | Sales and services 2.6% | 2.60 |
| V37 | Sales and services 3.7% | 3.70 |
| V38 | Sales and services 3.8% | 3.80 |
| VS77 | Discount Sales and services 7.7% | 7.70 |
| VS81 | Discount Sales and services 8.1% | 8.10 |
| VS25-N | Discount Sales and services 2.5% | 2.50 |
| VS26 | Discount Sales and services 2.6% | 2.60 |
| VS37 | Discount Sales and services 3.7% | 3.70 |
| VS38 | Discount Sales and services 3.8% | 3.80 |
| Taxable turnover (299) | ||
| F1 | 1. Flat tax rate 2024 | |
| F2 | 2. Flat tax rate 2024 | |
| FS1 | Discount Sales and services 1. Flat tax rate 2024 | |
| FS2 | Discount Sales and services 2. Flat tax rate 2024 | |
| F3 | 1. Flat tax rate 2018 | |
| F4 | 2. Flat tax rate 2018 | |
| FS3 | Discount Sales and services 1. Flat tax rate 2018 | |
| FS4 | Discount Sales and services 2. Flat tax rate 2018 | |
| Total Flat tax rate (322-333) | ||
| B77 | Acquisition tax 7.7% (With VAT/Sales tax) | 7.70 |
| B77-1 | Acquisition tax 7.7% (Without VAT/Sales tax) | 7.70 |
| B77-2 | Acquisition tax 7.7% (VAT/Sales tax amount) | 7.70 |
| B81 | Acquisition tax 8.1% (With VAT/Sales tax) | 8.10 |
| B81-1 | Acquisition tax 8.1% (Without VAT/Sales tax) | 8.10 |
| B81-2 | Acquisition tax 8.1% (VAT/Sales tax amount) | 8.10 |
| Total Tax on purchases (382-383) | ||
| Total VAT Due (399) | ||
| Recoverable VAT | ||
| M0 | Exempt material- and service expenses | |
| I0 | Exempt investment and operating expenses | |
| M77 | Purchase of material and services 7.7% (With VAT/Sales tax) | 7.70 |
| M77-1 | Purchase of material and services 7.7% (Without VAT/Sales tax) | 7.70 |
| M77-2 | Purchase of material and services 7.7% (VAT/Sales tax amount) | 7.70 |
| M81 | Purchase of material and services 8.1% (With VAT/Sales tax) | 8.10 |
| M81-1 | Purchase of material and services 8.1% (Without VAT/Sales tax) | 8.10 |
| M81-2 | Purchase of material and services 8.1% (VAT/Sales tax amount) | 8.10 |
| M25 | Purchase of material and services 2.5% | 2.50 |
| M26 | Purchase of material and services 2.6% | 2.60 |
| M37 | Purchase of material and services 3.7% | 3.70 |
| M38 | Purchase of material and services 3.8% | 3.80 |
| Investment and operating expenses | ||
| I77 | Investment and operating expenses 7.7% | 7.70 |
| I77-1 | Investment and operating expenses 7.7% (Without VAT/Sales tax) | 7.70 |
| I77-2 | Investment and operating expenses 7.7% (VAT/Sales tax amount) | 7.70 |
| I81 | Investment and operating expenses 8.1% | 8.10 |
| I81-1 | Investment and operating expenses 8.1% (Without VAT/Sales tax) | 8.10 |
| I81-2 | Investment and operating expenses 8.1% (VAT/Sales tax amount) | 8.10 |
| I25 | Investment and operating expenses 2.5% | 2.50 |
| I26 | Investment and operating expenses 2.6% | 2.60 |
| I37 | Investment and operating expenses 3.7% | 3.70 |
| I38 | Investment and operating expenses 3.8% | 3.80 |
| Corrections and adjustments | ||
| K77-A | Subsequent adjustment of prior tax 7.7% (410) | 7.70 |
| K81-A | Subsequent adjustment of prior tax 8.1 % (410) | 8.10 |
| K77-B | Corrections of prior tax 7.7% (415) | 7.70 |
| K81-B | Corrections of prior tax 8.1% (415) | 8.10 |
| K77-C | Reductions of the deduction of prior tax 7.7% (420) | 7.70 |
| K81-C | Reductions of the deduction of prior tax 8.1% (420) | 8.10 |
| F1050 | Tax computation according to form Nr. 1050 | |
| F1055 | Tax computation according to form Nr. 1055 | |
| Total Recoverable VAT (479) | ||
| Total VAT payable (500) or VAT credit (510) | ||
| Other financial flows | ||
| Z0-A | Subsidies, tourist taxes collected by the tourism offices, contributions to the institutions responsible for the elimination of waste and for the supply of water (let. a - c) | |
| Z0 | Gifts, dividends, compensation for damages etc. | |
| Not considered | ||
| Final total for control | ||
Ristorante | PMI | IVA | Contabilità sull'incassato | con centri di costo
In this article
Ristorante | PMI | IVA | Contabilità sull'incassato | con centri di costo
Ristorante | PMI | IVA | Contabilità sull'incassato | con centri di costo
Modello destinato per gestire la contabilità di un ristorante o di un bar. Piano contabile ben strutturato per avere maggiori dettagli per gruppi di costo e di ricavo e avere maggiore controllo sulla liquidità e redditività.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
Il nostro modello è studiato su misura per le esigenze contabili di ristoranti e bar.
Funzionalità Principali
- Inserimento automatizzato delle registrazioni contabili
- Calcolo e rendicontazione IVA semplificati
- Segnalazione automatica di errori e incongruenze
- Stampe professionali:
Vantaggi di una Contabilità Organizzata
La contabilità non è solo un adempimento fiscale: è uno strumento strategico per ottimizzare risorse, aumentare i profitti e prendere decisioni basate su dati concreti.
Controllo dei Costi
- Identificazione rapida delle spese eccessive
- Riduzione degli sprechi (soprattutto su materie prime).
Maggiore Redditività
- Analisi dei piatti più venduti e più redditizi
- Ottimizzazione del menu e della gestione della cucina.
Decisioni Strategiche Basate sui Dati
- Previsione della stagionalità
- Pianificazione degli investimenti
Crea il tuo File in pochi passi
Vai su File > Proprietà file per impostare:
- Periodo contabile
- Nome del tuo ristorante o bar
- Moneta di base
Salva il file con File > Salva con nome
Includere nome del locale e anno, es. "Ristorante Belvedere 2025.ac2"
Risorse utili
Shop | Income & Expense accounting | VAT net tax rate
In this article
Shop | Income & Expense accounting | VAT net tax rate
Shop | Income & Expense accounting | VAT net tax rate
Ideal for managing your income and expenses with VAT net tax rate method. The structure of the chart of accounts corresponds to the Swiss SME chart of accounts and sample recordings are available.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate preview
Company XX
Accounting 2024
Basic Currency: CHF
Income & Expense accounting with VAT/Sales tax
| Group | Account | Description | Sum In |
|---|---|---|---|
| ESTATE | |||
| 1000 | Cash | 1 | |
| 1010 | Post office current account | 1 | |
| 1020 | Bank current account | 1 | |
| 1100 | Credits | 1 | |
| 1176 | Withholding tax | 1 | |
| 1520 | Office machinery, information and communication technology | 1 | |
| 2000 | Current liabilities short term | 1 | |
| 2200 | VAT Due | 1 | |
| 2201 | VAT according to VAT report | 1 | |
| 2400 | Liabilities long term | 1 | |
| 1 | NET ESTATE | ||
| Group | Category | Description | Sum In |
|---|---|---|---|
| OPERATING RESULT | |||
| INCOME | |||
| 3000 | Sales merchandise category A | 3 | |
| 3001 | Sales merchandise category B | 3 | |
| 3002 | Various sales | 3 | |
| 3090 | Discounts on purchases | 3 | |
| 3680 | Various revenue | 3 | |
| 3809 | VAT flat tax rate | 3 | |
| 7000 | Revenue from investments | 3 | |
| 3 | TOTAL INCOME | 00 | |
| EXPENSES | |||
| 4000 | Purchase merchandise category A | 4 | |
| 4001 | Purchase merchandise category B | 4 | |
| 4003 | Purchase raw materials | 4 | |
| 4005 | Purchase packaging | 4 | |
| 4090 | Discounts on purchases | 4 | |
| 5000 | Salaries | 4 | |
| 5700 | Contributions to old age insurance and unemployment | 4 | |
| 5720 | Contributions to pension funds | 4 | |
| 5730 | Contributions to accident insurance | 4 | |
| 5790 | Source tax | 4 | |
| 5820 | Travel and entertainment expenses | 4 | |
| 5850 | Various expenses | 4 | |
| 5900 | Third-party payments | 4 | |
| 5901 | Subcontracting | 4 | |
| 6000 | Rental | 4 | |
| 6100 | Maintenance & upkeep | 4 | |
| 6220 | Insurance premiums | 4 | |
| 6402 | Electricity | 4 | |
| 6410 | Heating expenses | 4 | |
| 6430 | Water | 4 | |
| 6460 | Garbage | 4 | |
| 6500 | Office supplies | 4 | |
| 6510 | Telephone | 4 | |
| 6600 | Advertising | 4 | |
| 6800 | Depreciation and value adjustments of fixed assets | 4 | |
| 6900 | Financial costs | 4 | |
| 8900 | Taxes | 4 | |
| 4 | TOTAL EXPENSES | 00 | |
| 00 | OPERATING RESULT | ||
| VAT Code | Description | %VAT |
|---|---|---|
| Explanations | ||
| V = Sales (200) | ||
| VS = Discount sales and services (235) | ||
| B = Acquisition tax (38x) | ||
| M = Expenses for material and services (400) | ||
| I = Investments and other operating expenses (405) | ||
| K = Corrections (410, 415, 420) | ||
| Z = Not considered (910) | ||
| VAT codes information (do not modify) | ||
| id=vatcodes-che-2024.20230614 | ||
| Last update: 14.06.2023 | ||
| VAT Due | ||
| V0 | Exempt services (220) | |
| V0-E | Export services abroad (221) | |
| V0-T | Transfers in the reporting procedure (225) | |
| V0-N | Non-taxable services (230) | |
| Decrease of income from services, see discounts | ||
| V0-D | Various (280) | |
| V77 | Sales and services 7.7% | 7.70 |
| V81 | Sales and services 8.1% | 8.10 |
| V77-B | Sales and services 7.7% (chosen) | 7.70 |
| V81-B | Sales and services 8.1% (chosen) | 8.10 |
| V25-N | Sales and services 2.5% | 2.50 |
| V26 | Sales and services 2.6% | 2.60 |
| V37 | Sales and services 3.7% | 3.70 |
| V38 | Sales and services 3.8% | 3.80 |
| VS77 | Discount Sales and services 7.7% | 7.70 |
| VS81 | Discount Sales and services 8.1% | 8.10 |
| VS25-N | Discount Sales and services 2.5% | 2.50 |
| VS26 | Discount Sales and services 2.6% | 2.60 |
| VS37 | Discount Sales and services 3.7% | 3.70 |
| VS38 | Discount Sales and services 3.8% | 3.80 |
| Taxable turnover (299) | ||
| F1 | 1. Flat tax rate 2024 | |
| F2 | 2. Flat tax rate 2024 | |
| FS1 | Discount Sales and services 1. Flat tax rate 2024 | |
| FS2 | Discount Sales and services 2. Flat tax rate 2024 | |
| F3 | 1. Flat tax rate 2018 | |
| F4 | 2. Flat tax rate 2018 | |
| FS3 | Discount Sales and services 1. Flat tax rate 2018 | |
| FS4 | Discount Sales and services 2. Flat tax rate 2018 | |
| Total Flat tax rate (322-333) | ||
| B77 | Acquisition tax 7.7% (With VAT/Sales tax) | 7.70 |
| B77-1 | Acquisition tax 7.7% (Without VAT/Sales tax) | 7.70 |
| B77-2 | Acquisition tax 7.7% (VAT/Sales tax amount) | 7.70 |
| B81 | Acquisition tax 8.1% (With VAT/Sales tax) | 8.10 |
| B81-1 | Acquisition tax 8.1% (Without VAT/Sales tax) | 8.10 |
| B81-2 | Acquisition tax 8.1% (VAT/Sales tax amount) | 8.10 |
| Total Tax on purchases (382-383) | ||
| Total VAT Due (399) | ||
| Recoverable VAT | ||
| M0 | Exempt material- and service expenses | |
| I0 | Exempt investment and operating expenses | |
| M77 | Purchase of material and services 7.7% (With VAT/Sales tax) | 7.70 |
| M77-1 | Purchase of material and services 7.7% (Without VAT/Sales tax) | 7.70 |
| M77-2 | Purchase of material and services 7.7% (VAT/Sales tax amount) | 7.70 |
| M81 | Purchase of material and services 8.1% (With VAT/Sales tax) | 8.10 |
| M81-1 | Purchase of material and services 8.1% (Without VAT/Sales tax) | 8.10 |
| M81-2 | Purchase of material and services 8.1% (VAT/Sales tax amount) | 8.10 |
| M25 | Purchase of material and services 2.5% | 2.50 |
| M26 | Purchase of material and services 2.6% | 2.60 |
| M37 | Purchase of material and services 3.7% | 3.70 |
| M38 | Purchase of material and services 3.8% | 3.80 |
| Investment and operating expenses | ||
| I77 | Investment and operating expenses 7.7% | 7.70 |
| I77-1 | Investment and operating expenses 7.7% (Without VAT/Sales tax) | 7.70 |
| I77-2 | Investment and operating expenses 7.7% (VAT/Sales tax amount) | 7.70 |
| I81 | Investment and operating expenses 8.1% | 8.10 |
| I81-1 | Investment and operating expenses 8.1% (Without VAT/Sales tax) | 8.10 |
| I81-2 | Investment and operating expenses 8.1% (VAT/Sales tax amount) | 8.10 |
| I25 | Investment and operating expenses 2.5% | 2.50 |
| I26 | Investment and operating expenses 2.6% | 2.60 |
| I37 | Investment and operating expenses 3.7% | 3.70 |
| I38 | Investment and operating expenses 3.8% | 3.80 |
| Corrections and adjustments | ||
| K77-A | Subsequent adjustment of prior tax 7.7% (410) | 7.70 |
| K81-A | Subsequent adjustment of prior tax 8.1 % (410) | 8.10 |
| K77-B | Corrections of prior tax 7.7% (415) | 7.70 |
| K81-B | Corrections of prior tax 8.1% (415) | 8.10 |
| K77-C | Reductions of the deduction of prior tax 7.7% (420) | 7.70 |
| K81-C | Reductions of the deduction of prior tax 8.1% (420) | 8.10 |
| F1050 | Tax computation according to form Nr. 1050 | |
| F1055 | Tax computation according to form Nr. 1055 | |
| Total Recoverable VAT (479) | ||
| Total VAT payable (500) or VAT credit (510) | ||
| Other financial flows | ||
| Z0-A | Subsidies, tourist taxes collected by the tourism offices, contributions to the institutions responsible for the elimination of waste and for the supply of water (let. a - c) | |
| Z0 | Gifts, dividends, compensation for damages etc. | |
| Not considered | ||
| Final total for control | ||
Doppia: Hotel | PMI | IVA | Contabilità sull'incassato | centri di costo
In this article
Doppia: Hotel | PMI | IVA | Contabilità sull'incassato | centri di costo
Doppia: Hotel | PMI | IVA | Contabilità sull'incassato | centri di costo
Il piano dei conti è progettato per gestire in modo efficiente la contabilità di un hotel. La struttura del piano dei conti è dettagliata e include i centri di costo, che consentono di monitorare separatamente la redditività dei servizi accessori offerti dalla struttura, come lavanderia, chiosco, SPA, parcheggio, e altri reparti. Questo approccio facilita l’analisi economico-finanziaria per singola area operativa, supportando un controllo di gestione preciso e orientato alle performance. In automatico ottieni il Bilancio, il Conto economico, Rendiconti IVA e tanti altri report che ti permettono di adempiere agli obblighi fiscali e tenere sotto controllo la situazione finanziaria ed economica dell'hotel.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
Una buona gestione contabile di un hotel è fondamentale per avere il pieno controllo dei flussi economici, dei reparti e dei costi operativi. Una contabilità chiara e ben organizzata è lo strumento che consente di prendere decisioni strategiche in modo consapevole e tempestivo.
Il piano dei conti è strutturato per soddisfare le esigenze contabili e gestionali specifiche di una struttura alberghiera. Esso consente di classificare e organizzare in modo sistematico tutte le operazioni economico-finanziarie dell'hotel, garantendo una corretta tenuta della contabilità generale e l'elaborazione di report gestionali efficaci.
Automazione e importazione movimenti
Per ottimizzare i tempi di registrazione contabile, è prevista la possibilità di importare i movimenti direttamente dagli estratti conto bancari, postali e delle carte di credito. Ciò riduce gli errori manuali e velocizza il processo di contabilizzazione.
L'utilizzo delle Regole di registrazione automatica durante l'importazione permette di associare automaticamente le contropartite contabili, i codici IVA, i centri di costo e altre informazioni accessorie. Questa funzionalità favorisce l’uniformità delle registrazioni e l’affidabilità dei dati contabili.
Grazie alle funzioni di automazione ci sono vantaggi e benefici non indifferenti:
- Immissione veloce dei dati e più tempo per attività a maggior valore aggiunto
- Riduce il rischio di errori manuali
- Dati sempre aggiornati con visione in tempo reale dello stato finanziario dell’hotel.
Gestione IVA
Il programma gestisce automaticamente l’IVA secondo la normativa svizzera, generando i rendiconti richiesti e i file XML per la trasmissione online. Questo assicura conformità normativa e riduce al minimo il lavoro manuale.
Per utilizzare le estensioni IVA 2024/2025, occorre:
Il Rendiconto IVA Svizzera 2024/2025 viene creato in automatico grazie alle seguenti estensioni, integrate in Banana Contabilità Plus:
Centri di costo e analisi per area operativa
A supporto dell’analisi economica, sono stati definiti appositi centri di costo, che permettono di monitorare la redditività dei singoli reparti o servizi offerti: camere, ristorazione, centro benessere (SPA), eventi, parcheggi, ecc. Ad esempio, è possibile sapere se il centro benessere copre i costi o se il ristorante lavora in perdita, così da intervenire con azioni mirate. Questo consente una valutazione dettagliata delle performance operative e supporta il processo decisionale nella gestione strategica.
Reportistica e bilanci
La reportistica e bilanci in una contabilità alberghiera non sono degli strumenti fiscali, ma dei veri alleati per guidare la gestione, migliorare la redditività e garantire la sostenibilità dell’attività nel tempo.
I bilanci e le principali stampe contabili e fiscali sono completamente automatizzate e vengono generate in modo chiaro e dettagliato. I report includono:
- Stato patrimoniale
- Conto economico
- Centri di costo e profitto
- Rendiconti IVA e liquidazioni periodiche
- Report analitici per gestione e controllo interno
L'automazione delle stampe consente di avere aggiornamenti in tempo reale, migliorando la capacità di monitoraggio e previsione finanziaria.
Revenue-based Accounting Tutorial for Ltd and LLC | SME
In this article
Revenue-based Accounting Tutorial for Ltd and LLC | SME
Revenue-based Accounting Tutorial for Ltd and LLC | SME
The ideal template for a Ltd or LLC with VAT management based on revenue. The chart of accounts is structured according to SME standards, and the VAT Codes table includes the rates valid from 01.01.2024. You can manage customers and suppliers, create invoices with QR codes, send reminders, and prepare the VAT report. Professional and immediate reports: Balance Sheet, Profit and Loss Statement, Account Cards, Journal, VAT Summaries, and many other reports, including by period. Cost Centers and Segments to monitor expenses and profitability by sector or project. Digital attachments can be added to transactions. Open the template from our WebApp or directly from the program and save the file to your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open tutorial in WebAppTemplate documentation
Efficient and customizable accounting management for SMEs
Our accounting template is pre-configured according to the standard framework of the Swiss Code of Obligations, specifically designed to meet the needs of small and medium-sized enterprises (SMEs) with an annual turnover equal to or greater than CHF 500,000.
Flexibility and customization
If you need to customize the chart of accounts, you can easily add new accounts. See our dedicated page on the Complete SME Chart of Accounts, which includes all the accounts and groups specified by the Swiss SME account system (Sterchi, Mattle, Helbing), ensuring perfect integration.
Simplicity and automation
Data entry is fast and intuitive, with an interface similar to Excel. You can import data directly from your bank statements or credit cards, and thanks to the use of Rules, the process becomes fully automated, drastically reducing manual work.
All-round accounting management
Record transactions quickly and automatically, keep balances always updated, and generate professional real-time reports. With our system, you can:
- Create and post invoices simultaneously
- Send reminders easily
- Make cash flow forecasts and manage budgets
- Generate Balance Sheet, Profit and Loss Statement, Account Cards and Journal
- With the VAT extension, send VAT report data online to the FTA (only with Advanced plan).
Some features require a subscription to the Banana Accounting Plus Advanced plan, such as generating the sample or XML file for the VAT report, using the new Rules functions, Filter, and temporary Sort Rows. See all the features of the Advanced plan.
Create your file
- Open the template with Banana Accounting Plus WebApp
- With the File > File Properties command, set the period, your company name, and the base currency (you can do budgeting and accounting in any currency).
- With the File > Save As command, save the file. It is useful to include the company name and year in the file name. For example, "Rossi-SA-20xx.ac2".
WARNING: if you close the browser without saving, you will lose the entered data. Always save the file to your computer.
To reopen the saved file click on File > Open.
Also see Organize accounting files locally, on network and cloud.
Accounts Table
When opening the template, the chart of accounts includes all the accounts to manage your business. You only need to enter:
- In the Accounts table, Account column, your Customer and Supplier accounts complete with address, country code, and language.
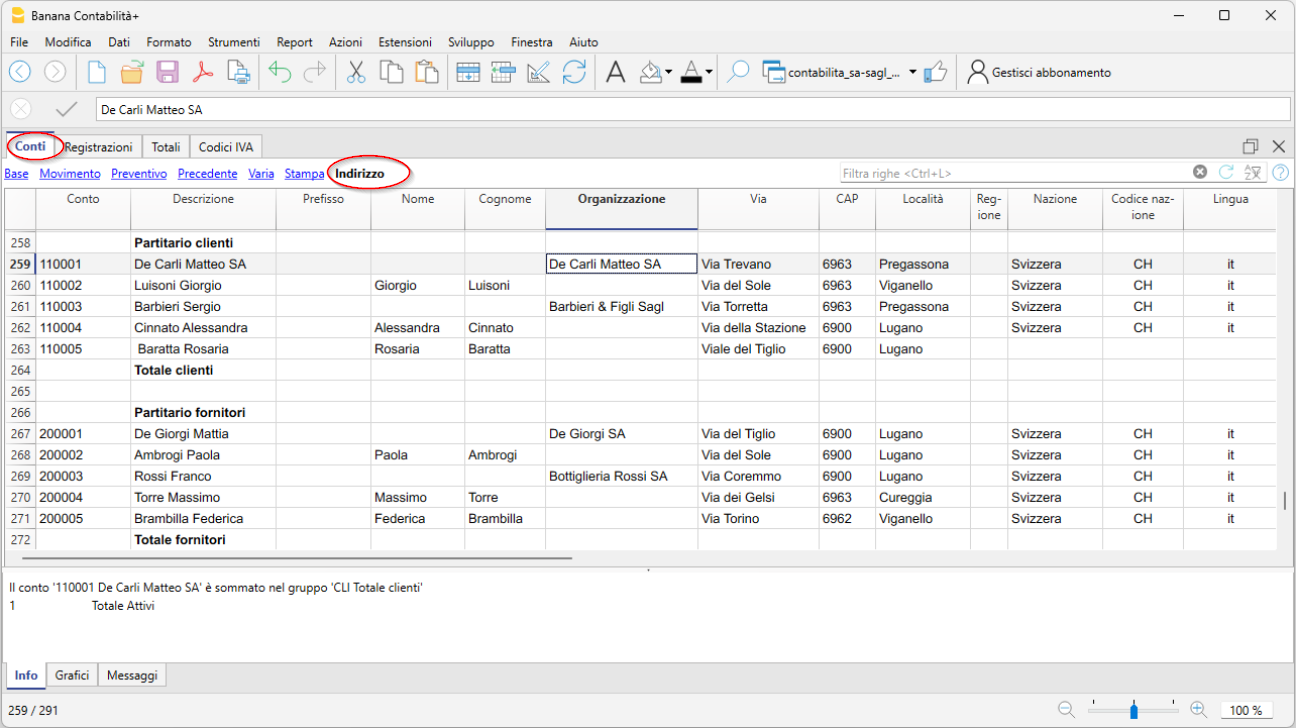
- In the Accounts table, Opening column, the initial balance for each account (for assets and liabilities)
At year-end closing, the opening balance is carried forward automatically via Actions > Create new year.
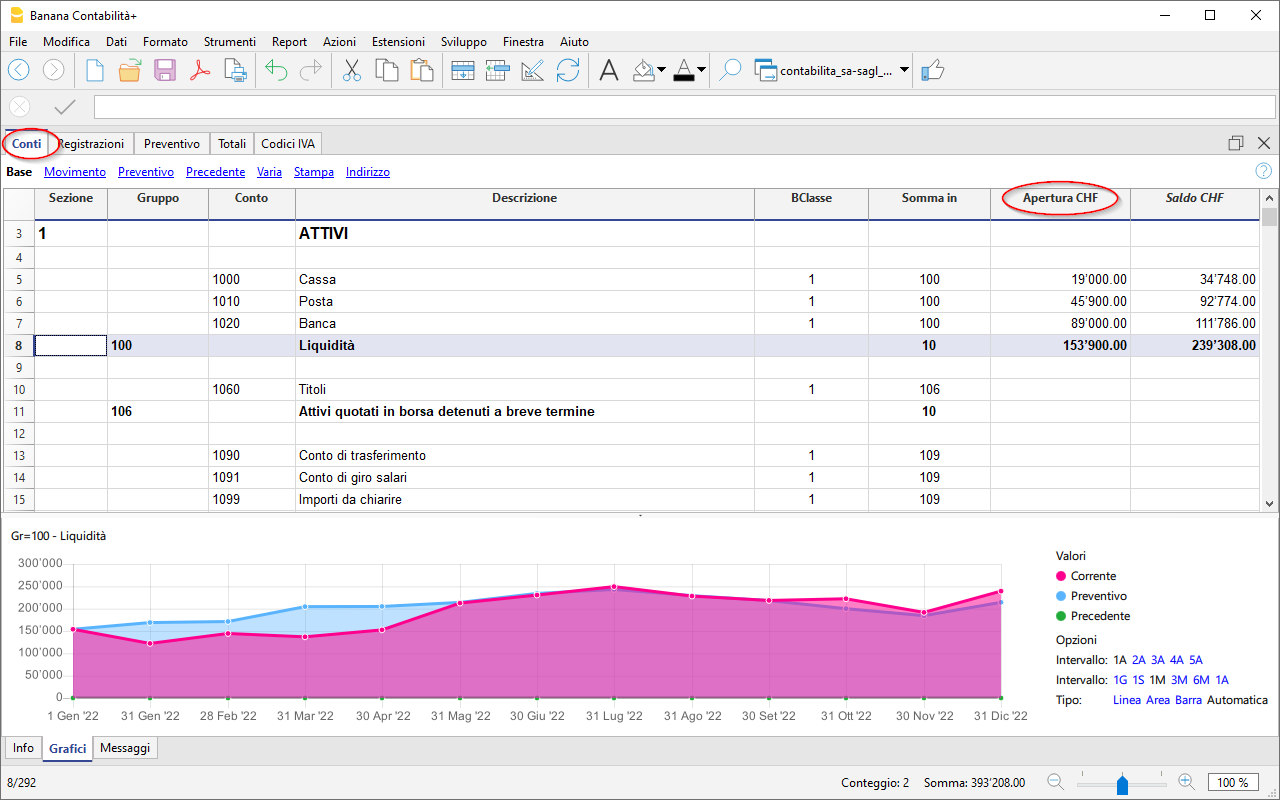
After each transaction, the columns in the Accounts table are updated immediately, giving you a clear and instant view of your financial situation.
The Income Statement has a progressive structure, allowing the profit to be viewed in the following stages:
- Gross operating profit after deducting material and resale goods costs
- Gross operating profit after deducting personnel costs
- Operating result before depreciation, adjustments, financial results, and taxes (EBITDA)
- Operating result before financial results and taxes (EBIT)
- Operating result before taxes (EBT)
- Non-operating result
- Profit or loss before taxes
- Annual profit or loss

Record transactions
In the Transactions table, enter all daily movements. To speed up entry, we recommend using various automation features:
- The Autocomplete data entry feature allows automatic reuse of previously entered data
- The Recurring Transactions feature (under the Actions menu) allows you to store repetitive transactions in a dedicated table
- Importing data from the bank statement retrieves all bank transactions automatically. With the Advanced plan you can use Rules, a new feature that provides full automation of transaction entry.
- You can link each transaction to its digital receipt, and with one click, view the document.
See also Accounting files and digital receipts for better organization of your documents. - Use the Sort Transactions by Date command to order rows by progressive date.
- Use the Print/Preview command to print or export the journal in PDF format.
Transactions with VAT
To record VAT transactions, simply enter the VAT code corresponding to the operation (purchase, sale, international transactions, etc.). Calculations are made automatically, with no need to manually post to the VAT account.
In our templates, all VAT codes are pre-set in compliance with the new 2024 VAT rates.
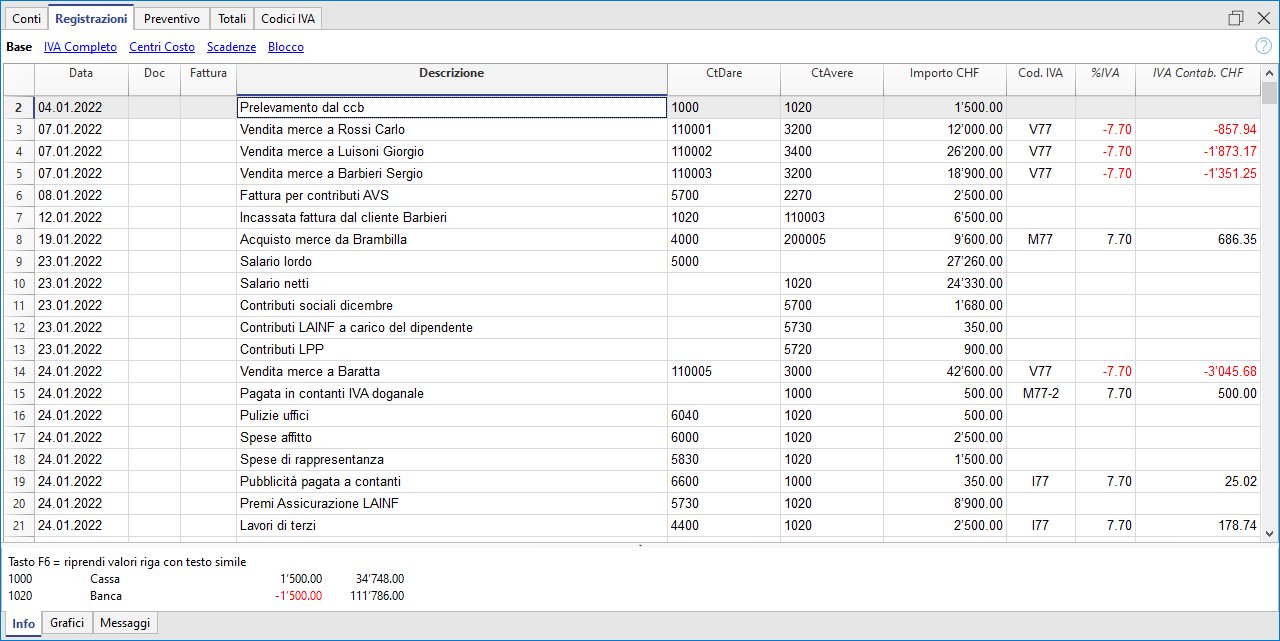
At the end of the period, you can automatically obtain:
- VAT Summary by account, code, percentage for all transactions (Professional and Advanced plans).
- VAT Sample, Effective Method (Advanced plan only)
- VAT Sample, Flat Rate Method (Advanced plan only)
- XML file for electronic data submission (Advanced plan only).
Import transactions from bank statements with Rules (Advanced plan only)
The new Rules feature is the most advanced automation innovation, highly appreciated by our users. This technology simplifies the management of financial transactions imported from bank, postal, and credit card statements using keywords. Each recurring transaction is automatically linked to a keyword, allowing precise assignment of the counterpart, VAT code, costs, and related segments.
Thanks to this system, during subsequent imports, the software quickly recognizes transactions based on the keywords and automatically completes the entry in the Transactions table. This drastically reduces manual entry, significantly speeds up workflow, and minimizes the chance of errors.
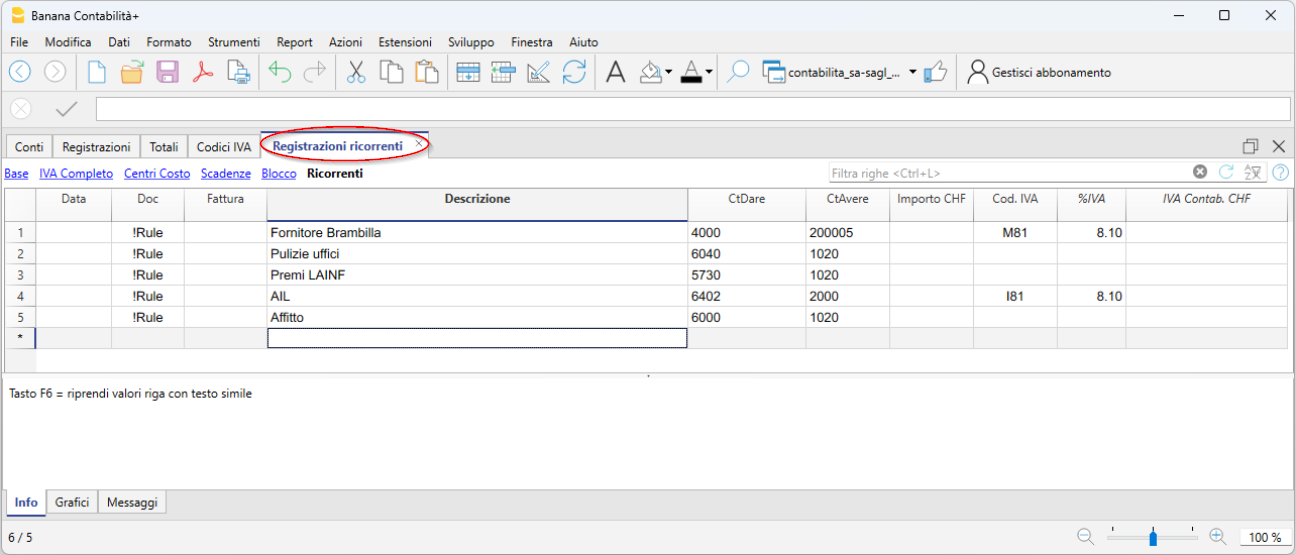
Create your invoices
Integrated invoicing in the accounting file allows invoice data to be recorded in the Transactions table. For each new invoice, insert a new transaction row.
The following settings are essential for creating invoices:
- Enter customer addresses (columns in the Address view)
- Set the customer group
- In the Transactions table, it is essential to enter the invoice number,
You can enter simple invoices on a single row or more complex invoices on multiple rows. Additionally, by enabling the Items columns (from the Tools menu), you can specify quantities, unit, and unit price.
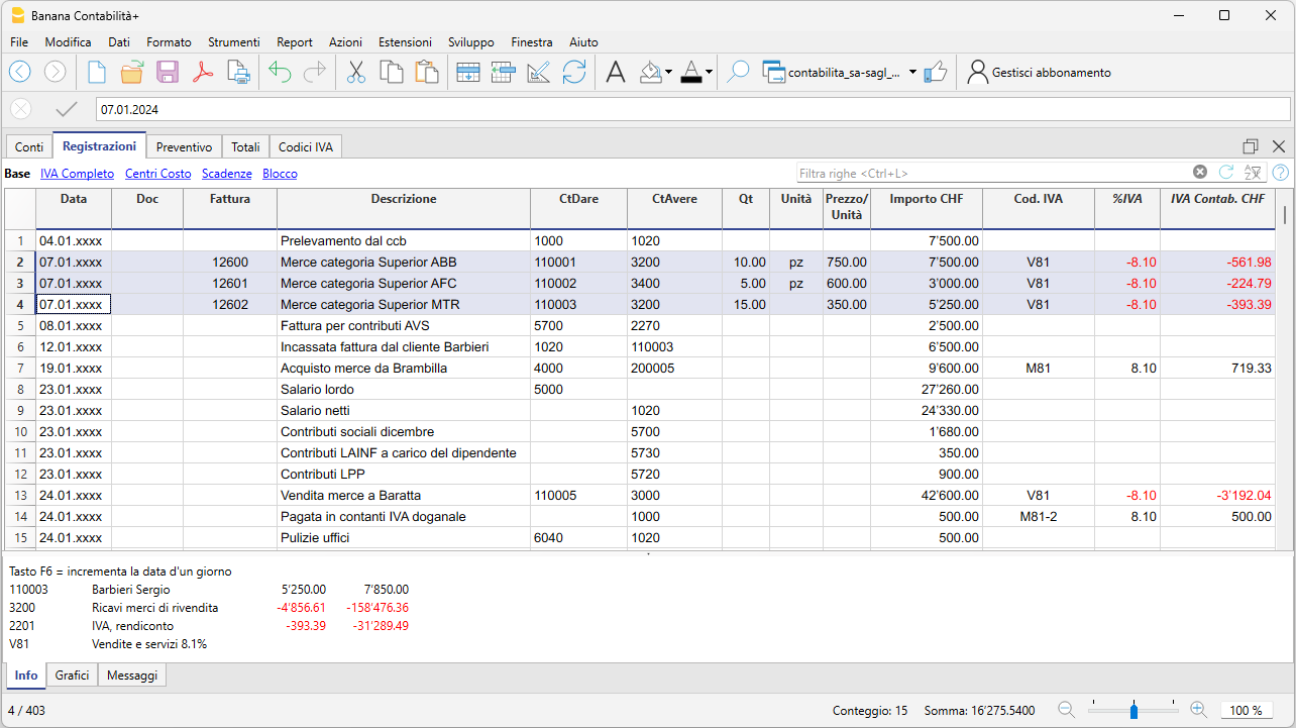
To print the invoice go to Report > Customers > Print Invoice
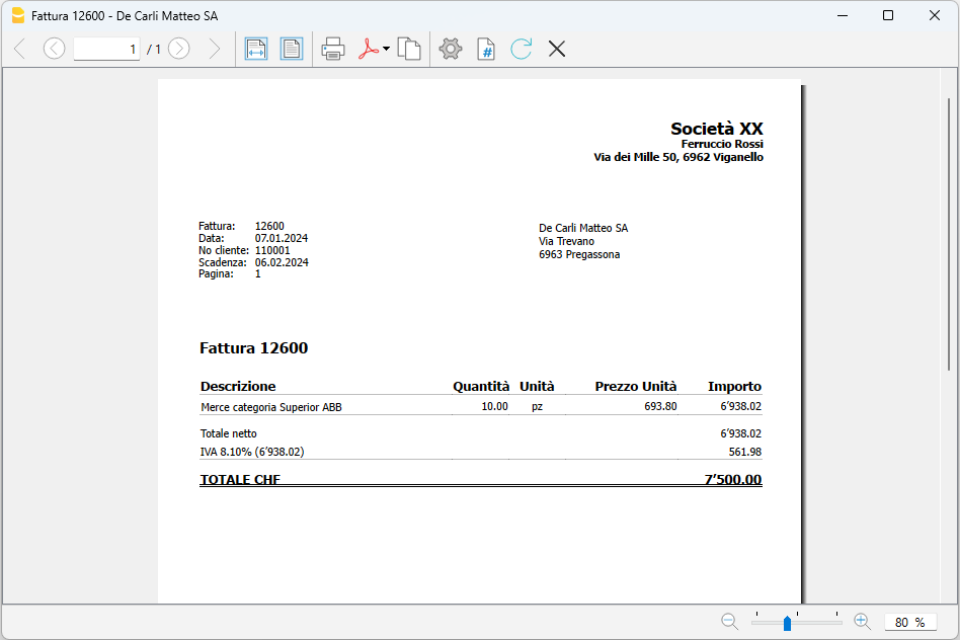
Beautified Balance Sheet with Groups
To view the Balance Sheet, click on the menu Report > Beautified Balance Sheet with Groups. You can customize the report with the columns you want to see, such as including the budget column or having Reports also by period.
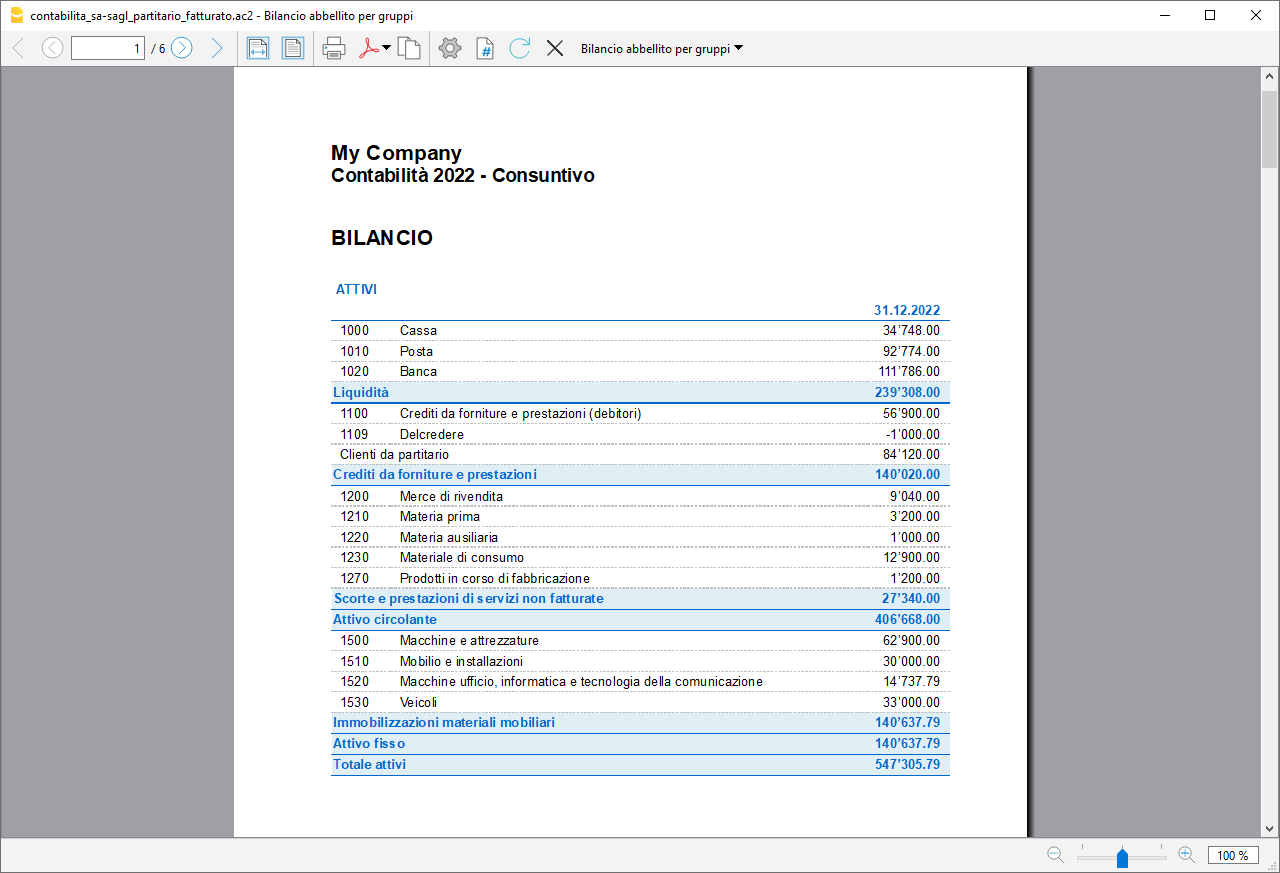
Cash Flow: the lifeblood of your business
Cash flow is central to a company’s ability to operate, maintain solvency with suppliers, and generate income. Anticipating cash availability is essential to avoid mistakes, minimize risks, and optimize strategic decisions, helping you reach your goals successfully.
For optimal business management, it is crucial to have forward-looking insights, forecasting cash flow trends, sales, purchases, and future investments. Knowing whether your business will generate income is important, but forecasting cash availability is even more decisive. Without sufficient liquidity, you may be forced to cut expenses or seek financing.
With Banana Accounting, you can easily create both a cash flow forecast and a financial budget—strategic tools that will help you build a successful future for your business.
Discover the advanced forecasting features in our Documentation:
Template preview
Company XXX
Accounting 2024
Basic Currency: CHF
Double-entry with VAT/Sales tax
| Group | Account | Description | Sum In | Gr1 |
|---|---|---|---|---|
| BALANCE SHEET | ||||
| ASSETS | ||||
| 1000 | Cash on hand | 100 | ||
| 1010 | Post office current account | 100 | ||
| 1020 | Bank account | 100 | ||
| 1045 | Credit cards / Debit cards | 100 | ||
| 100 | Cash and cash equivalents | 10 | 1 | |
| 1060 | Bonds and stocks | 106 | ||
| 106 | Short-term assets listed on the stock exchange | 10 | ||
| 1090 | Internal transfers | 109 | ||
| 1091 | Transfer account for salaries | 109 | ||
| 1099 | Clarification account | 109 | ||
| 109 | Transfer accounts | 10 | ||
| 1100 | Receivables from deliveries and services (debtors) | 110 | ||
| 1109 | Provision for doubtful debts | 110 | ||
| 110A | Clients from register | 110 | ||
| 110 | Receivables from deliveries and services | 10 | ||
| 1140 | Advances and loans | 114 | ||
| 1176 | Withholding tax | 114 | ||
| 1179 | Tax at source | 114 | ||
| 1180 | AHV, IV, EO, ALV current account | 114 | ||
| 1190 | Various short-term receivables | 114 | ||
| 1191 | Deposits | 114 | ||
| 114 | Other short-term receivables | 10 | ||
| 1200 | Resale merchandise | 120 | ||
| 1210 | Raw materials | 120 | ||
| 1230 | Auxiliary material | 120 | ||
| 1231 | Consumables | 120 | ||
| 1260 | Finished products | 120 | ||
| 1270 | Semi-finished products | 120 | ||
| 1280 | Non-invoiced services | 120 | ||
| 120 | Inventories and non-invoiced services | 10 | 1 | |
| 1300 | Prepaid expenses | 130 | ||
| 1301 | Accrued income | 130 | ||
| 130 | Accrued income and prepaid expenses | 10 | 1 | |
| 10 | Current assets | 1 | 1 | |
| 1400 | Bonds and stocks | 140 | ||
| 1440 | Loans | 140 | ||
| 1460 | Loans/Mortgages to shareholder | 140 | ||
| 140 | Financial assets | 14 | ||
| 1480 | Participations | 148 | ||
| 148 | Participations | 14 | ||
| 1500 | Machinery and equipment | 150 | ||
| 1510 | Furniture and installations | 150 | ||
| 1520 | Office machines, information and communication technology | 150 | ||
| 1530 | Vehicles | 150 | ||
| 1540 | Tools and equipment | 150 | ||
| 150 | Movable tangible assets | 14 | ||
| 1600 | Commercial properties | 160 | ||
| 160 | Fixed tangible assets | 14 | ||
| 1700 | Patents, know-how, licences, rights and development | 170 | ||
| 1710 | Brands | 170 | ||
| 1712 | Models | 170 | ||
| 1770 | Goodwill | 170 | ||
| 170 | Intangible assets | 14 | ||
| 1850 | Unpaid share capital, nominal capital, participation certificate capital and foundation capital | 180 | ||
| 180 | Unpaid share capital or foundation capital | 14 | ||
| 14 | Fixed assets | 1 | ||
| 1 | Total assets | 00 | ||
| LIABILITIES | ||||
| 2000 | Accounts payable (creditors) | 200 | ||
| 2030 | Advance payments from third parties | 200 | ||
| 200A | Suppliers from register | 200 | ||
| 200 | Accounts payable | 20 | 1 | |
| 2100 | Short-term debt due to banks | 210 | ||
| 2120 | Financial leasing commitments | 210 | ||
| 2140 | Other onerous debts | 210 | ||
| 210 | Short-term interest-bearing debts | 20 | ||
| 2200 | VAT due | 220 | ||
| 2201 | VAT settlement account | 220 | ||
| 2206 | Withholding tax | 220 | ||
| 2208 | Direct taxes | 220 | ||
| 2209 | Tax at source | 220 | ||
| 2210 | Other short-term debts | 220 | ||
| 2260 | Debts due to shareholder | 220 | ||
| 2269 | Dividends | 220 | ||
| 2270 | AHV, IV, EO, ALV current account | 220 | ||
| 220 | Other short-term debts | 20 | ||
| 2300 | Accrued expenses | 230 | ||
| 2301 | Revenues received in advance | 230 | ||
| 2330 | Short-term provisions | 230 | ||
| 230 | Accruals and deferred income, short-term provisions | 20 | ||
| 20 | Short-term third party capital | 2A | ||
| 2400 | Due to banks | 240 | ||
| 2420 | Financial leasing commitments | 240 | ||
| 2430 | Debenture loans | 240 | ||
| 2450 | Loans | 240 | ||
| 2451 | Mortgages | 240 | ||
| 240 | Long-term interest-bearing debts | 24 | ||
| 2500 | Other long-term debts (not interest-bearing) | 250 | ||
| 250 | Other long-term debts | 24 | ||
| 2630 | Provisions | 260 | ||
| 260 | Long-term provisions and similar statutory positions | 24 | ||
| 24 | Long-term third party capital | 2A | ||
| 2A | Third party capital | 2 | ||
| 2800 | Share capital, nominal capital, participation rights or foundation capital | 280 | ||
| 280 | Nominal capital or capital of the foundation | 28 | ||
| 2900 | Premium at foundation or in the event of a capital increase | |||
| 2903 | Legal reserves | 290 | ||
| 2950 | Legal retained earnings | 290 | ||
| 2955 | Revaluation reserve | 290 | ||
| 2960 | Optional retained earnings | 290 | ||
| 290 | Reserves | 28 | ||
| 2965 | Own shares, nominal shares, share certificates and participation certificates (negative) | 296 | ||
| 296 | Own shares, nominal shares, share certificates and participation certificates (negative) | 28 | ||
| 2970 | Profit or loss carried forward | 297 | ||
| 2979 | Profit or loss for the year | 297 | ||
| 297 | Profit or loss from Balance Sheet | 28 | ||
| 28 | Equity | 2 | ||
| 2 | Total liabilities | 00 | 1 | |
| PROFIT & LOSS STATEMENT | ||||
| 3000 | Revenues from own products | 30 | ||
| 3200 | Revenues from resale merchandise | 30 | ||
| 3400 | Revenues from provided services | 30 | ||
| 3600 | Other revenues and services | 30 | ||
| 3710 | Own consumption | 30 | ||
| 3800 | Decrease in revenues | 30 | ||
| 3805 | Losses on receivables, changes in value adjustments | 30 | ||
| 3810 | Credit/debit card fees | 30 | ||
| 30 | Net amount from deliveries and services | 3 | ||
| 3900 | Changes in finished products inventories | 39 | ||
| 3901 | Changes in semi-finished products inventories | 39 | ||
| 3940 | Changes in non-invoiced services value | 39 | ||
| 39 | Changes in inventories and non-invoiced services | 3 | ||
| 3 | Revenues from supplies and services | E1 | ||
| 4000 | Material costs for production | 4 | ||
| 4200 | Merchandise costs for resale | 4 | ||
| 4400 | Expenses for services | 4 | ||
| 4500 | Energy consumption for production | 4 | ||
| 4800 | Discounts | 4 | ||
| 4 | Costs for material, goods, services and energy | E1 | ||
| E1 | Gross operating result after deducting costs for materials and resale merchandise | E2 | ||
| 5000 | Salaries | 5 | ||
| 5700 | AHV, IV, EO, ALV contributions | 5 | ||
| 5710 | Family allowance | 5 | ||
| 5720 | Contribution to pension funds | 5 | ||
| 5730 | Contribution to accident insurance | 5 | ||
| 5740 | Daily sickness benefits insurance | 5 | ||
| 5790 | Tax at source | 5 | ||
| 5800 | Other personnel expenses | 5 | ||
| 5810 | Personnel training | 5 | ||
| 5820 | Travel expenses | 5 | ||
| 5830 | Management flat-rate expenses | 5 | ||
| 5900 | Benefits from third parties | 5 | ||
| 5 | Personnel expenses | E2 | ||
| E2 | Gross operating result after deducting personnel expenses | E3 | ||
| 6000 | Rental | 60 | ||
| 6040 | Cleaning | 60 | ||
| 60 | Facility expenses | 6 | ||
| 6100 | Maintenance, repairs and replacement of movable tangible assets | 61 | ||
| 6105 | Leasing of movable tangible assets | 61 | ||
| 61 | Maintenance, repairs, replacements (MRR): leasing of movable tangible assets | 6 | ||
| 6200 | Repairs | 62 | ||
| 6210 | Petrol | 62 | ||
| 6220 | Liability insurance | 62 | ||
| 6260 | Vehicle leasing and rental | 62 | ||
| 6270 | Private share of vehicle expenses | 62 | ||
| 6280 | Freights | 62 | ||
| 62 | Vehicle and transport expenses | 6 | ||
| 6300 | Property insurance, charges, fees, permits | 63 | ||
| 63 | Property insurance, charges, fees, permits | 6 | ||
| 6400 | Electricity | 64 | ||
| 6410 | Heating | 64 | ||
| 6430 | Water | 64 | ||
| 6460 | Garbage | 64 | ||
| 64 | Energy and disposal costs | 6 | ||
| 6500 | Office equipment | 65 | ||
| 6503 | Specialist publications, newspapers, periodicals | 65 | ||
| 6510 | Telephone | 65 | ||
| 6512 | Internet | 65 | ||
| 6513 | Postal charges | 65 | ||
| 6570 | IT charges including leasing | 65 | ||
| 6580 | Licenses and updates expenses | 65 | ||
| 6583 | Consumables | 65 | ||
| 65 | Administrative and IT expenses | 6 | ||
| 6600 | Advertisements | 66 | ||
| 6642 | Gifts to customers | 66 | ||
| 66 | Advertising expenses | 6 | ||
| 6700 | Other operating expenses | 67 | ||
| 67 | Other operating expenses | 6 | ||
| 6 | Various operating expenses | E3 | ||
| E3 | Operating result before depreciation and value adjustments, financial results and taxes (EBITDA) | E4 | ||
| 6800 | Depreciation and value adjustments to fixed assets | 68 | ||
| 68 | Depreciation and value adjustments to fixed assets | E4 | ||
| E4 | Operating result before financial results and taxes (EBIT) | E5 | ||
| 6900 | Financial costs | 69 | ||
| 6940 | Bank costs | 69 | ||
| 6950 | Financial revenues | 69 | ||
| 69 | Financial costs and revenues | E5 | ||
| E5 | Operating result before taxes (EBT) | E6 | ||
| 7000 | Ancillary activities revenues | 7 | ||
| 7010 | Ancillary activities costs | 7 | ||
| 7500 | Operational real estate revenues | 7 | ||
| 7510 | Operational real estate costs | 7 | ||
| 7 | Ancillary operating result | E6 | ||
| 8000 | Non-operating costs | 8 | ||
| 8100 | Non-operating revenues | 8 | ||
| 8500 | Extraordinary, non-recurring or unrelated to the period costs | 8 | ||
| 8510 | Extraordinary, non-recurring or unrelated to the period revenues | 8 | ||
| 8 | Non-operating, extraordinary, non-recurring or unrelated to the period result | E6 | ||
| E6 | Profit or loss before taxes | E7 | ||
| 8900 | Direct taxes | 89 | ||
| 89 | Direct taxes | E7 | ||
| E7 | Annual profit or loss | 2979 | ||
| 00 | Difference should be = 0 (blank cell) | |||
| Clients register | ||||
| 110001 | Customer A | CLI | ||
| 110002 | Customer B | CLI | ||
| 110003 | Customer C | CLI | ||
| 110004 | Customer D | CLI | ||
| 110005 | Customer E | CLI | ||
| CLI | Total clients | 110A | ||
| Suppliers register | ||||
| 200001 | Supplier A | SUP | ||
| 200002 | Supplier B | SUP | ||
| 200003 | Supplier C | SUP | ||
| 200004 | Supplier D | SUP | ||
| 200005 | Supplier E | SUP | ||
| SUP | Total suppliers | 200A | ||
| COST CENTERS | ||||
| .PAC | Packaging A | INV | ||
| .RM | Raw materials A | INV | ||
| .AM | Auxiliairy materials A | INV | ||
| INV | Total inventories | |||
| ,MAN1 | Maintenance 1 | MAN | ||
| ,MAN2 | Maintenance 2 | MAN | ||
| ,MAN3 | Maintenance 3 | MAN | ||
| MAN | Total maintenance costs | |||
| ;ADV1 | Advertising type 1 | ADV | ||
| ;ADV2 | Advertising type 2 | ADV | ||
| ADV | Total advertising costs | |||
| VAT Code | Description | %VAT |
|---|---|---|
| Explanations | ||
| V = Sales (200) | ||
| VS = Discount sales and services (235) | ||
| B = Acquisition tax (38x) | ||
| M = Expenses for material and services (400) | ||
| I = Investments and other operating expenses (405) | ||
| K = Corrections (410, 415, 420) | ||
| Z = Not considered (910) | ||
| VAT codes information (do not modify) | ||
| id=vatcodes-che-2024.20230614 | ||
| Last update: 14.06.2023 | ||
| VAT Due | ||
| V0 | Exempt services (220) | |
| V0-E | Export services abroad (221) | |
| V0-T | Transfers in the reporting procedure (225) | |
| V0-N | Non-taxable services (230) | |
| Decrease of income from services, see discounts | ||
| V0-D | Various (280) | |
| V77 | Sales and services 7.7% | 7.70 |
| V81 | Sales and services 8.1% | 8.10 |
| V77-B | Sales and services 7.7% (chosen) | 7.70 |
| V81-B | Sales and services 8.1% (chosen) | 8.10 |
| V25-N | Sales and services 2.5% | 2.50 |
| V26 | Sales and services 2.6% | 2.60 |
| V37 | Sales and services 3.7% | 3.70 |
| V38 | Sales and services 3.8% | 3.80 |
| VS77 | Discount Sales and services 7.7% | 7.70 |
| VS81 | Discount Sales and services 8.1% | 8.10 |
| VS25-N | Discount Sales and services 2.5% | 2.50 |
| VS26 | Discount Sales and services 2.6% | 2.60 |
| VS37 | Discount Sales and services 3.7% | 3.70 |
| VS38 | Discount Sales and services 3.8% | 3.80 |
| Taxable turnover (299) | ||
| F1 | 1. Flat tax rate 2024 | |
| F2 | 2. Flat tax rate 2024 | |
| FS1 | Discount Sales and services 1. Flat tax rate 2024 | |
| FS2 | Discount Sales and services 2. Flat tax rate 2024 | |
| F3 | 1. Flat tax rate 2018 | |
| F4 | 2. Flat tax rate 2018 | |
| FS3 | Discount Sales and services 1. Flat tax rate 2018 | |
| FS4 | Discount Sales and services 2. Flat tax rate 2018 | |
| Total Flat tax rate (322-333) | ||
| B77 | Acquisition tax 7.7% (With VAT/Sales tax) | 7.70 |
| B77-1 | Acquisition tax 7.7% (Without VAT/Sales tax) | 7.70 |
| B77-2 | Acquisition tax 7.7% (VAT/Sales tax amount) | 7.70 |
| B81 | Acquisition tax 8.1% (With VAT/Sales tax) | 8.10 |
| B81-1 | Acquisition tax 8.1% (Without VAT/Sales tax) | 8.10 |
| B81-2 | Acquisition tax 8.1% (VAT/Sales tax amount) | 8.10 |
| Total Tax on purchases (382-383) | ||
| Total VAT Due (399) | ||
| Recoverable VAT | ||
| M0 | Exempt material- and service expenses | |
| I0 | Exempt investment and operating expenses | |
| M77 | Purchase of material and services 7.7% (With VAT/Sales tax) | 7.70 |
| M77-1 | Purchase of material and services 7.7% (Without VAT/Sales tax) | 7.70 |
| M77-2 | Purchase of material and services 7.7% (VAT/Sales tax amount) | 7.70 |
| M81 | Purchase of material and services 8.1% (With VAT/Sales tax) | 8.10 |
| M81-1 | Purchase of material and services 8.1% (Without VAT/Sales tax) | 8.10 |
| M81-2 | Purchase of material and services 8.1% (VAT/Sales tax amount) | 8.10 |
| M25 | Purchase of material and services 2.5% | 2.50 |
| M26 | Purchase of material and services 2.6% | 2.60 |
| M37 | Purchase of material and services 3.7% | 3.70 |
| M38 | Purchase of material and services 3.8% | 3.80 |
| Investment and operating expenses | ||
| I77 | Investment and operating expenses 7.7% | 7.70 |
| I77-1 | Investment and operating expenses 7.7% (Without VAT/Sales tax) | 7.70 |
| I77-2 | Investment and operating expenses 7.7% (VAT/Sales tax amount) | 7.70 |
| I81 | Investment and operating expenses 8.1% | 8.10 |
| I81-1 | Investment and operating expenses 8.1% (Without VAT/Sales tax) | 8.10 |
| I81-2 | Investment and operating expenses 8.1% (VAT/Sales tax amount) | 8.10 |
| I25 | Investment and operating expenses 2.5% | 2.50 |
| I26 | Investment and operating expenses 2.6% | 2.60 |
| I37 | Investment and operating expenses 3.7% | 3.70 |
| I38 | Investment and operating expenses 3.8% | 3.80 |
| Corrections and adjustments | ||
| K77-A | Subsequent adjustment of prior tax 7.7% (410) | 7.70 |
| K81-A | Subsequent adjustment of prior tax 8.1 % (410) | 8.10 |
| K77-B | Corrections of prior tax 7.7% (415) | 7.70 |
| K81-B | Corrections of prior tax 8.1% (415) | 8.10 |
| K77-C | Reductions of the deduction of prior tax 7.7% (420) | 7.70 |
| K81-C | Reductions of the deduction of prior tax 8.1% (420) | 8.10 |
| F1050 | Tax computation according to form Nr. 1050 | |
| F1055 | Tax computation according to form Nr. 1055 | |
| Total Recoverable VAT (479) | ||
| Total VAT payable (500) or VAT credit (510) | ||
| Other financial flows | ||
| Z0-A | Subsidies, tourist taxes collected by the tourism offices, contributions to the institutions responsible for the elimination of waste and for the supply of water (let. a - c) | |
| Z0 | Gifts, dividends, compensation for damages etc. | |
| Not considered | ||
| Final total for control | ||
Company | VAT Flat Tax Rate Method | SME
In this article
Company | VAT Flat Tax Rate Method | SME
Company | VAT Flat Tax Rate Method | SME
Default template for managing accounting with VAT balance rate. The VAT code settings and the new extension for the balance rate method have been updated according to the new VAT regulations effective from 01.01.2024. Banana Accounting Plus prepares all calculations, the VAT summary, the VAT report template, and the XML file for electronically submitting data on the AFC website. Open the template from our WebApp or the program and save the file on your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
Companies with an annual turnover (including VAT) not exceeding 5.024 million Swiss francs and a VAT liability not exceeding 103,000 Swiss francs per year can opt for the balance rate VAT method, subject to request and approval from the AFC.
More information are available at the Swiss VAT tax report - Flat tax rate method page (available in German, Italian and French only)
In the Banana Accounting Plus template, the chart of accounts and the VAT Codes table include all the necessary settings to manage VAT in Switzerland using the balance rate method.
You can choose how to handle VAT in your transactions:
- Break down VAT in each transaction
Before you start recording transactions, enter your VAT rates in the VAT Codes table and set "YES" in the Gross column. This way, each transaction will include a VAT breakdown, with the VAT amount displayed in the corresponding column. - Calculate balance rate VAT at the end of the period
VAT codes must be entered in the VAT calculation dialog, available in the Banana Accounting Plus extension. Transactions will be recorded with VAT-inclusive amounts, and there will be no breakdown of VAT amounts.
More information is available on the page VAT Report - Net tax Rate / Flat Rate Method.
At the end of the period, the software automatically calculates VAT using the balance rate method and generates a PDF preview of the official VAT report along with an XML file for the electronic submission of VAT data to the AFC.
The program includes many features to work efficiently and achieve professional results.
Some features require a subscription to the Advanced plan of Banana Accounting Plus, such as generating the VAT report template or the XML file, using the new Rules, Filter, and Temporary Sort Rows functions. Check out all the features of the Advanced plan.
Create your file
- Open the template with the Banana Accounting WebApp
- Using the File > File Properties command, set the period, your company name, and the base currency (you can create a budget and manage accounting in any currency you prefer).
- With the File > Save As command, save the file. It is useful to include your studio name and the year in the file name. For example, "Studio-Rossi-SA-20xx.ac2".
WARNING: If you close the browser without saving, you will lose the entered data. Always save the file on your computer.
Further information and insights:
Tutorial invoice with customer ledger | Revenue-based accounting | VAT
In this article
Tutorial invoice with customer ledger | Revenue-based accounting | VAT
Tutorial invoice with customer ledger | Revenue-based accounting | VAT
Banana Accounting Plus offers an innovative and professional method for creating invoices and automatically recording them in the accounting. The proposed tutorial template shows you how to record different types of invoices, from the simplest one to those with multiple items, and to test all the printing functions. If you want to create your own file based on this template, replace the example customer accounts in the Accounts table with your own data, enter the invoice items in the Transactions table, and the invoice is ready to be printed with or without a QR code for Switzerland. Open the template from our WebApp or from the program and save the file on your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open tutorial in WebAppTemplate documentation
Tutorial with a very simple and short chart of accounts, where we provide some recording examples to create invoices with VAT. The file also includes the Items table, where you can enter the data of the items or services to be invoiced. The data entered in the Items table is automatically retrieved in the Transactions table.
Create the file and test the Invoice functions
If you want to try out the invoice printing functions with VAT and QR code, you can start with this template.
- Open the template with the Banana Accounting Plus WebApp
- With the File > File and accounting properties command, set the period, your company name, and base currency.
- With the File > Save As command, save the file, for example as "Rossi-SA-20xx.ac2".
- In the Accounts table, enter the data of one of your customers. In the Addresses view, you can complete all address details (company name, address, phone and email contacts, country code and customer language).
- In the Transactions table, you will find various billing scenarios already recorded. You can delete the rows and enter the data of your invoice. By entering the Debit and Credit accounts, the invoice will be automatically posted.
- Select the Reports > Customers > Print invoices menu, click OK to preview the documents.
- To try out the different available invoice layouts, see the Invoice layouts page.
- To customize the invoices, see the Advanced input - Type column page.
You can find all the information about creating and printing invoices with QR code at the following webpage:
WARNING: If you close the browser without saving, you will lose the entered data. Always save the file to your computer.
To reopen the saved file, click on File > Open.
Some functions require a subscription to the Advanced plan of Banana Accounting Plus, such as using the new features for printing the VAT return sample from 2024, Rules, Filter and Temporary row sorting. See all the features of the Advanced plan.
Other Resources
Template preview
Invoices 2022
Basic Currency: CHF
Double-entry with VAT/Sales tax
| Group | Account | Description | Sum In |
|---|---|---|---|
| BALANCE SHEET | |||
| Assets | |||
| 1020 | Bank account | 1 | |
| 10 | Customers' register | 1 | |
| 1 | Total assets | 00 | |
| Liabilities | |||
| 2200 | VAT Due | 2 | |
| 2201 | VAT according to VAT report | 2 | |
| 297 | Profit for the period | 2 | |
| 2 | Total Liabilities | 00 | |
| PROFIT & LOSS STATEMENT | |||
| Revenue & Expenses | |||
| 3000 | Sales Revenue Product A | 4 | |
| 3001 | Sales Revenue Product B | 4 | |
| 3002 | Other sales revenue | 4 | |
| 3400 | Revenue from services | 4 | |
| 3800 | Discounts | 4 | |
| 4 | Total Revenue & Expenses | 02 | |
| 02 | Profit/Loss for Profit & Loss Statement | 297 | |
| 00 | Difference should be = 0 (blank cell) | ||
| Customers' Register | |||
| 1100 | Customer A | DEB | |
| 1101 | Customer B | DEB | |
| 1102 | Customer C | DEB | |
| 1103 | Customer D | DEB | |
| 1104 | Customer E | DEB | |
| DEB | Total | 10 |
| VAT Code | Description | %VAT |
|---|---|---|
| Explanations | ||
| V = Sales (200) | ||
| VS = Discount sales and services (235) | ||
| B = Acquisition tax (380) | ||
| M = Expenses for material and services (400) | ||
| I = Investments and other operating expenses (405) | ||
| K = Corrections (410, 415, 420) | ||
| Z = Not considered (910) | ||
| VAT codes information (do not modify) | ||
| id=vatcodes-che-2018.20211210 | ||
| Last update: 10.12.2021 | ||
| VAT Due | ||
| V0 | Exempt services (220) | |
| V0-E | Export services abroad (221) | |
| V0-T | Transfers in the reporting procedure (225) | |
| V0-N | Non-taxable services (230) | |
| Decrease of income from services, see discounts | ||
| V0-D | Various (280) | |
| V77 | Sales and services 7.7% | 7.70 |
| V80 | Sales and services 8.0% | 8.00 |
| V77-B | Sales and services 7.7% (chosen) | 7.70 |
| V80-B | Sales and services 8.0% (chosen) | 8.00 |
| V25-N | Sales and services 2.5% 2018 | 2.50 |
| V25 | Sales and services 2.5% 2017 | 2.50 |
| V37 | Sales and services 3.7% | 3.70 |
| V38 | Sales and services 3.8% | 3.80 |
| VS77 | Discount Sales and services 7.7% | 7.70 |
| VS80 | Discount Sales and services 8.0% | 8.00 |
| VS25-N | Discount Sales and services 2.5% 2018 | 2.50 |
| VS25 | Discount Sales and services 2.5% 2017 | 2.50 |
| VS37 | Discount Sales and services 3.7% | 3.70 |
| VS38 | Discount Sales and services 3.8% | 3.80 |
| Taxable turnover (299) | ||
| F1 | 1. Flat tax rate 2017 | |
| F2 | 2. Flat tax rate 2017 | |
| FS1 | Discount Sales and services 1. Flat tax rate 2017 | |
| FS2 | Discount Sales and services 2. Flat tax rate 2017 | |
| F3 | 1. Flat tax rate 2018 | |
| F4 | 2. Flat tax rate 2018 | |
| FS3 | Discount Sales and services 1. Flat tax rate 2018 | |
| FS4 | Discount Sales and services 2. Flat tax rate 2018 | |
| Total Flat tax rate (321-331) | ||
| B77 | Acquisition tax 7.7% (With VAT/Sales tax) | 7.70 |
| B80 | Acquisition tax 8% (With VAT/Sales tax) | 8.00 |
| B77-1 | Acquisition tax 7.7% (Without VAT/Sales tax) | 7.70 |
| B80-1 | Acquisition tax 8% (Without VAT/Sales tax) | 8.00 |
| B77-2 | Acquisition tax 7.7% (VAT/Sales tax amount) | 7.70 |
| B80-2 | Acquisition tax 8% (VAT/Sales tax amount) | 8.00 |
| Total Tax on purchases (380-381) | ||
| Total VAT Due (399) | ||
| Recoverable VAT | ||
| M0 | Exempt material- and service expenses | |
| I0 | Exempt investment and operating expenses | |
| M77 | Purchase of material and services 7.7% (With VAT/Sales tax) | 7.70 |
| M80 | Purchase of material and services 8.0% (With VAT/Sales tax) | 8.00 |
| M77-1 | Purchase of material and services 7.7% (Without VAT/Sales tax) | 7.70 |
| M80-1 | Purchase of material and services 8.0% (Without VAT/Sales tax) | 8.00 |
| M77-2 | Purchase of material and services 7.7% (VAT/Sales tax amount) | 7.70 |
| M80-2 | Purchase of material and services 8.0% (VAT/Sales tax amount) | 8.00 |
| M25 | Purchase of material and services 2.5% | 2.50 |
| M37 | Purchase of material and services 3.7% | 3.70 |
| M38 | Purchase of material and services 3.8% | 3.80 |
| Investment and operating expenses | ||
| I77 | Investment and operating expenses 7.7% | 7.70 |
| I77-2 | Investment and operating expenses 7.7% (VAT/Sales tax amount) | 7.70 |
| I80 | Investment and operating expenses 8.0% | 8.00 |
| I25 | Investment and operating expenses 2.5% | 2.50 |
| I37 | Investment and operating expenses 3.7% | 3.70 |
| I38 | Investment and operating expenses 3.8% | 3.80 |
| Corrections and adjustments | ||
| K77-A | Subsequent adjustment of prior tax 7.7% (410) | 7.70 |
| K80-A | Subsequent adjustment of prior tax 8 % (410) | 8.00 |
| K77-B | Corrections of prior tax 7.7% (415) | 7.70 |
| K80-B | Corrections of prior tax 8% (415) | 8.00 |
| K77-C | Reductions of the deduction of prior tax 7.7% (420) | 7.70 |
| K80-C | Reductions of the deduction of prior tax 8% (420) | 8.00 |
| F1050 | Tax computation according to form Nr. 1050 | |
| F1055 | Tax computation according to form Nr. 1055 | |
| Total Recoverable VAT (479) | ||
| Total VAT payable (500) or VAT credit (510) | ||
| Other financial flows | ||
| Z0-A | Subsidies, tourist taxes collected by the tourism offices, contributions to the institutions responsible for the elimination of waste and for the supply of water (let. a - c) | |
| Z0 | Gifts, dividends, compensation for damages etc. | |
| Not considered | ||
| Final total for control |
Sole proprietorship | VAT | SME
In this article
Sole proprietorship | VAT | SME
Sole proprietorship | VAT | SME
Model set up for sole proprietorships with VAT management, according to Swiss SME regulations. With automation features, you can import transactions directly from bank statements, and with one click prepare Account cards, Journal, Balance Sheets, VAT returns, invoices with QR code, reports to track due dates and print reminders. Open the template from our WebApp or from the program and save the file to your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
Template with SME chart of accounts, compliant with the rules established in the Swiss Code of Obligations (Art. 957 and following). Ideal for keeping accounts with an annual turnover of at least CHF 500,000.
The structure of the chart of accounts is in a step format and allows you to view the composition of the operating result also in intermediate stages.
- You can customize the accounts to suit your specific needs.
- By setting up the customer ledger, you have the possibility to issue invoices to your customers with the added benefit of having them automatically recorded in the accounting.
- The VAT Codes table is updated with the new 2024 VAT rates.
- To speed up data entry, you can use the bank statement import function together with Rules: for each imported transaction, enter a keyword (Rule) that completes all other elements of the entry (counter account, VAT code, cost center...). On subsequent imports, the program automatically completes any entry that contains the keyword, significantly reducing workload and minimizing errors.
Many automation features, such as bank statement import using Rules, the VAT return sample form with the new 2024 rates, the XML file for electronic VAT data submission, filtering, and many others, are included exclusively in the Advanced plan of Banana Accounting Plus.
Create your file
- Open the template with the Banana Accounting Plus WebApp
- With the File > File and accounting properties command, set the period, your company name, and base currency (you can do budgeting and accounting in any currency you prefer).
- With the File > Save As command, save the file. It’s helpful to include the company name and year in the file name. For example, "Rossi-SA-20xx.ac2".
WARNING: If you close the browser without saving, you will lose the entered data. Always save the file to your computer.
More information and insights:
In our Documentation you will find all the information and details to manage your accounting effectively:
Template preview
Company XXX
Accounting 2025
Basic Currency: CHF
Double-entry with VAT/Sales tax
| Group | Account | Description | Sum In | Gr1 |
|---|---|---|---|---|
| BALANCE SHEET | ||||
| ASSETS | ||||
| 1000 | Cash on hand | 100 | ||
| 1020 | Bank account | 100 | ||
| 100 | Cash and cash equivalents | 10 | 1 | |
| 1060 | Bonds and stocks | 106 | ||
| 106 | Short-term Assets listed in Stock Exchange | 10 | ||
| 1090 | Internal transfers | 109 | ||
| 1091 | Transfer account for salaries | 109 | ||
| 1099 | Amounts to be clarified | 109 | ||
| 109 | Transfer accounts | 10 | ||
| 1100 | Due from Clients or Debtors | 110 | ||
| 1109 | Provision for Doubtful Debts | 110 | ||
| 110 | Accounts receivable | 10 | ||
| 1140 | Advances and loans | 114 | ||
| 1176 | Withholding tax | 114 | ||
| 1180 | Receivables from social insurances and social security institutions | 114 | ||
| 1188 | Source tax | 114 | ||
| 1190 | Various short-term receivables | 114 | ||
| 1199 | Securities | 114 | ||
| 114 | Other short-term receivables | 10 | ||
| 1200 | Goods for resale | 120 | ||
| 1210 | Raw materials | 120 | ||
| 1220 | Auxiliary material | 120 | ||
| 1230 | Consumables | 120 | ||
| 1260 | Finished products | 120 | ||
| 1270 | In-process products | 120 | ||
| 1280 | Non-invoiced services | 120 | ||
| 120 | Inventories | 10 | 1 | |
| 1300 | Prepaid expenses | 130 | ||
| 1301 | Accrued income | 130 | ||
| 130 | Prepaid Expenses | 10 | 1 | |
| 10 | Current assets | 1 | 1 | |
| 1400 | Bonds and stocks | 140 | ||
| 1440 | Loans | 140 | ||
| 140 | Financial assets | 14 | ||
| 1480 | Investments | 148 | ||
| 148 | Investments | 14 | ||
| 1500 | Machinery | 150 | ||
| 1510 | Office furniture and equipment | 150 | ||
| 1520 | Office machinery, information and communication technology | 150 | ||
| 1530 | Motor vehicles | 150 | ||
| 1540 | Tools and equipment | 150 | ||
| 150 | Tangible assets | 14 | ||
| 1600 | Commercial buildings | 160 | ||
| 160 | Tangible fixed asset management | 14 | ||
| 14 | Fixed Assets | 1 | ||
| 1 | Total Assets | 00 | ||
| LIABILITIES | ||||
| 2000 | Suppliers or creditors | 200 | ||
| 2030 | Deposits received | 200 | ||
| 200 | Suppliers or creditors | 20 | 1 | |
| 2100 | Due to banks short/term | 210 | ||
| 2120 | Financial leasing commitments | 210 | ||
| 2140 | Other onerous debts | 210 | ||
| 210 | Short-term onorous debts | 20 | ||
| 2200 | VAT Due | 220 | ||
| 2201 | VAT according to VAT report | 220 | ||
| 2206 | Withholding tax | 220 | ||
| 2208 | Direct taxes | 220 | ||
| 2210 | Other short-term debts | 220 | ||
| 2270 | Social insurances and social security institutions | 220 | ||
| 2279 | Source tax | 220 | ||
| 220 | Other short-term debts | 20 | ||
| 2300 | Accrued expenses | 230 | ||
| 2301 | Next year's revenues collected | 230 | ||
| 2330 | Short-term provisions | 230 | ||
| 230 | Accruals and deferred income | 20 | ||
| 20 | Short-term third party capital | 2A | ||
| 2400 | Due to banks | 240 | ||
| 2420 | Financial leasing commitments | 240 | ||
| 2430 | Debenture loans | 240 | ||
| 2450 | Loans | 240 | ||
| 2451 | Mortgage | 240 | ||
| 240 | Long-term onorous debts | 24 | ||
| 2500 | Other long-term debts (non-onorous) | 250 | ||
| 250 | Other long-term debts | 24 | ||
| 2600 | Provisions | 260 | ||
| 260 | Provisions and similar statutory posts | 24 | ||
| 24 | Long-term third party capital | 2A | ||
| 2A | Third party capital | 2 | ||
| 2800 | Equity at the beginning of the financial year | 28 | ||
| 2850 | Private account | 28 | ||
| 2970 | Profit / Loss for the year | 28 | ||
| 2891 | Profit/loss for the period | 28 | ||
| 28 | Equity | 2 | ||
| 2 | Total liabilities | 00 | 1 | |
| PROFIT & LOSS STATEMENT | ||||
| 3000 | Earnings from own products | 30 | ||
| 3200 | Earnings from resale | 30 | ||
| 3400 | Earnings from services rendered | 30 | ||
| 3600 | Other revenues and services | 30 | ||
| 3710 | Own consumption | 30 | ||
| 3800 | Decrease in revenues | 30 | ||
| 3805 | Losses on accounts receivable, credit variation | 30 | ||
| 3809 | VAT flat tax rate | 30 | ||
| 30 | Net revenues from supplies and services | 3 | ||
| 3900 | Change in inventories of in-process products | 39 | ||
| 3901 | Change in inventories of finished products | 39 | ||
| 3940 | Non-invoiced services variations | 39 | ||
| 39 | Change in inventories and Non-invoiced services | 3 | ||
| 3 | Revenues from supplies and services | E1 | ||
| 4000 | Raw materials | 4 | ||
| 4200 | Expenses for goods for resale | 4 | ||
| 4400 | Third party expenses | 4 | ||
| 4500 | Energy consumption for production | 4 | ||
| 4900 | Reduction of costs | 4 | ||
| 4 | Costs for material, goods, services and energy | E1 | ||
| E1 | Gross operating result after deducting costs for materials and goods | E2 | ||
| 5000 | Salaries | 5 | ||
| 5700 | Contribution to old age insurance and unemployment | 5 | ||
| 5710 | Family equalization fund | 5 | ||
| 5720 | Contribution to pension funds | 5 | ||
| 5730 | Contribution to accident insurance | 5 | ||
| 5740 | Contribution to voluntary daily benefits insurance | 5 | ||
| 5790 | Source tax | 5 | ||
| 5800 | Other personnel expenses | 5 | ||
| 5810 | Training of personnel | 5 | ||
| 5820 | Travel and entertainment expenses effective | 5 | ||
| 5830 | Travel and entertainment expense allowance | 5 | ||
| 5900 | Temporary staff | 5 | ||
| 5 | Personnel expenses | E2 | ||
| E2 | Gross operating result after deducting personnel expenses | E3 | ||
| 6000 | Rental | 60 | ||
| 6040 | Cleaning of facilities | 60 | ||
| 60 | Rental | 6 | ||
| 6100 | Maintenance, repairs and replacement of tangible assets | 61 | ||
| 6105 | Leasing costs tangible assets | 61 | ||
| 61 | Maintenance, repairs and replacement of tangible assets | 6 | ||
| 6200 | Repairs | 62 | ||
| 6210 | Fuel | 62 | ||
| 6220 | Car insurance | 62 | ||
| 6260 | Car leasing and rental | 62 | ||
| 6270 | Car costs - private part | 62 | ||
| 6282 | Transportation expenses | 62 | ||
| 62 | Vehicle and transportation expenses | 6 | ||
| 6300 | Insurance for damage of items | 63 | ||
| 63 | Insurance for damage of items | 6 | ||
| 6402 | Electricity | 64 | ||
| 6410 | Heating expenses | 64 | ||
| 6430 | Water | 64 | ||
| 6460 | Garbage | 64 | ||
| 64 | Energy and disposal costs | 6 | ||
| 6500 | Office supplies | 65 | ||
| 6503 | Technical magazines, newspapers, periodicals | 65 | ||
| 6510 | Telephone / internet | 65 | ||
| 6511 | Hosting at third-party | 65 | ||
| 6513 | Postal charges | 65 | ||
| 6570 | IT charges including leasing | 65 | ||
| 6580 | Licenses and updates | 65 | ||
| 6583 | Consumables | 65 | ||
| 65 | Administrative and IT costs | 6 | ||
| 6600 | Advertising | 66 | ||
| 6642 | Gifts to customers | 66 | ||
| 66 | Advertising | 6 | ||
| 6700 | Various costs for the financial year | 67 | ||
| 67 | Various costs for the financial year | 6 | ||
| 6 | Other operating expenses, depreciation, value adjustments and financial results | E3 | ||
| E3 | Operating result before depreciation and value adjustments, financial results and taxes (EBITDA) | E4 | ||
| 6800 | Depreciation and value adjustments of fixed assets | 68 | ||
| 68 | Depreciation and value adjustments of fixed assets | E4 | ||
| E4 | Operating result before financial results and taxes (EBIT) | E5 | ||
| 6900 | Costs for bank interest | 69 | ||
| 6940 | Bank costs | 69 | ||
| 6950 | Financial revenue | 69 | ||
| 69 | Financial costs and revenue | E5 | ||
| E5 | Operating result before taxes (EBT) | E6 | ||
| 7000 | Non-operating revenue | 7 | ||
| 7010 | Non-operating costs | 7 | ||
| 7500 | Corporate real estate revenues | 7 | ||
| 7510 | Corporate real estate costs | 7 | ||
| 7 | Non-operating items | E6 | ||
| 8000 | Extraneous costs | 8 | ||
| 8100 | Extraneous revenue | 8 | ||
| 8500 | Extraordinary, unique costs or costs relating to other accounting periods | 8 | ||
| 8510 | Extraordinary, unique revenue or revenue relating to other accounting periods | 8 | ||
| 8 | Results of extraneous, extraordinary or unique character, or for other accounting periods | E6 | ||
| E6 | Profit or loss before taxes | E7 | ||
| 8900 | Direct taxes | 89 | ||
| 89 | Direct taxes | E7 | ||
| E7 | Annual profit or loss | 2891 | ||
| 00 | Difference should be = 0 (blank cell) | |||
| 1 | ||||
| COST CENTERS | ||||
| .PAC | Packaging A | INV | ||
| .RM | Raw materials A | INV | ||
| .AM | Auxiliairy materials A | INV | ||
| INV | Total inventories | |||
| ,MAN1 | Maintenance 1 | MAN | ||
| ,MAN2 | Maintenance 2 | MAN | ||
| ,MAN3 | Maintenance 3 | MAN | ||
| MAN | Total maintenance | |||
| ;PB1 | Publicity 1 | PU | ||
| ;PB2 | Publicity 2 | PU | ||
| PU | Total publicity | |||
| VAT Code | Description | %VAT |
|---|---|---|
| Explanations | ||
| V = Sales (200) | ||
| VS = Discount sales and services (235) | ||
| B = Acquisition tax (38x) | ||
| M = Expenses for material and services (400) | ||
| I = Investments and other operating expenses (405) | ||
| K = Corrections (410, 415, 420) | ||
| Z = Not considered (910) | ||
| VAT codes information (do not modify) | ||
| id=vatcodes-che-2024.20230614 | ||
| Last update: 14.06.2023 | ||
| VAT Due | ||
| V0 | Exempt services (220) | |
| V0-E | Export services abroad (221) | |
| V0-T | Transfers in the reporting procedure (225) | |
| V0-N | Non-taxable services (230) | |
| Decrease of income from services, see discounts | ||
| V0-D | Various (280) | |
| V77 | Sales and services 7.7% | 7.70 |
| V81 | Sales and services 8.1% | 8.10 |
| V77-B | Sales and services 7.7% (chosen) | 7.70 |
| V81-B | Sales and services 8.1% (chosen) | 8.10 |
| V25-N | Sales and services 2.5% | 2.50 |
| V26 | Sales and services 2.6% | 2.60 |
| V37 | Sales and services 3.7% | 3.70 |
| V38 | Sales and services 3.8% | 3.80 |
| VS77 | Discount Sales and services 7.7% | 7.70 |
| VS81 | Discount Sales and services 8.1% | 8.10 |
| VS25-N | Discount Sales and services 2.5% | 2.50 |
| VS26 | Discount Sales and services 2.6% | 2.60 |
| VS37 | Discount Sales and services 3.7% | 3.70 |
| VS38 | Discount Sales and services 3.8% | 3.80 |
| Taxable turnover (299) | ||
| F1 | 1. Flat tax rate 2024 | |
| F2 | 2. Flat tax rate 2024 | |
| FS1 | Discount Sales and services 1. Flat tax rate 2024 | |
| FS2 | Discount Sales and services 2. Flat tax rate 2024 | |
| F3 | 1. Flat tax rate 2018 | |
| F4 | 2. Flat tax rate 2018 | |
| FS3 | Discount Sales and services 1. Flat tax rate 2018 | |
| FS4 | Discount Sales and services 2. Flat tax rate 2018 | |
| Total Flat tax rate (322-333) | ||
| B77 | Acquisition tax 7.7% (With VAT/Sales tax) | 7.70 |
| B77-1 | Acquisition tax 7.7% (Without VAT/Sales tax) | 7.70 |
| B77-2 | Acquisition tax 7.7% (VAT/Sales tax amount) | 7.70 |
| B81 | Acquisition tax 8.1% (With VAT/Sales tax) | 8.10 |
| B81-1 | Acquisition tax 8.1% (Without VAT/Sales tax) | 8.10 |
| B81-2 | Acquisition tax 8.1% (VAT/Sales tax amount) | 8.10 |
| Total Tax on purchases (382-383) | ||
| Total VAT Due (399) | ||
| Recoverable VAT | ||
| M0 | Exempt material- and service expenses | |
| I0 | Exempt investment and operating expenses | |
| M77 | Purchase of material and services 7.7% (With VAT/Sales tax) | 7.70 |
| M77-1 | Purchase of material and services 7.7% (Without VAT/Sales tax) | 7.70 |
| M77-2 | Purchase of material and services 7.7% (VAT/Sales tax amount) | 7.70 |
| M81 | Purchase of material and services 8.1% (With VAT/Sales tax) | 8.10 |
| M81-1 | Purchase of material and services 8.1% (Without VAT/Sales tax) | 8.10 |
| M81-2 | Purchase of material and services 8.1% (VAT/Sales tax amount) | 8.10 |
| M25 | Purchase of material and services 2.5% | 2.50 |
| M26 | Purchase of material and services 2.6% | 2.60 |
| M37 | Purchase of material and services 3.7% | 3.70 |
| M38 | Purchase of material and services 3.8% | 3.80 |
| Investment and operating expenses | ||
| I77 | Investment and operating expenses 7.7% | 7.70 |
| I77-1 | Investment and operating expenses 7.7% (Without VAT/Sales tax) | 7.70 |
| I77-2 | Investment and operating expenses 7.7% (VAT/Sales tax amount) | 7.70 |
| I81 | Investment and operating expenses 8.1% | 8.10 |
| I81-1 | Investment and operating expenses 8.1% (Without VAT/Sales tax) | 8.10 |
| I81-2 | Investment and operating expenses 8.1% (VAT/Sales tax amount) | 8.10 |
| I25 | Investment and operating expenses 2.5% | 2.50 |
| I26 | Investment and operating expenses 2.6% | 2.60 |
| I37 | Investment and operating expenses 3.7% | 3.70 |
| I38 | Investment and operating expenses 3.8% | 3.80 |
| Corrections and adjustments | ||
| K77-A | Subsequent adjustment of prior tax 7.7% (410) | 7.70 |
| K81-A | Subsequent adjustment of prior tax 8.1 % (410) | 8.10 |
| K77-B | Corrections of prior tax 7.7% (415) | 7.70 |
| K81-B | Corrections of prior tax 8.1% (415) | 8.10 |
| K77-C | Reductions of the deduction of prior tax 7.7% (420) | 7.70 |
| K81-C | Reductions of the deduction of prior tax 8.1% (420) | 8.10 |
| F1050 | Tax computation according to form Nr. 1050 | |
| F1055 | Tax computation according to form Nr. 1055 | |
| Total Recoverable VAT (479) | ||
| Total VAT payable (500) or VAT credit (510) | ||
| Other financial flows | ||
| Z0-A | Subsidies, tourist taxes collected by the tourism offices, contributions to the institutions responsible for the elimination of waste and for the supply of water (let. a - c) | |
| Z0 | Gifts, dividends, compensation for damages etc. | |
| Not considered | ||
| Final total for control | ||
Einzelunternehmen | KMU | MWST-Abrechnung nach vereinbarten Entgelten
In this article
Einzelunternehmen | KMU | MWST-Abrechnung nach vereinbarten Entgelten
Einzelunternehmen | KMU | MWST-Abrechnung nach vereinbarten Entgelten
Ideales Modell für die Buchhaltung eines Einzelunternehmens mit MWST-Abrechnung nach vereinbarten Entgelten. Im Kontenplan wird das Postenbuch Kunden/Lieferanten nach dem Kompetenzprinzip geführt. Dank der Funktionen der integrierten Fakturierung kannst du die gleichen Daten, die du für die Rechnungserstellung eingibst, nutzen, um Rechnungen mit QR-Code zu erstellen und auszudrucken. Es stehen zahlreiche Funktionen zur Verfügung, um die Eingabe von Buchhaltungsdaten zu beschleunigen und automatisch die Bilanz, die Gewinn- und Verlustrechnung, die MWST-Abrechnungen mit der entsprechenden Übermittlung der MWST-Daten an die ESTV und vieles mehr zu erhalten. Mit der Liquiditäts- und Budgetplanung kannst du die finanzielle und wirtschaftliche Lage deines Unternehmens im Blick behalten. Öffne das Modell mit der WebApp oder direkt über das Programm und speichere die Datei auf deinem Computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate preview
Basiswährung: CHF
Doppelte Buchhaltung mit MWST/USt
| Gruppe | Konto | Beschreibung | Summ. in |
|---|---|---|---|
| BILANZ | |||
| AKTIVEN | |||
| 1000 | Kasse | 100 | |
| 1020 | Bankguthaben | 100 | |
| 1045 | Kreditkarten / Debitkarten | 100 | |
| 100 | Flüssige Mittel | 10 | |
| 1060 | Wertschriften | 106 | |
| 106 | Kurzfristig gehaltene Aktiven mit Börsenkurs | 10 | |
| 1090 | Transferkonto | 109 | |
| 1091 | Lohndurchlaufkonto | 109 | |
| 1099 | Abklärungskonto | 109 | |
| 109 | Transferkonto | 10 | |
| 100A | Summe Debitoren | 110 | |
| 1100 | Forderungen aus Lieferungen und Leistungen (Debitoren) | 110 | |
| 1109 | Delkredere | 110 | |
| 110 | Forderungen aus Lieferungen und Leistungen | 10 | |
| 1140 | Vorschüsse und Darlehen | 114 | |
| 1176 | Verrechnungssteuer | 114 | |
| 1179 | Quellensteuer | 114 | |
| 1180 | Kontokorrent AHV, IV, EO, ALV | 114 | |
| 1190 | Sonstige kurzfristige Forderungen | 114 | |
| 1191 | Kautionen | 114 | |
| 114 | Übrige kurzfristige Forderungen | 10 | |
| 1200 | Handelswaren | 120 | |
| 1210 | Rohstoffe | 120 | |
| 1230 | Hilfsmaterial | 120 | |
| 1231 | Verbrauchsmaterial | 120 | |
| 1250 | Handelswaren in Konsignation | 120 | |
| 1260 | Fertige Erzeugnisse | 120 | |
| 1270 | Unfertige Erzeugnisse | 120 | |
| 1280 | Nicht fakturierte Dienstleistungen | 120 | |
| 120 | Vorräte und nicht fakturierte Dienstleistungen | 10 | |
| 1300 | Bezahlter Aufwand des Folgejahres | 130 | |
| 1301 | Noch nicht erhaltener Ertrag | 130 | |
| 130 | Aktive Rechnungsabgrenzungen | 10 | |
| 10 | Umlaufvermögen | 1 | |
| 1400 | Wertschriften | 140 | |
| 1440 | Darlehen | 140 | |
| 1441 | Hypotheken | 140 | |
| 140 | Finanzanlagen | 14 | |
| 1480 | Beteiligungen | 148 | |
| 148 | Beteiligungen | 14 | |
| 1500 | Maschinen und Apparate | 150 | |
| 1510 | Mobiliar und Einrichtungen | 150 | |
| 1520 | Büromaschinen, Informatik, Kommunikationstechnologie | 150 | |
| 1530 | Fahrzeuge | 150 | |
| 1540 | Werkzeuge und Geräte | 150 | |
| 150 | Mobile Sachanlagen | 14 | |
| 1600 | Geschäftsliegenschaften | 160 | |
| 160 | Immobile Sachanlagen | 14 | |
| 14 | Anlagevermögen | 1 | |
| 1 | Total Aktiven | 00 | |
| PASSIVEN | |||
| 2000 | Verbindlichkeiten aus Lieferungen und Leistungen (Kreditoren) | 200 | |
| 2030 | Anzahlungen von Dritten | 200 | |
| 200A | Summe Kreditoren | 200 | |
| 200 | Verbindlichkeiten aus Lieferungen und Leistungen | 20 | |
| 2100 | Bankverbindlichkeiten | 210 | |
| 2120 | Verbindlichkeiten aus Finanzierungsleasing | 210 | |
| 2140 | Übrige verzinsliche Verbindlichkeiten | 210 | |
| 210 | Kurzfristige verzinsliche Verbindlichkeiten | 20 | |
| 2200 | Geschuldete MWST (Umsatzsteuer) | 220 | |
| 2201 | Abrechnungskonto MWST | 220 | |
| 2206 | Verrechnungssteuer | 220 | |
| 2208 | Direkte Steuern | 220 | |
| 2209 | Quellensteuer | 220 | |
| 2210 | Sonstige kurzfristige Verbindlichkeiten | 220 | |
| 2270 | Kontokorrent AHV, IV, EO, ALV | 220 | |
| 220 | Übrige kurzfristige Verbindlichkeiten | 20 | |
| 2300 | Noch nicht bezahlter Aufwand | 230 | |
| 2301 | Erhaltener Ertrag des Folgejahres | 230 | |
| 2330 | Kurzfristige Rückstellungen | 230 | |
| 230 | Passive Rechnungsabgrenzungen und kurzfristige Rückstellungen | 20 | |
| 20 | Kurzfristiges Fremdkapital | 2A | |
| 2400 | Bankverbindlichkeiten | 240 | |
| 2420 | Verbindlichkeiten aus Finanzierungsleasing | 240 | |
| 2430 | Obligationenanleihen | 240 | |
| 2450 | Darlehen | 240 | |
| 2451 | Hypotheken | 240 | |
| 240 | Langfristige verzinsliche Verbindlichkeiten | 24 | |
| 2500 | Übrige langfristige Verbindlichkeiten (unverzinslich) | 250 | |
| 250 | Übrige langfristige Verbindlichkeiten | 24 | |
| 2600 | Rückstellungen | 260 | |
| 260 | Langfristige Rückstellungen sowie vom Gesetz vorgesehene ähnliche Positionen | 24 | |
| 24 | Langfristiges Fremdkapital | 2A | |
| 2A | Fremdkapital | 2 | |
| 2800 | Eigenkapital zu Beginn des Geschäftsjahres | 28 | |
| 2820 | Kapitaleinlagen und Kapitalrückzüge | 28 | |
| 2850 | Privat | 28 | |
| 2891 | Jahresgewinn oder Jahresverlust | 28 | |
| 28 | Eigenkapital | 2 | |
| 2 | Total Passiven | 00 | |
| ERFOLGSRECHNUNG | |||
| 3000 | Produktionserlöse | 30 | |
| 3200 | Handelserlöse | 30 | |
| 3400 | Dienstleistungserlöse | 30 | |
| 3600 | Übrige Erlöse aus Lieferungen und Leistungen | 30 | |
| 3700 | Eigenleistungen | 30 | |
| 3710 | Eigenverbrauch | 30 | |
| 3800 | Erlösminderungen | 30 | |
| 3805 | Verluste Forderungen (Debitoren), Veränderung Delkredere | 30 | |
| 3809 | MWST Saldosteuersatz | 30 | |
| 3810 | Kredit-/Debitkartenkommissionen | 30 | |
| 30 | Nettoerlöse aus Lieferungen und Leistungen | 3 | |
| 3900 | Bestandsänderungen fertige Erzeugnisse | 39 | |
| 3901 | Bestandsänderungen unfertige Erzeugnisse | 39 | |
| 3940 | Bestandsänderungen nicht fakturierte Dienstleistungen | 39 | |
| 39 | Bestandesänderungen an Erzeugnissen sowie an nicht fakturierten Dienstleistungen | 3 | |
| 3 | Betrieblicher Ertrag aus Lieferungen und Leistungen | E1 | |
| 4000 | Materialaufwand Produktion | 4 | |
| 4200 | Handelswarenaufwand | 4 | |
| 4400 | Aufwand für bezogene Dienstleistungen | 4 | |
| 4500 | Energieaufwand zur Leistungserstellung | 4 | |
| 4800 | Aufwandminderungen | 4 | |
| 4 | Aufwand für Material, Handelswaren, Dienstleistungen und Energie | E1 | |
| E1 | Bruttoergebnis nach Material- und Warenaufwand | E2 | |
| 5000 | Lohnaufwand | 5 | |
| 5701 | AHV, IV, EO Inhaber | 5 | |
| 5710 | FAK | 5 | |
| 5720 | Vorsorgeeinrichtungen | 5 | |
| 5730 | Unfallversicherung | 5 | |
| 5740 | Krankentaggeldversicherung | 5 | |
| 5790 | Quellensteuer | 5 | |
| 5800 | Übriger Personalaufwand | 5 | |
| 5830 | Pauschalspesen Personal | 5 | |
| 5900 | Leistungen Dritter | 5 | |
| 5 | Personalaufwand | E2 | |
| E2 | Bruttoergebnis nach Personalaufwand | E3 | |
| 6000 | Raumaufwand | 60 | |
| 6040 | Reinigung Lokalitäten | 60 | |
| 60 | Raumaufwand | 6 | |
| 6100 | Unterhalt, Reparaturen, Ersatz mobile Sachanlagen | 61 | |
| 6105 | Leasingaufwand mobile Sachanlagen | 61 | |
| 61 | Unterhalt, Reparaturen, Ersatz (URE); Leasing mobile Sachanlagen | 6 | |
| 6200 | Reparaturen | 62 | |
| 6210 | Betriebsstoffe | 62 | |
| 6220 | Haftpflichtversicherung | 62 | |
| 6260 | Fahrzeugleasing | 62 | |
| 6270 | Privatanteile Fahrzeugaufwand | 62 | |
| 6280 | Transportaufwand | 62 | |
| 62 | Fahrzeug- und Transportaufwand | 6 | |
| 6300 | Sachversicherungen, Abgaben, Gebühren, Bewilligungen | 63 | |
| 63 | Sachversicherungen, Abgaben, Gebühren, Bewilligungen | 6 | |
| 6402 | Lichtstrom | 64 | |
| 6410 | Erdgas | 64 | |
| 6430 | Wasser | 64 | |
| 6460 | Kehrichtabfuhr | 64 | |
| 64 | Energie- und Entsorgungsaufwand | 6 | |
| 6500 | Büromaterial | 65 | |
| 6503 | Fachliteratur, Zeitungen, Zeitschriften | 65 | |
| 6510 | Telefon | 65 | |
| 6512 | Internet | 65 | |
| 6513 | Porti | 65 | |
| 6570 | Informatikaufwand inkl. Leasing | 65 | |
| 6580 | Lizenzaufwendungen/Update | 65 | |
| 6583 | Verbrauchsmaterial | 65 | |
| 65 | Verwaltungs- und Informatikaufwand | 6 | |
| 6600 | Werbeaufwand | 66 | |
| 6642 | Kundengeschenke | 66 | |
| 66 | Werbeaufwand | 6 | |
| 6700 | Sonstiger betrieblicher Aufwand | 67 | |
| 67 | Sonstiger betrieblicher Aufwand | 6 | |
| 6 | Übriger betrieblicher Aufwand | E3 | |
| E3 | Betriebliches Ergebnis vor Abschreibungen und Wertberichtigungen, Finanzerfolg und Steuern (EBITDA) | E4 | |
| 6800 | Abschreibungen und Wertberichtigungen auf Positionen des Anlagevermögens | 68 | |
| 68 | Abschreibungen und Wertberichtigungen auf Positionen des Anlagevermögens | E4 | |
| E4 | Betriebliches Ergebnis vor Finanzerfolg und Steuern (EBIT) | E5 | |
| 6900 | Bankkreditzinsaufwand | 69 | |
| 6940 | Bankspesen | 69 | |
| 6950 | Erträge aus Bankguthaben | 69 | |
| 69 | Finanzaufwand und Finanzertrag | E5 | |
| E5 | Betriebliches Ergebnis vor Steuern (EBT) | E6 | |
| 7000 | Ertrag Nebenbetrieb | 7 | |
| 7010 | Aufwand Nebenbetrieb | 7 | |
| 7500 | Ertrag betriebliche Liegenschaft | 7 | |
| 7510 | Aufwand betriebliche Liegenschaft | 7 | |
| 7 | Betrieblicher Nebenerfolg | E6 | |
| 8000 | Betriebsfremder Aufwand | 8 | |
| 8100 | Betriebsfremder Ertrag | 8 | |
| 8500 | Ausserordentlicher, einmaliger oder periodenfremder Aufwand | 8 | |
| 8510 | Ausserordentlicher, einmaliger oder periodenfremder Ertrag | 8 | |
| 8 | Betriebsfremder, ausserordentlicher, einmaliger oder periodenfremder Aufwand und Ertrag | E6 | |
| E6 | Jahresgewinn oder Jahresverlust vor Steuern | E7 | |
| 8900 | Direkte Steuern | 89 | |
| 89 | Direkte Steuern | E7 | |
| E7 | Jahresgewinn oder Jahresverlust | 2891 | |
| 00 | Differenz muss = 0 sein | ||
| DEBITOREN | |||
| 110001 | Urs Weisshaupt | DEB1 | |
| 110002 | Susanne Müller | DEB1 | |
| 110003 | Peter Schmid | DEB1 | |
| DEB1 | Total Debitoren | 100A | |
| KREDITOREN | |||
| 200001 | Firma 1 | KRE1 | |
| 200002 | Firma 2 | KRE1 | |
| 200003 | Firma 3 | KRE1 | |
| KRE1 | Total Kreditoren | 200A | |
| KOSTENSTELLEN | |||
| .HAN | Handelswaren A | VOR | |
| .ROH | Rohstoffe A | VOR | |
| .WER | Werkstoffe A | VOR | |
| VOR | Total Vorräte | ||
| ,UN1 | Unterhalt 1 | UN | |
| ,UN2 | Unterhalt 2 | UN | |
| ,UN3 | Unterhalt 3 | UN | |
| UN | Total Unterhalt | ||
| ;WE1 | Werbeaufwand 1 | WER | |
| ;WE2 | Werbeaufwand 2 | WER | |
| WER | Total Werbeaufwand |
| MwSt/USt-Code | Beschreibung | MwSt/USt-% |
|---|---|---|
| Erläuterungen | ||
| V = Umsatz Verkauf (200) | ||
| VS = Skonto Verkauf und Dienstleistungen (235) | ||
| B = Bezugsteuer (38x) | ||
| M = Material- und Dienstleistungsaufwand (400) | ||
| I = Investitionen und übrigem Betriebsaufwand (405) | ||
| K = Korrekturen und Kürzungen (410, 415, 420) | ||
| Z = Nicht-Entgelte (910) | ||
| MwSt/USt-Codes-Informationen (nicht bearbeiten) | ||
| id=vatcodes-chd-2024.20230614 | ||
| Letzte Aktualisierung: 14.06.2023 | ||
| Umsatzsteuer (Schuld) | ||
| V0 | Von der Steuer befreite Leistungen, u.a. Exporte (220) | |
| V0-E | Leistungen im Ausland (221) | |
| V0-T | Übertragung im Meldeverfahren (225) | |
| V0-N | Nicht steuerbare Leistungen (230) | |
| Entgeltminderungen siehe Skonti | ||
| V0-D | Diverses (280) | |
| V77 | Verkauf und Dienstleistungen 7.7% | 7.70 |
| V81 | Verkauf und Dienstleistungen 8.1% | 8.10 |
| V77-B | Verkauf und Dienstleistungen 7.7% (optiert) | 7.70 |
| V81-B | Verkauf und Dienstleistungen 8.1% (optiert) | 8.10 |
| V25-N | Verkauf und Dienstleistungen 2.5% | 2.50 |
| V26 | Verkauf und Dienstleistungen 2.6% | 2.60 |
| V37 | Verkauf und Dienstleistungen 3.7% | 3.70 |
| V38 | Verkauf und Dienstleistungen 3.8% | 3.80 |
| VS77 | Skonto Verkauf und Dienstleistungen 7.7% | 7.70 |
| VS81 | Skonto Verkauf und Dienstleistungen 8.1% | 8.10 |
| VS25-N | Skonto Verkauf und Dienstleistungen 2.5% | 2.50 |
| VS26 | Skonto Verkauf und Dienstleistungen 2.6% | 2.60 |
| VS37 | Skonto Verkauf und Dienstleistungen 3.7% | 3.70 |
| VS38 | Skonto Verkauf und Dienstleistungen 3.8% | 3.80 |
| Steuerbarer Gesamtumsatz (299) | ||
| F1 | 1. Saldosteuersatz 2024 | |
| F2 | 2. Saldosteuersatz 2024 | |
| FS1 | Skonto Verkauf und Dienstleistungen 1. Saldosteuersatz 2024 | |
| FS2 | Skonto Verkauf und Dienstleistungen 2. Saldosteuersatz 2024 | |
| F3 | 1. Saldosteuersatz 2018 | |
| F4 | 2. Saldosteuersatz 2018 | |
| FS3 | Skonto Verkauf und Dienstleistungen 1. Saldosteuersatz 2018 | |
| FS4 | Skonto Verkauf und Dienstleistungen 2. Saldosteuersatz 2018 | |
| Total Saldosteuersatz (322-333) | ||
| B77 | Bezugsteuer 7.7% (inklusive MwSt/USt) | 7.70 |
| B77-1 | Bezugsteuer 7.7% (exklusive MwSt/USt) | 7.70 |
| B77-2 | Bezugsteuer 7.7% (MwSt/USt-Betrag) | 7.70 |
| B81 | Bezugsteuer 8.1% (inklusive MwSt/USt) | 8.10 |
| B81-1 | Bezugsteuer 8.1% (exklusive MwSt/USt) | 8.10 |
| B81-2 | Bezugsteuer 8.1% (MwSt/USt-Betrag) | 8.10 |
| Total Bezugsteuer (382-383) | ||
| Total geschuldete Steuer (399) | ||
| Vorsteuer (Guthaben) | ||
| M0 | Befreite Material- und Dienstleistungsaufwand | |
| I0 | Befreite Investition und Betriebsaufwand | |
| M77 | Material- und Dienstleistungsaufwand 7.7% (inklusive MwSt/USt) | 7.70 |
| M77-1 | Material- und Dienstleistungsaufwand 7.7% (exklusive MwSt/USt) | 7.70 |
| M77-2 | Material- und Dienstleistungsaufwand 7.7% (MwSt/USt-Betrag) | 7.70 |
| M81 | Material- und Dienstleistungsaufwand 8.1% (inklusive MwSt/USt) | 8.10 |
| M81-1 | Material- und Dienstleistungsaufwand 8.1% (exklusive MwSt/USt) | 8.10 |
| M81-2 | Material- und Dienstleistungsaufwand 8.1% (MwSt/USt-Betrag) | 8.10 |
| M25 | Material- und Dienstleistungsaufwand 2.5% | 2.50 |
| M26 | Material- und Dienstleistungsaufwand 2.6% | 2.60 |
| M37 | Material- und Dienstleistungsaufwand 3.7% | 3.70 |
| M38 | Material- und Dienstleistungsaufwand 3.8% | 3.80 |
| Investition und Betriebsaufwand | ||
| I77 | Investition und Betriebsaufwand 7.7% | 7.70 |
| I77-1 | Investition und Betriebsaufwand 7.7% (exklusive MwSt/USt) | 7.70 |
| I77-2 | Investition und Betriebsaufwand 7.7% (MwSt/USt-Betrag) | 7.70 |
| I81 | Investition und Betriebsaufwand 8.1% | 8.10 |
| I81-1 | Investition und Betriebsaufwand 8.1% (exklusive MwSt/USt) | 8.10 |
| I81-2 | Investition und Betriebsaufwand 8.1% (MwSt/USt-Betrag) | 8.10 |
| I25 | Investition und Betriebsaufwand 2.5% | 2.50 |
| I26 | Investition und Betriebsaufwand 2.6% | 2.60 |
| I37 | Investition und Betriebsaufwand 3.7% | 3.70 |
| I38 | Investition und Betriebsaufwand 3.8% | 3.80 |
| Korrekturen und Kürzungen | ||
| K77-A | Einlageentsteuerung 7.7% (410) | 7.70 |
| K81-A | Einlageentsteuerung 8.1% (410) | 8.10 |
| K77-B | Vorsteuerkorrekturen 7.7% (415) | 7.70 |
| K81-B | Vorsteuerkorrekturen 8.1% (415) | 8.10 |
| K77-C | Vorsteuerkürzungen 7.7% (420) | 7.70 |
| K81-C | Vorsteuerkürzungen 8.1% (420) | 8.10 |
| F1050 | Steueranrechnung gemäss Formular Nr. 1050 | |
| F1055 | Steueranrechnung gemäss Formular Nr. 1055 | |
| Total Vorsteuer (479) | ||
| Total zu bezahlen (500) oder Guthaben (510) | ||
| Andere Mittelflüsse | ||
| Z0-A | Subventionen, durch Kurvereine eingenommene Tourismusabgaben, Entsorgungs-und Wasserwerkbeiträge (Bst. a-c) | |
| Z0 | Spenden, Dividenden, Schadenersatz usw. | |
| Nicht-Entgelte | ||
| Total der Kontrolle | ||
Einzelunternehmen | KMU | MWST-Abrechnung nach vereinnahmten Entgelten | mit Kostenstellen
In this article
Einzelunternehmen | KMU | MWST-Abrechnung nach vereinnahmten Entgelten | mit Kostenstellen
Einzelunternehmen | KMU | MWST-Abrechnung nach vereinnahmten Entgelten | mit Kostenstellen
Ideales Modell für die Buchhaltung eines Einzelunternehmens mit MWST-Abrechnung nach vereinnahmten Entgelten. Im Kontenplan sind die Kunden-/Lieferantenkonten mit der KS3 Kosten- und Profitstellen verknüpft. In der Tabelle Buchungen kannst du die Rechnungsdaten wie normale Buchungen eingeben und mit dem QR-Code ausdrucken. Automatisch erhältst du die Bilanz, die Gewinn- und Verlustrechnung, MWST-Abrechnungen und viele weitere Berichte, die dir helfen, deine steuerlichen Verpflichtungen zu erfüllen und die finanzielle sowie wirtschaftliche Lage deines Unternehmens im Blick zu behalten. Du kannst Liquiditätsprognosen und Budgets erstellen. Öffne das Modell über unsere WebApp oder die Software und speichere die Datei auf deinem Computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate preview
Basiswährung: CHF
Doppelte Buchhaltung mit MWST/USt
| Gruppe | Konto | Beschreibung | Summ. in |
|---|---|---|---|
| BILANZ | |||
| AKTIVEN | |||
| 1000 | Kasse | 100 | |
| 1020 | Bankguthaben | 100 | |
| 1045 | Kreditkarten / Debitkarten | 100 | |
| 100 | Flüssige Mittel | 10 | |
| 1060 | Wertschriften | 106 | |
| 106 | Kurzfristig gehaltene Aktiven mit Börsenkurs | 10 | |
| 1090 | Transferkonto | 109 | |
| 1091 | Lohndurchlaufkonto | 109 | |
| 1099 | Abklärungskonto | 109 | |
| 109 | Transferkonto | 10 | |
| 1100 | Forderungen aus Lieferungen und Leistungen (Debitoren) | 110 | |
| 1109 | Delkredere | 110 | |
| 110 | Forderungen aus Lieferungen und Leistungen | 10 | |
| 1140 | Vorschüsse und Darlehen | 114 | |
| 1176 | Verrechnungssteuer | 114 | |
| 1179 | Quellensteuer | 114 | |
| 1180 | Kontokorrent AHV, IV, EO, ALV | 114 | |
| 1190 | Sonstige kurzfristige Forderungen | 114 | |
| 1191 | Kautionen | 114 | |
| 114 | Übrige kurzfristige Forderungen | 10 | |
| 1200 | Handelswaren | 120 | |
| 1210 | Rohstoffe | 120 | |
| 1230 | Hilfsmaterial | 120 | |
| 1231 | Verbrauchsmaterial | 120 | |
| 1250 | Handelswaren in Konsignation | 120 | |
| 1260 | Fertige Erzeugnisse | 120 | |
| 1270 | Unfertige Erzeugnisse | 120 | |
| 1280 | Nicht fakturierte Dienstleistungen | 120 | |
| 120 | Vorräte und nicht fakturierte Dienstleistungen | 10 | |
| 1300 | Bezahlter Aufwand des Folgejahres | 130 | |
| 1301 | Noch nicht erhaltener Ertrag | 130 | |
| 130 | Aktive Rechnungsabgrenzungen | 10 | |
| 10 | Umlaufvermögen | 1 | |
| 1400 | Wertschriften | 140 | |
| 1440 | Darlehen | 140 | |
| 1441 | Hypotheken | 140 | |
| 140 | Finanzanlagen | 14 | |
| 1480 | Beteiligungen | 148 | |
| 148 | Beteiligungen | 14 | |
| 1500 | Maschinen und Apparate | 150 | |
| 1510 | Mobiliar und Einrichtungen | 150 | |
| 1520 | Büromaschinen, Informatik, Kommunikationstechnologie | 150 | |
| 1530 | Fahrzeuge | 150 | |
| 1540 | Werkzeuge und Geräte | 150 | |
| 150 | Mobile Sachanlagen | 14 | |
| 1600 | Geschäftsliegenschaften | 160 | |
| 160 | Immobile Sachanlagen | 14 | |
| 14 | Anlagevermögen | 1 | |
| 1 | Total Aktiven | 00 | |
| PASSIVEN | |||
| 2000 | Verbindlichkeiten aus Lieferungen und Leistungen (Kreditoren) | 200 | |
| 2030 | Anzahlungen von Dritten | 200 | |
| 200 | Verbindlichkeiten aus Lieferungen und Leistungen | 20 | |
| 2100 | Bankverbindlichkeiten | 210 | |
| 2120 | Verbindlichkeiten aus Finanzierungsleasing | 210 | |
| 2140 | Übrige verzinsliche Verbindlichkeiten | 210 | |
| 210 | Kurzfristige verzinsliche Verbindlichkeiten | 20 | |
| 2200 | Geschuldete MWST (Umsatzsteuer) | 220 | |
| 2201 | Abrechnungskonto MWST | 220 | |
| 2206 | Verrechnungssteuer | 220 | |
| 2208 | Direkte Steuern | 220 | |
| 2209 | Quellensteuer | 220 | |
| 2210 | Sonstige kurzfristige Verbindlichkeiten | 220 | |
| 2270 | Kontokorrent AHV, IV, EO, ALV | 220 | |
| 220 | Übrige kurzfristige Verbindlichkeiten | 20 | |
| 2300 | Noch nicht bezahlter Aufwand | 230 | |
| 2301 | Erhaltener Ertrag des Folgejahres | 230 | |
| 2330 | Kurzfristige Rückstellungen | 230 | |
| 230 | Passive Rechnungsabgrenzungen und kurzfristige Rückstellungen | 20 | |
| 20 | Kurzfristiges Fremdkapital | 2A | |
| 2400 | Bankverbindlichkeiten | 240 | |
| 2420 | Verbindlichkeiten aus Finanzierungsleasing | 240 | |
| 2430 | Obligationenanleihen | 240 | |
| 2450 | Darlehen | 240 | |
| 2451 | Hypotheken | 240 | |
| 240 | Langfristige verzinsliche Verbindlichkeiten | 24 | |
| 2500 | Übrige langfristige Verbindlichkeiten (unverzinslich) | 250 | |
| 250 | Übrige langfristige Verbindlichkeiten | 24 | |
| 2600 | Rückstellungen | 260 | |
| 260 | Langfristige Rückstellungen sowie vom Gesetz vorgesehene ähnliche Positionen | 24 | |
| 24 | Langfristiges Fremdkapital | 2A | |
| 2A | Fremdkapital | 2 | |
| 2800 | Eigenkapital zu Beginn des Geschäftsjahres | 28 | |
| 2820 | Kapitaleinlagen und Kapitalrückzüge | 28 | |
| 2850 | Privat | 28 | |
| 2891 | Jahresgewinn oder Jahresverlust | 28 | |
| 28 | Eigenkapital | 2 | |
| 2 | Total Passiven | 00 | |
| ERFOLGSRECHNUNG | |||
| 3000 | Produktionserlöse | 30 | |
| 3200 | Handelserlöse | 30 | |
| 3400 | Dienstleistungserlöse | 30 | |
| 3600 | Übrige Erlöse aus Lieferungen und Leistungen | 30 | |
| 3700 | Eigenleistungen | 30 | |
| 3710 | Eigenverbrauch | 30 | |
| 3800 | Erlösminderungen | 30 | |
| 3805 | Verluste Forderungen (Debitoren), Veränderung Delkredere | 30 | |
| 3809 | MWST Saldosteuersatz | 30 | |
| 3810 | Kredit-/Debitkartenkommissionen | 30 | |
| 30 | Nettoerlöse aus Lieferungen und Leistungen | 3 | |
| 3900 | Bestandsänderungen fertige Erzeugnisse | 39 | |
| 3901 | Bestandsänderungen unfertige Erzeugnisse | 39 | |
| 3940 | Bestandsänderungen nicht fakturierte Dienstleistungen | 39 | |
| 39 | Bestandesänderungen an Erzeugnissen sowie an nicht fakturierten Dienstleistungen | 3 | |
| 3 | Betrieblicher Ertrag aus Lieferungen und Leistungen | E1 | |
| 4000 | Materialaufwand Produktion | 4 | |
| 4200 | Handelswarenaufwand | 4 | |
| 4400 | Aufwand für bezogene Dienstleistungen | 4 | |
| 4500 | Energieaufwand zur Leistungserstellung | 4 | |
| 4800 | Aufwandminderungen | 4 | |
| 4 | Aufwand für Material, Handelswaren, Dienstleistungen und Energie | E1 | |
| E1 | Bruttoergebnis nach Material- und Warenaufwand | E2 | |
| 5000 | Lohnaufwand | 5 | |
| 5701 | AHV, IV, EO Inhaber | 5 | |
| 5710 | FAK | 5 | |
| 5720 | Vorsorgeeinrichtungen | 5 | |
| 5730 | Unfallversicherung | 5 | |
| 5740 | Krankentaggeldversicherung | 5 | |
| 5790 | Quellensteuer | 5 | |
| 5800 | Übriger Personalaufwand | 5 | |
| 5830 | Pauschalspesen Personal | 5 | |
| 5900 | Leistungen Dritter | 5 | |
| 5 | Personalaufwand | E2 | |
| E2 | Bruttoergebnis nach Personalaufwand | E3 | |
| 6000 | Raumaufwand | 60 | |
| 6040 | Reinigung Lokalitäten | 60 | |
| 60 | Raumaufwand | 6 | |
| 6100 | Unterhalt, Reparaturen, Ersatz mobile Sachanlagen | 61 | |
| 6105 | Leasingaufwand mobile Sachanlagen | 61 | |
| 61 | Unterhalt, Reparaturen, Ersatz (URE); Leasing mobile Sachanlagen | 6 | |
| 6200 | Reparaturen | 62 | |
| 6210 | Betriebsstoffe | 62 | |
| 6220 | Haftpflichtversicherung | 62 | |
| 6260 | Fahrzeugleasing | 62 | |
| 6270 | Privatanteile Fahrzeugaufwand | 62 | |
| 6280 | Transportaufwand | 62 | |
| 62 | Fahrzeug- und Transportaufwand | 6 | |
| 6300 | Sachversicherungen, Abgaben, Gebühren, Bewilligungen | 63 | |
| 63 | Sachversicherungen, Abgaben, Gebühren, Bewilligungen | 6 | |
| 6402 | Lichtstrom | 64 | |
| 6410 | Erdgas | 64 | |
| 6430 | Wasser | 64 | |
| 6460 | Kehrichtabfuhr | 64 | |
| 64 | Energie- und Entsorgungsaufwand | 6 | |
| 6500 | Büromaterial | 65 | |
| 6503 | Fachliteratur, Zeitungen, Zeitschriften | 65 | |
| 6510 | Telefon | 65 | |
| 6512 | Internet | 65 | |
| 6513 | Porti | 65 | |
| 6570 | Informatikaufwand inkl. Leasing | 65 | |
| 6580 | Lizenzaufwendungen/Update | 65 | |
| 6583 | Verbrauchsmaterial | 65 | |
| 65 | Verwaltungs- und Informatikaufwand | 6 | |
| 6600 | Werbeaufwand | 66 | |
| 6642 | Kundengeschenke | 66 | |
| 66 | Werbeaufwand | 6 | |
| 6700 | Sonstiger betrieblicher Aufwand | 67 | |
| 67 | Sonstiger betrieblicher Aufwand | 6 | |
| 6 | Übriger betrieblicher Aufwand | E3 | |
| E3 | Betriebliches Ergebnis vor Abschreibungen und Wertberichtigungen, Finanzerfolg und Steuern (EBITDA) | E4 | |
| 6800 | Abschreibungen und Wertberichtigungen auf Positionen des Anlagevermögens | 68 | |
| 68 | Abschreibungen und Wertberichtigungen auf Positionen des Anlagevermögens | E4 | |
| E4 | Betriebliches Ergebnis vor Finanzerfolg und Steuern (EBIT) | E5 | |
| 6900 | Bankkreditzinsaufwand | 69 | |
| 6940 | Bankspesen | 69 | |
| 6950 | Erträge aus Bankguthaben | 69 | |
| 69 | Finanzaufwand und Finanzertrag | E5 | |
| E5 | Betriebliches Ergebnis vor Steuern (EBT) | E6 | |
| 7000 | Ertrag Nebenbetrieb | 7 | |
| 7010 | Aufwand Nebenbetrieb | 7 | |
| 7500 | Ertrag betriebliche Liegenschaft | 7 | |
| 7510 | Aufwand betriebliche Liegenschaft | 7 | |
| 7 | Betrieblicher Nebenerfolg | E6 | |
| 8000 | Betriebsfremder Aufwand | 8 | |
| 8100 | Betriebsfremder Ertrag | 8 | |
| 8500 | Ausserordentlicher, einmaliger oder periodenfremder Aufwand | 8 | |
| 8510 | Ausserordentlicher, einmaliger oder periodenfremder Ertrag | 8 | |
| 8 | Betriebsfremder, ausserordentlicher, einmaliger oder periodenfremder Aufwand und Ertrag | E6 | |
| E6 | Jahresgewinn oder Jahresverlust vor Steuern | E7 | |
| 8900 | Direkte Steuern | 89 | |
| 89 | Direkte Steuern | E7 | |
| E7 | Jahresgewinn oder Jahresverlust | 2891 | |
| 00 | Differenz muss = 0 sein | ||
| DEBITOREN | |||
| ;110001 | Urs Weisshaupt | DEB1 | |
| ;110002 | Susanne Müller | DEB1 | |
| ;110003 | Peter Schmid | DEB1 | |
| DEB1 | Total Debitoren | ||
| KREDITOREN | |||
| ;200001 | Firma 1 | KRE1 | |
| ;200002 | Firma 2 | KRE1 | |
| ;200003 | Firma 3 | KRE1 | |
| KRE1 | Total Kreditoren | ||
| KOSTENSTELLEN | |||
| .HAN | Handelswaren A | VOR | |
| .ROH | Rohstoffe A | VOR | |
| .WER | Werkstoffe A | VOR | |
| VOR | Total Vorräte | ||
| ,UN1 | Unterhalt 1 | UN | |
| ,UN2 | Unterhalt 2 | UN | |
| ,UN3 | Unterhalt 3 | UN | |
| UN | Total Unterhalt | ||
| ;WE1 | Werbeaufwand 1 | WER | |
| ;WE2 | Werbeaufwand 2 | WER | |
| WER | Total Werbeaufwand |
| MwSt/USt-Code | Beschreibung | MwSt/USt-% |
|---|---|---|
| Erläuterungen | ||
| V = Umsatz Verkauf (200) | ||
| VS = Skonto Verkauf und Dienstleistungen (235) | ||
| B = Bezugsteuer (38x) | ||
| M = Material- und Dienstleistungsaufwand (400) | ||
| I = Investitionen und übrigem Betriebsaufwand (405) | ||
| K = Korrekturen und Kürzungen (410, 415, 420) | ||
| Z = Nicht-Entgelte (910) | ||
| MwSt/USt-Codes-Informationen (nicht bearbeiten) | ||
| id=vatcodes-chd-2024.20230614 | ||
| Letzte Aktualisierung: 14.06.2023 | ||
| Umsatzsteuer (Schuld) | ||
| V0 | Von der Steuer befreite Leistungen, u.a. Exporte (220) | |
| V0-E | Leistungen im Ausland (221) | |
| V0-T | Übertragung im Meldeverfahren (225) | |
| V0-N | Nicht steuerbare Leistungen (230) | |
| Entgeltminderungen siehe Skonti | ||
| V0-D | Diverses (280) | |
| V77 | Verkauf und Dienstleistungen 7.7% | 7.70 |
| V81 | Verkauf und Dienstleistungen 8.1% | 8.10 |
| V77-B | Verkauf und Dienstleistungen 7.7% (optiert) | 7.70 |
| V81-B | Verkauf und Dienstleistungen 8.1% (optiert) | 8.10 |
| V25-N | Verkauf und Dienstleistungen 2.5% | 2.50 |
| V26 | Verkauf und Dienstleistungen 2.6% | 2.60 |
| V37 | Verkauf und Dienstleistungen 3.7% | 3.70 |
| V38 | Verkauf und Dienstleistungen 3.8% | 3.80 |
| VS77 | Skonto Verkauf und Dienstleistungen 7.7% | 7.70 |
| VS81 | Skonto Verkauf und Dienstleistungen 8.1% | 8.10 |
| VS25-N | Skonto Verkauf und Dienstleistungen 2.5% | 2.50 |
| VS26 | Skonto Verkauf und Dienstleistungen 2.6% | 2.60 |
| VS37 | Skonto Verkauf und Dienstleistungen 3.7% | 3.70 |
| VS38 | Skonto Verkauf und Dienstleistungen 3.8% | 3.80 |
| Steuerbarer Gesamtumsatz (299) | ||
| F1 | 1. Saldosteuersatz 2024 | |
| F2 | 2. Saldosteuersatz 2024 | |
| FS1 | Skonto Verkauf und Dienstleistungen 1. Saldosteuersatz 2024 | |
| FS2 | Skonto Verkauf und Dienstleistungen 2. Saldosteuersatz 2024 | |
| F3 | 1. Saldosteuersatz 2018 | |
| F4 | 2. Saldosteuersatz 2018 | |
| FS3 | Skonto Verkauf und Dienstleistungen 1. Saldosteuersatz 2018 | |
| FS4 | Skonto Verkauf und Dienstleistungen 2. Saldosteuersatz 2018 | |
| Total Saldosteuersatz (322-333) | ||
| B77 | Bezugsteuer 7.7% (inklusive MwSt/USt) | 7.70 |
| B77-1 | Bezugsteuer 7.7% (exklusive MwSt/USt) | 7.70 |
| B77-2 | Bezugsteuer 7.7% (MwSt/USt-Betrag) | 7.70 |
| B81 | Bezugsteuer 8.1% (inklusive MwSt/USt) | 8.10 |
| B81-1 | Bezugsteuer 8.1% (exklusive MwSt/USt) | 8.10 |
| B81-2 | Bezugsteuer 8.1% (MwSt/USt-Betrag) | 8.10 |
| Total Bezugsteuer (382-383) | ||
| Total geschuldete Steuer (399) | ||
| Vorsteuer (Guthaben) | ||
| M0 | Befreite Material- und Dienstleistungsaufwand | |
| I0 | Befreite Investition und Betriebsaufwand | |
| M77 | Material- und Dienstleistungsaufwand 7.7% (inklusive MwSt/USt) | 7.70 |
| M77-1 | Material- und Dienstleistungsaufwand 7.7% (exklusive MwSt/USt) | 7.70 |
| M77-2 | Material- und Dienstleistungsaufwand 7.7% (MwSt/USt-Betrag) | 7.70 |
| M81 | Material- und Dienstleistungsaufwand 8.1% (inklusive MwSt/USt) | 8.10 |
| M81-1 | Material- und Dienstleistungsaufwand 8.1% (exklusive MwSt/USt) | 8.10 |
| M81-2 | Material- und Dienstleistungsaufwand 8.1% (MwSt/USt-Betrag) | 8.10 |
| M25 | Material- und Dienstleistungsaufwand 2.5% | 2.50 |
| M26 | Material- und Dienstleistungsaufwand 2.6% | 2.60 |
| M37 | Material- und Dienstleistungsaufwand 3.7% | 3.70 |
| M38 | Material- und Dienstleistungsaufwand 3.8% | 3.80 |
| Investition und Betriebsaufwand | ||
| I77 | Investition und Betriebsaufwand 7.7% | 7.70 |
| I77-1 | Investition und Betriebsaufwand 7.7% (exklusive MwSt/USt) | 7.70 |
| I77-2 | Investition und Betriebsaufwand 7.7% (MwSt/USt-Betrag) | 7.70 |
| I81 | Investition und Betriebsaufwand 8.1% | 8.10 |
| I81-1 | Investition und Betriebsaufwand 8.1% (exklusive MwSt/USt) | 8.10 |
| I81-2 | Investition und Betriebsaufwand 8.1% (MwSt/USt-Betrag) | 8.10 |
| I25 | Investition und Betriebsaufwand 2.5% | 2.50 |
| I26 | Investition und Betriebsaufwand 2.6% | 2.60 |
| I37 | Investition und Betriebsaufwand 3.7% | 3.70 |
| I38 | Investition und Betriebsaufwand 3.8% | 3.80 |
| Korrekturen und Kürzungen | ||
| K77-A | Einlageentsteuerung 7.7% (410) | 7.70 |
| K81-A | Einlageentsteuerung 8.1% (410) | 8.10 |
| K77-B | Vorsteuerkorrekturen 7.7% (415) | 7.70 |
| K81-B | Vorsteuerkorrekturen 8.1% (415) | 8.10 |
| K77-C | Vorsteuerkürzungen 7.7% (420) | 7.70 |
| K81-C | Vorsteuerkürzungen 8.1% (420) | 8.10 |
| F1050 | Steueranrechnung gemäss Formular Nr. 1050 | |
| F1055 | Steueranrechnung gemäss Formular Nr. 1055 | |
| Total Vorsteuer (479) | ||
| Total zu bezahlen (500) oder Guthaben (510) | ||
| Andere Mittelflüsse | ||
| Z0-A | Subventionen, durch Kurvereine eingenommene Tourismusabgaben, Entsorgungs-und Wasserwerkbeiträge (Bst. a-c) | |
| Z0 | Spenden, Dividenden, Schadenersatz usw. | |
| Nicht-Entgelte | ||
| Total der Kontrolle | ||
Legal entities | Accrual-based customer ledger | Double-entry accounting | VAT
In this article
Legal entities | Accrual-based customer ledger | Double-entry accounting | VAT
Legal entities | Accrual-based customer ledger | Double-entry accounting | VAT
Banana Accounting Plus template for managing revenue-based accounting of an SA or Sagl company, subject to VAT. The customer/supplier ledger is already set up with the corresponding totals grouped in the Balance Sheet. Includes the VAT Codes table with the Swiss rates in effect from 01.01.2024. With the specific Extension available in the Advanced plan, you can generate the VAT return sample and the XML file to upload VAT data to the FTA portal. Open the template from our WebApp or from the program and save the file to your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
Ideal template for managing the accounting of an SA or SAGL with VAT and an annual turnover equal to or greater than CHF 500,000. The chart of accounts is structured according to the SME scheme and includes the customer/supplier ledger, suitable for revenue-based accounting.
- In the Accounts table, at the end of the chart of accounts, you will find the customer and supplier ledger set up with accounts linked respectively to assets and liabilities; therefore, the balances will appear in the Balance Sheet.
- All customer and supplier invoices are recorded at the time of issue and receipt.
Create your file
- Open the template with the Banana Accounting Plus WebApp
- With the File > File and accounting properties command, set the period, your company name, and base currency (you can do budgeting and accounting in any currency you like).
- With the File > Save As command, save the file. It’s helpful to include the company name and year in the file name. For example, "Rossi-SA-20xx.ac2".
WARNING: If you close the browser without saving, you will lose the entered data. Always save the file to your computer.
To reopen the saved file, click on File > Open.
With this template you can:
- Create invoices with VAT to send to customers by using the Debit column for the customer account and the Credit column for the revenue account. This way, the invoice is already booked and integrated into your accounting file.
- Record received invoices from suppliers, also using QR code reading, and create payment orders (pain.001). Pain.001 files are XML messages that contain payment details and can be sent to financial institutions that support this format. More info at pain.001 payment orders (available only with Advanced plan – Dev version).
- Import all transactions from bank and postal statements or credit cards using Rules for fully automated entries (only with Advanced plan).
- Manage cost centers or Segments to monitor branches, departments, or profitability of products and services.
- Create budgets and financial forecasts to monitor liquidity and ensure you can meet future commitments; forecast revenues and expenses, and evaluate profitability scenarios for your company.
- Manage VAT according to the latest Swiss regulations.
- Print all the reports you need: Balance Sheets, Journal, Account cards, Open invoices, and much more.
For VAT management with the new rates, you’ll find detailed information on the following web pages: VAT management
Some features require a subscription to the Advanced plan of Banana Accounting Plus, such as generating the sample or XML VAT return, using the new Rules, Filter, and Temporary Sort features. See all the features of the Advanced plan.
Other Resources
Template preview
Company XXX
Accounting 2024
Basic Currency: CHF
Double-entry with VAT/Sales tax
| Group | Account | Description | Sum In | Gr1 |
|---|---|---|---|---|
| BALANCE SHEET | ||||
| ASSETS | ||||
| 1000 | Cash on hand | 100 | ||
| 1020 | Bank account | 100 | ||
| 100 | Cash and cash equivalents | 10 | 1 | |
| 1060 | Bonds and stocks | 106 | ||
| 106 | Short-term Assets listed in Stock Exchange | 10 | ||
| 1090 | Internal transfers | 109 | ||
| 1091 | Transfer account for salaries | 109 | ||
| 1099 | Amounts to be clarified | 109 | ||
| 109 | Transfer accounts | 10 | ||
| 1100 | Due from Clients or Debitors | 110 | ||
| 1109 | Provision for Doubtful Debts | 110 | ||
| 110A | Clients or Debtors | 110 | ||
| 110 | Accounts receivable | 10 | ||
| 1140 | Advances and loans | 114 | ||
| 1176 | Withholding tax | 114 | ||
| 1180 | Receivables from social insurances and social security institutions | 114 | ||
| 1188 | Source tax | 114 | ||
| 1190 | Various short-term receivables | 114 | ||
| 1199 | Securities | 114 | ||
| 114 | Other short-term receivables | 10 | ||
| 1200 | Goods for resale | 120 | ||
| 1210 | Raw materials | 120 | ||
| 1220 | Auxiliary material | 120 | ||
| 1230 | Consumables | 120 | ||
| 1260 | Finished products | 120 | ||
| 1270 | In-process products | 120 | ||
| 1280 | Non-invoiced services | 120 | ||
| 120 | Inventories | 10 | 1 | |
| 1300 | Prepaid expenses | 130 | ||
| 1301 | Accrued income | 130 | ||
| 130 | Prepaid Expenses | 10 | 1 | |
| 10 | Current assets | 1 | 1 | |
| 1400 | Bonds and stocks | 140 | ||
| 1440 | Loans | 140 | ||
| 1460 | Loan to share-holder | 140 | ||
| 140 | Financial assets | 14 | ||
| 1480 | Investments | 148 | ||
| 148 | Investments | 14 | ||
| 1500 | Machinery | 150 | ||
| 1510 | Office furniture and equipment | 150 | ||
| 1520 | Office machinery, information and communication technology | 150 | ||
| 1530 | Motor vehicles | 150 | ||
| 1540 | Tools and equipment | 150 | ||
| 150 | Tangible assets | 14 | ||
| 1600 | Commercial buildings | 160 | ||
| 160 | Tangible fixed asset management | 14 | ||
| 1700 | Patents, know-how, licences, rights and development | 170 | ||
| 1710 | Brands | 170 | ||
| 1712 | Models | 170 | ||
| 1770 | Goodwill | 170 | ||
| 170 | Intangible fixed assets | 14 | ||
| 1850 | Share capital, rights not paid or non-paid Foundation capital | 180 | ||
| 180 | Capital or non-paid Foundation capital | 14 | ||
| 14 | Fixed Assets | 1 | ||
| 1 | Total Assets | 00 | ||
| LIABILITIES | ||||
| 2000 | Suppliers or creditors | 200 | ||
| 2030 | Deposits received | 200 | ||
| 200A | Suppliers or creditors | 200 | ||
| 200 | Suppliers or creditors | 20 | 1 | |
| 2100 | Due to banks short/term | 210 | ||
| 2120 | Financial leasing commitments | 210 | ||
| 2140 | Other onerous debts | 210 | ||
| 210 | Short-term onorous debts | 20 | ||
| 2200 | VAT Due | 220 | ||
| 2201 | VAT according to VAT report | 220 | ||
| 2206 | Withholding tax | 220 | ||
| 2208 | Direct taxes | 220 | ||
| 2210 | Other short-term debts | 220 | ||
| 2260 | Due to share-holder | 220 | ||
| 2261 | Dividends | 220 | ||
| 2270 | Social insurances and social security institutions | 220 | ||
| 2279 | Source tax | 220 | ||
| 220 | Other short-term debts | 20 | ||
| 2300 | Accrued expenses | 230 | ||
| 2301 | Next year's revenues collected | 230 | ||
| 2330 | Short-term provisions | 230 | ||
| 230 | Accruals and deferred income | 20 | ||
| 20 | Short-term third party capital | 2A | ||
| 2400 | Due to banks | 240 | ||
| 2420 | Financial leasing commitments | 240 | ||
| 2430 | Debenture loans | 240 | ||
| 2450 | Loans | 240 | ||
| 2451 | Mortgage | 240 | ||
| 240 | Long-term onorous debts | 24 | ||
| 2500 | Other long-term debts (non-onorous) | 250 | ||
| 250 | Other long-term debts | 24 | ||
| 2600 | Provisions | 260 | ||
| 260 | Provisions and similar statutory posts | 24 | ||
| 24 | Long-term third party capital | 2A | ||
| 2A | Third party capital | 2 | ||
| 2800 | Share capital, rights, foundation capital | 280 | ||
| 280 | Capital or capital of the foundation | 28 | ||
| 2900 | Legal reserves | 290 | ||
| 2940 | Revaluation reserves | 290 | ||
| 290 | Legal reserves | 28 | ||
| 2950 | Legal reserve from profit | 295 | ||
| 295 | Legal reserve from profit | 28 | ||
| 2960 | Optional reserves from profit | 296 | ||
| 296 | Optional reserves from profit | 28 | ||
| 2970 | Profit / Loss carried forward | 297 | ||
| 29A | Profit / Loss for the year | 297 | ||
| 297 | Profit / Loss from Balance Sheet | 28 | ||
| 2980 | Treasury stock, shares, rights of investment (negative) | 298 | ||
| 298 | Treasury stock, shares, rights of investment (negative) | 28 | ||
| 28 | Equity | 2 | ||
| 2 | Total liabilities | 00 | 1 | |
| PROFIT & LOSS STATEMENT | ||||
| 3000 | Earnings from own products | 30 | ||
| 3200 | Earnings from resale | 30 | ||
| 3400 | Earnings from services rendered | 30 | ||
| 3600 | Other revenues and services | 30 | ||
| 3710 | Own consumption | 30 | ||
| 3800 | Decrease in revenues | 30 | ||
| 3805 | Losses on accounts receivable, credit variation | 30 | ||
| 3809 | VAT flat tax rate | 30 | ||
| 30 | Net revenues from supplies and services | 3 | ||
| 3900 | Change in inventories of in-process products | 39 | ||
| 3901 | Change in inventories of finished products | 39 | ||
| 3940 | Non-invoiced services variations | 39 | ||
| 39 | Change in inventories and Non-invoiced services | 3 | ||
| 3 | Revenues from supplies and services | E1 | ||
| 4000 | Raw materials | 4 | ||
| 4200 | Expenses for goods for resale | 4 | ||
| 4400 | Third party expenses | 4 | ||
| 4500 | Energy consumption for production | 4 | ||
| 4900 | Reduction of costs | 4 | ||
| 4 | Costs for material, goods, services and energy | E1 | ||
| E1 | Gross operating result after deducting costs for materials and goods | E2 | ||
| 5000 | Salaries | 5 | ||
| 5700 | Contribution to old age insurance and unemployment | 5 | ||
| 5710 | Family equalization fund | 5 | ||
| 5720 | Contribution to pension funds | 5 | ||
| 5730 | Contribution to accident insurance | 5 | ||
| 5740 | Contribution to voluntary daily benefits insurance | 5 | ||
| 5790 | Source tax | 5 | ||
| 5800 | Other personnel expenses | 5 | ||
| 5810 | Training of personnel | 5 | ||
| 5820 | Travel and entertainment expenses effective | 5 | ||
| 5830 | Travel and entertainment expense allowance | 5 | ||
| 5900 | Temporary staff | 5 | ||
| 5 | Personnel expenses | E2 | ||
| E2 | Gross operating result after deducting personnel expenses | E3 | ||
| 6000 | Rental | 60 | ||
| 6040 | Cleaning of facilities | 60 | ||
| 60 | Rental | 6 | ||
| 6100 | Maintenance, repairs and replacement of tangible assets | 61 | ||
| 6105 | Leasing costs tangible assets | 61 | ||
| 61 | Maintenance, repairs and replacement of tangible assets | 6 | ||
| 6200 | Repairs | 62 | ||
| 6210 | Fuel | 62 | ||
| 6220 | Car insurance | 62 | ||
| 6260 | Car leasing and rental | 62 | ||
| 6270 | Car costs - private part | 62 | ||
| 6282 | Transportation expenses | 62 | ||
| 62 | Vehicle and transportation expenses | 6 | ||
| 6300 | Insurance for damage of items | 63 | ||
| 63 | Insurance for damage of items | 6 | ||
| 6402 | Electricity | 64 | ||
| 6410 | Heating expenses | 64 | ||
| 6430 | Water | 64 | ||
| 6460 | Garbage | 64 | ||
| 64 | Energy and disposal costs | 6 | ||
| 6500 | Office supplies | 65 | ||
| 6503 | Technical magazines, newspapers, periodicals | 65 | ||
| 6510 | Telephone / internet | 65 | ||
| 6511 | Hosting at third-party | 65 | ||
| 6513 | Postal charges | 65 | ||
| 6570 | IT charges including leasing | 65 | ||
| 6580 | Licenses and updates | 65 | ||
| 6583 | Consumables | 65 | ||
| 65 | Administrative and IT costs | 6 | ||
| 6600 | Advertising | 66 | ||
| 6642 | Gifts to customers | 66 | ||
| 66 | Advertising | 6 | ||
| 6700 | Various costs for the financial year | 67 | ||
| 67 | Various costs for the financial year | 6 | ||
| 6 | Other operating expenses, depreciation, value adjustments and financial results | E3 | ||
| E3 | Operating result before depreciation and value adjustments, financial results and taxes (EBITDA) | E4 | ||
| 6800 | Depreciation and value adjustments of fixed assets | 68 | ||
| 68 | Depreciation and value adjustments of fixed assets | E4 | ||
| E4 | Operating result before financial results and taxes (EBIT) | E5 | ||
| 6900 | Costs for bank interest | 69 | ||
| 6940 | Bank costs | 69 | ||
| 6950 | Financial revenue | 69 | ||
| 69 | Financial costs and revenue | E5 | ||
| E5 | Operating result before taxes (EBT) | E6 | ||
| 7000 | Non-operating revenue | 7 | ||
| 7010 | Non-operating costs | 7 | ||
| 7500 | Corporate real estate revenues | 7 | ||
| 7510 | Corporate real estate costs | 7 | ||
| 7 | Non-operating items | E6 | ||
| 8000 | Extraneous costs | 8 | ||
| 8100 | Extraneous revenue | 8 | ||
| 8500 | Extraordinary, unique costs or costs relating to other accounting periods | 8 | ||
| 8510 | Extraordinary, unique revenue or revenue relating to other accounting periods | 8 | ||
| 8 | Results of extraneous, extraordinary or unique character, or for other accounting periods | E6 | ||
| E6 | Profit or loss before taxes | E7 | ||
| 8900 | Direct taxes | 89 | ||
| 89 | Direct taxes | E7 | ||
| E7 | Annual profit or loss | 29A | ||
| 00 | Difference should be = 0 (blank cell) | |||
| CLIENTS/DEBTORS | ||||
| 110001 | Company 1 | DEB1 | ||
| 110002 | Company 2 | DEB1 | ||
| 110003 | Company 3 | DEB1 | ||
| DEB1 | Total Clients/Debtors | 110A | ||
| SUPPLIERS/CREDITORS | ||||
| 200001 | Company 1 | CRE1 | ||
| 200002 | Company 2 | CRE1 | ||
| 200003 | Company 3 | CRE1 | ||
| CRE1 | Total suppliers/Creditors | 200A | ||
| COST CENTERS | ||||
| .PAC | Packaging A | INV | ||
| .RM | Raw materials A | INV | ||
| .AM | Auxiliairy materials A | INV | ||
| INV | Total inventories | |||
| ,MAN1 | Maintenance 1 | MAN | ||
| ,MAN2 | Maintenance 2 | MAN | ||
| ,MAN3 | Maintenance 3 | MAN | ||
| MAN | Total maintenance | |||
| ;PB1 | Publicity 1 | PU | ||
| ;PB2 | Publicity 2 | PU | ||
| PU | Total publicity | |||
| VAT Code | Description | %VAT |
|---|---|---|
| Explanations | ||
| V = Sales (200) | ||
| VS = Discount sales and services (235) | ||
| B = Acquisition tax (38x) | ||
| M = Expenses for material and services (400) | ||
| I = Investments and other operating expenses (405) | ||
| K = Corrections (410, 415, 420) | ||
| Z = Not considered (910) | ||
| VAT codes information (do not modify) | ||
| id=vatcodes-che-2024.20230614 | ||
| Last update: 14.06.2023 | ||
| VAT Due | ||
| V0 | Exempt services (220) | |
| V0-E | Export services abroad (221) | |
| V0-T | Transfers in the reporting procedure (225) | |
| V0-N | Non-taxable services (230) | |
| Decrease of income from services, see discounts | ||
| V0-D | Various (280) | |
| V77 | Sales and services 7.7% | 7.70 |
| V81 | Sales and services 8.1% | 8.10 |
| V77-B | Sales and services 7.7% (chosen) | 7.70 |
| V81-B | Sales and services 8.1% (chosen) | 8.10 |
| V25-N | Sales and services 2.5% | 2.50 |
| V26 | Sales and services 2.6% | 2.60 |
| V37 | Sales and services 3.7% | 3.70 |
| V38 | Sales and services 3.8% | 3.80 |
| VS77 | Discount Sales and services 7.7% | 7.70 |
| VS81 | Discount Sales and services 8.1% | 8.10 |
| VS25-N | Discount Sales and services 2.5% | 2.50 |
| VS26 | Discount Sales and services 2.6% | 2.60 |
| VS37 | Discount Sales and services 3.7% | 3.70 |
| VS38 | Discount Sales and services 3.8% | 3.80 |
| Taxable turnover (299) | ||
| F1 | 1. Flat tax rate 2024 | |
| F2 | 2. Flat tax rate 2024 | |
| FS1 | Discount Sales and services 1. Flat tax rate 2024 | |
| FS2 | Discount Sales and services 2. Flat tax rate 2024 | |
| F3 | 1. Flat tax rate 2018 | |
| F4 | 2. Flat tax rate 2018 | |
| FS3 | Discount Sales and services 1. Flat tax rate 2018 | |
| FS4 | Discount Sales and services 2. Flat tax rate 2018 | |
| Total Flat tax rate (322-333) | ||
| B77 | Acquisition tax 7.7% (With VAT/Sales tax) | 7.70 |
| B77-1 | Acquisition tax 7.7% (Without VAT/Sales tax) | 7.70 |
| B77-2 | Acquisition tax 7.7% (VAT/Sales tax amount) | 7.70 |
| B81 | Acquisition tax 8.1% (With VAT/Sales tax) | 8.10 |
| B81-1 | Acquisition tax 8.1% (Without VAT/Sales tax) | 8.10 |
| B81-2 | Acquisition tax 8.1% (VAT/Sales tax amount) | 8.10 |
| Total Tax on purchases (382-383) | ||
| Total VAT Due (399) | ||
| Recoverable VAT | ||
| M0 | Exempt material- and service expenses | |
| I0 | Exempt investment and operating expenses | |
| M77 | Purchase of material and services 7.7% (With VAT/Sales tax) | 7.70 |
| M77-1 | Purchase of material and services 7.7% (Without VAT/Sales tax) | 7.70 |
| M77-2 | Purchase of material and services 7.7% (VAT/Sales tax amount) | 7.70 |
| M81 | Purchase of material and services 8.1% (With VAT/Sales tax) | 8.10 |
| M81-1 | Purchase of material and services 8.1% (Without VAT/Sales tax) | 8.10 |
| M81-2 | Purchase of material and services 8.1% (VAT/Sales tax amount) | 8.10 |
| M25 | Purchase of material and services 2.5% | 2.50 |
| M26 | Purchase of material and services 2.6% | 2.60 |
| M37 | Purchase of material and services 3.7% | 3.70 |
| M38 | Purchase of material and services 3.8% | 3.80 |
| Investment and operating expenses | ||
| I77 | Investment and operating expenses 7.7% | 7.70 |
| I77-1 | Investment and operating expenses 7.7% (Without VAT/Sales tax) | 7.70 |
| I77-2 | Investment and operating expenses 7.7% (VAT/Sales tax amount) | 7.70 |
| I81 | Investment and operating expenses 8.1% | 8.10 |
| I81-1 | Investment and operating expenses 8.1% (Without VAT/Sales tax) | 8.10 |
| I81-2 | Investment and operating expenses 8.1% (VAT/Sales tax amount) | 8.10 |
| I25 | Investment and operating expenses 2.5% | 2.50 |
| I26 | Investment and operating expenses 2.6% | 2.60 |
| I37 | Investment and operating expenses 3.7% | 3.70 |
| I38 | Investment and operating expenses 3.8% | 3.80 |
| Corrections and adjustments | ||
| K77-A | Subsequent adjustment of prior tax 7.7% (410) | 7.70 |
| K81-A | Subsequent adjustment of prior tax 8.1 % (410) | 8.10 |
| K77-B | Corrections of prior tax 7.7% (415) | 7.70 |
| K81-B | Corrections of prior tax 8.1% (415) | 8.10 |
| K77-C | Reductions of the deduction of prior tax 7.7% (420) | 7.70 |
| K81-C | Reductions of the deduction of prior tax 8.1% (420) | 8.10 |
| F1050 | Tax computation according to form Nr. 1050 | |
| F1055 | Tax computation according to form Nr. 1055 | |
| Total Recoverable VAT (479) | ||
| Total VAT payable (500) or VAT credit (510) | ||
| Other financial flows | ||
| Z0-A | Subsidies, tourist taxes collected by the tourism offices, contributions to the institutions responsible for the elimination of waste and for the supply of water (let. a - c) | |
| Z0 | Gifts, dividends, compensation for damages etc. | |
| Not considered | ||
| Final total for control | ||
Legal entities | Cash principle ledger | Double-entry accounting | VAT
In this article
Legal entities | Cash principle ledger | Double-entry accounting | VAT
Legal entities | Cash principle ledger | Double-entry accounting | VAT
The ideal template for the accounting of an SA and Sagl with VAT on a cash basis. We have used the CC3 cost and profit center to set up customer and supplier management based on cash receipts. The VAT rates are included to ensure compliance with VAT regulations from 2024. Thanks to the new CH10 Layout, you can print your invoices with a QR code. Automatically, you will obtain the balance sheet, income statement, and many other reports that help you fulfill tax obligations and keep your company’s financial and economic situation under control. You can also create cash flow forecasts and budgets. Open the model from our WebApp or the program and save the file on your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
Ideal model for managing the accounting of an SA and Sagl with VAT and an annual turnover equal to or exceeding CHF 500,000. The chart of accounts is structured according to the SME framework and includes the customer/supplier ledger, suitable for those managing accounting on a cash basis. It includes all the necessary settings and functions for:
- Creating and printing invoices with the Swiss QR code
- Importing data from bank statements
- Setting up rules to store and automate the completion of transactions imported from bank statements
- Managing VAT according to the new VAT rates
- Handling cost centers, customisable to track specific details for particular accounts
- Creating budgets and financial forecasts
- Printing all the reports you need: balance sheets, journal, account statements, VAT reports, open invoices, and much more
For VAT management with the new rates, you can find detailed information on the VAT management web pages.
Some features require a subscription to the Advanced plan of Banana Accounting Plus, such as generating the VAT report template or XML file, using the new Rules functions, and the temporary Filter and Sort rows feature. Check out all the features of the Advanced plan.
Create your file
- Open the template with the Banana Accounting WebApp
- Using the File > File Properties command, set the period, your company name, and the base currency (you can create a budget and manage accounting in any currency you prefer).
- With the File > Save As command, save the file. It is useful to include your studio name and the year in the file name. For example, "Studio-Rossi-SA-20xx.ac2".
WARNING: If you close the browser without saving, you will lose the entered data. Always save the file on your computer.
In our Documentation, you will find explanations on various topics to help you manage your accounting effectively:
- Videos
- How to get started
- Transactions
- Integrated invoicing
- Reminders
- Estimates and Invoices
- VAT report form - Effective method (in German, French and Italian only)
- VAT report form - Flat rate method (in German, French and Italian only)
- Printouts
Partnerships | Double-entry bookkeeping | VAT
In this article
Partnerships | Double-entry bookkeeping | VAT
Partnerships | Double-entry bookkeeping | VAT
Ideal template for managing VAT accounting for a partnership. Professional and instant reports: Balance Sheet, Profit & Loss Statement, Account Cards, Journal, and other reports also by period. Detailed sector information with cost centers and digital documents attached to entries to ensure organisation and immediate overview, without consulting paper documents. VAT management is fully automated and compliant with the new rates in effect from 01.01.2024; in addition to VAT summaries, it also allows the creation of the XML file for electronic submission of VAT data to the FTA (Advanced plan). Open the template from our WebApp or from the program and save the file to your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
Ideal template for a partnership with VAT management. It includes all settings and functions to:
- Import data from bank statements
- Set up Rules to save and automate the completion of transactions imported from bank statements.
- Manage VAT according to the new VAT rates
- Manage cost centers ,customizable to your needs to view specific details of certain accounts.
- Create budgets and financial forecasts
- Create and print invoices with Swiss QR code , just set up the accounts receivable and payable using CC3
- Print all the reports you need : Balance Sheets, Journal, Account Cards, VAT Reports, Open Invoices, and much more.
For VAT management with the new rates, you can find detailed information on the web pages VAT Management .
Some features require a subscription to the Advanced plan of Banana Accounting Plus , such as generating a preview or the XML file for the VAT report, using the new Rules, Filter and Temporary Sort functions. See all the features of the Advanced plan .
Create your file
- Open the template with the Banana Accounting Plus WebApp
- From the menu File > File properties set the period, your company name, and the base currency in any currency you prefer.
- From the menu File > Save as , save the file. It's helpful to include the company name and the year in the file name. For example, "Rossi-SA-20xx.ac2".
- Nella tabella Exchange rates set the foreign currencies always with reference to the base currency and the exchange rates. The opening rates are set only the first time you use Banana Accounting. At the turn of the new year, they are automatically carried forward according to the closing rates entered on 31.12.
WARNING: If you close the browser without saving, you will lose the entered data. Always save the file to your computer.
To reopen the saved file, click on File > Open .
In our Documentation you will find all the information and insights to manage your accounting efficiently:
Template preview
Company XXX
Accounting 2024
Basic Currency: CHF
Double-entry with VAT/Sales tax
| Group | Account | Description | Sum In | Gr1 |
|---|---|---|---|---|
| BALANCE SHEET | ||||
| ASSETS | ||||
| 1000 | Cash on hand | 100 | ||
| 1020 | Bank account | 100 | ||
| 100 | Cash and cash equivalents | 10 | 1 | |
| 1060 | Bonds and stocks | 106 | ||
| 106 | Short-term Assets listed in Stock Exchange | 10 | ||
| 1090 | Internal transfers | 109 | ||
| 1091 | Transfer account for salaries | 109 | ||
| 1099 | Amounts to be clarified | 109 | ||
| 109 | Transfer accounts | 10 | ||
| 1100 | Due from Clients or Debtors | 110 | ||
| 1109 | Provision for Doubtful Debts | 110 | ||
| 110 | Accounts receivable | 10 | ||
| 1140 | Advances and loans | 114 | ||
| 1176 | Withholding tax | 114 | ||
| 1180 | Receivables from social insurances and social security institutions | 114 | ||
| 1188 | Source tax | 114 | ||
| 1190 | Various short-term receivables | 114 | ||
| 1199 | Securities | 114 | ||
| 114 | Other short-term receivables | 10 | ||
| 1200 | Goods for resale | 120 | ||
| 1210 | Raw materials | 120 | ||
| 1220 | Auxiliary material | 120 | ||
| 1230 | Consumables | 120 | ||
| 1260 | Finished products | 120 | ||
| 1270 | In-process products | 120 | ||
| 1280 | Non-invoiced services | 120 | ||
| 120 | Inventories | 10 | 1 | |
| 1300 | Prepaid expenses | 130 | ||
| 1301 | Accrued income | 130 | ||
| 130 | Prepaid Expenses | 10 | 1 | |
| 10 | Current assets | 1 | 1 | |
| 1400 | Bonds and stocks | 140 | ||
| 1440 | Loans | 140 | ||
| 1460 | Loan to partner | 140 | ||
| 140 | Financial assets | 14 | ||
| 1480 | Investments | 148 | ||
| 148 | Investments | 14 | ||
| 1500 | Machinery | 150 | ||
| 1510 | Office furniture and equipment | 150 | ||
| 1520 | Office machinery, information and communication technology | 150 | ||
| 1530 | Motor vehicles | 150 | ||
| 1540 | Tools and equipment | 150 | ||
| 150 | Tangible assets | 14 | ||
| 1600 | Commercial buildings | 160 | ||
| 160 | Tangible fixed asset management | 14 | ||
| 1700 | Patents, know-how, licences, rights and development | 170 | ||
| 1710 | Brands | 170 | ||
| 1712 | Models | 170 | ||
| 1770 | Goodwill | 170 | ||
| 170 | Intangible fixed assets | 14 | ||
| 1850 | Share capital, rights not paid or non-paid Foundation capital | 180 | ||
| 180 | Capital or non-paid Foundation capital | 14 | ||
| 14 | Fixed Assets | 1 | ||
| 1 | Total Assets | 00 | ||
| LIABILITIES | ||||
| 2000 | Suppliers or creditors | 200 | ||
| 2030 | Deposits received | 200 | ||
| 200 | Suppliers or creditors | 20 | 1 | |
| 2100 | Due to banks short/term | 210 | ||
| 2120 | Financial leasing commitments | 210 | ||
| 2140 | Other onerous debts | 210 | ||
| 210 | Short-term onorous debts | 20 | ||
| 2200 | VAT Due | 220 | ||
| 2201 | VAT according to VAT report | 220 | ||
| 2206 | Withholding tax | 220 | ||
| 2208 | Direct taxes | 220 | ||
| 2210 | Other short-term debts | 220 | ||
| 2260 | Due to partner | 220 | ||
| 2270 | Social insurances and social security institutions | 220 | ||
| 2279 | Source tax | 220 | ||
| 220 | Other short-term debts | 20 | ||
| 2300 | Accrued expenses | 230 | ||
| 2301 | Next year's revenues collected | 230 | ||
| 2330 | Short-term provisions | 230 | ||
| 230 | Accruals and deferred income | 20 | ||
| 20 | Short-term third party capital | 2A | ||
| 2400 | Due to banks | 240 | ||
| 2420 | Financial leasing commitments | 240 | ||
| 2430 | Debenture loans | 240 | ||
| 2450 | Loans | 240 | ||
| 2451 | Mortgage | 240 | ||
| 240 | Long-term onorous debts | 24 | ||
| 2500 | Other long-term debts (non-onorous) | 250 | ||
| 250 | Other long-term debts | 24 | ||
| 2600 | Provisions | 260 | ||
| 260 | Provisions and similar statutory posts | 24 | ||
| 24 | Long-term third party capital | 2A | ||
| 2A | Third party capital | 2 | ||
| 2800 | Equity partner A at the beginning of the year | 28 | ||
| 2810 | Contributions to equity/equity withdrawals partner A | 28 | ||
| 2820 | Private account partner A | 28 | ||
| 2831 | Profit / Loss for the year partner A | 28 | ||
| 2850 | Equity sponsor A at the beginning of the year | 28 | ||
| 2860 | Contributions to equity/equity withdrawals sponsor A | 28 | ||
| 2870 | Private account sponsor A | 28 | ||
| 2881 | Profit / Loss for the year sponsor A | 28 | ||
| 297 | Profit/loss for the period | 28 | ||
| 28 | Equity | 2 | ||
| 2 | Total liabilities | 00 | 1 | |
| PROFIT & LOSS STATEMENT | ||||
| 3000 | Earnings from own products | 30 | ||
| 3200 | Earnings from resale | 30 | ||
| 3400 | Earnings from services rendered | 30 | ||
| 3600 | Other revenues and services | 30 | ||
| 3710 | Own consumption | 30 | ||
| 3800 | Decrease in revenues | 30 | ||
| 3805 | Losses on accounts receivable, credit variation | 30 | ||
| 30 | Net revenues from supplies and services | 3 | ||
| 3900 | Change in inventories of in-process products | 39 | ||
| 3901 | Change in inventories of finished products | 39 | ||
| 3940 | Non-invoiced services variations | 39 | ||
| 39 | Change in inventories and Non-invoiced services | 3 | ||
| 3 | Revenues from supplies and services | E1 | ||
| 4000 | Raw materials | 4 | ||
| 4200 | Expenses for goods for resale | 4 | ||
| 4400 | Third party expenses | 4 | ||
| 4500 | Energy consumption for production | 4 | ||
| 4900 | Reduction of costs | 4 | ||
| 4 | Costs for material, goods, services and energy | E1 | ||
| E1 | Gross operating result after deducting costs for materials and goods | E2 | ||
| 5000 | Salaries | 5 | ||
| 5700 | Contribution to old age insurance and unemployment | 5 | ||
| 5710 | Family equalization fund | 5 | ||
| 5720 | Contribution to pension funds | 5 | ||
| 5730 | Contribution to accident insurance | 5 | ||
| 5740 | Contribution to voluntary daily benefits insurance | 5 | ||
| 5790 | Source tax | 5 | ||
| 5800 | Other personnel expenses | 5 | ||
| 5810 | Training of personnel | 5 | ||
| 5820 | Travel and entertainment expenses effective | 5 | ||
| 5830 | Travel and entertainment expense allowance | 5 | ||
| 5900 | Temporary staff | 5 | ||
| 5 | Personnel expenses | E2 | ||
| E2 | Gross operating result after deducting personnel expenses | E3 | ||
| 6000 | Rental | 60 | ||
| 6040 | Cleaning of facilities | 60 | ||
| 60 | Rental | 6 | ||
| 6100 | Maintenance, repairs and replacement of tangible assets | 61 | ||
| 6105 | Leasing costs tangible assets | 61 | ||
| 61 | Maintenance, repairs and replacement of tangible assets | 6 | ||
| 6200 | Repairs | 62 | ||
| 6210 | Fuel | 62 | ||
| 6220 | Car insurance | 62 | ||
| 6260 | Car leasing and rental | 62 | ||
| 6270 | Car costs - private part | 62 | ||
| 6282 | Transportation expenses | 62 | ||
| 62 | Vehicle and transportation expenses | 6 | ||
| 6300 | Insurance for damage of items | 63 | ||
| 63 | Insurance for damage of items | 6 | ||
| 6402 | Electricity | 64 | ||
| 6410 | Heating expenses | 64 | ||
| 6430 | Water | 64 | ||
| 6460 | Garbage | 64 | ||
| 64 | Energy and disposal costs | 6 | ||
| 6500 | Office supplies | 65 | ||
| 6503 | Technical magazines, newspapers, periodicals | 65 | ||
| 6510 | Telephone / internet | 65 | ||
| 6511 | Hosting at third-party | 65 | ||
| 6513 | Postal charges | 65 | ||
| 6570 | IT charges including leasing | 65 | ||
| 6580 | Licenses and updates | 65 | ||
| 6583 | Consumables | 65 | ||
| 65 | Administrative and IT costs | 6 | ||
| 6600 | Advertising | 66 | ||
| 6642 | Gifts to customers | 66 | ||
| 66 | Advertising | 6 | ||
| 6700 | Various costs for the financial year | 67 | ||
| 67 | Various costs for the financial year | 6 | ||
| 6 | Other operating expenses, depreciation, value adjustments and financial results | E3 | ||
| E3 | Operating result before depreciation and value adjustments, financial results and taxes (EBITDA) | E4 | ||
| 6800 | Depreciation and value adjustments of fixed assets | 68 | ||
| 68 | Depreciation and value adjustments of fixed assets | E4 | ||
| E4 | Operating result before financial results and taxes (EBIT) | E5 | ||
| 6900 | Costs for bank interest | 69 | ||
| 6940 | Bank costs | 69 | ||
| 6950 | Financial revenue | 69 | ||
| 69 | Financial costs and revenue | E5 | ||
| E5 | Operating result before taxes (EBT) | E6 | ||
| 7000 | Non-operating revenue | 7 | ||
| 7010 | Non-operating costs | 7 | ||
| 7500 | Corporate real estate revenues | 7 | ||
| 7510 | Corporate real estate costs | 7 | ||
| 7 | Non-operating items | E6 | ||
| 8000 | Extraneous costs | 8 | ||
| 8100 | Extraneous revenue | 8 | ||
| 8500 | Extraordinary, unique costs or costs relating to other accounting periods | 8 | ||
| 8510 | Extraordinary, unique revenue or revenue relating to other accounting periods | 8 | ||
| 8 | Results of extraneous, extraordinary or unique character, or for other accounting periods | E6 | ||
| E6 | Profit or loss before taxes | E7 | ||
| 8900 | Direct taxes | 89 | ||
| 89 | Direct taxes | E7 | ||
| E7 | Annual profit or loss | 297 | ||
| 00 | Difference should be = 0 (blank cell) | |||
| 1 | ||||
| COST CENTERS | ||||
| .PAC | Packaging A | INV | ||
| .RM | Raw materials A | INV | ||
| .AM | Auxiliairy materials A | INV | ||
| INV | Total inventories | |||
| ,MAN1 | Maintenance 1 | MAN | ||
| ,MAN2 | Maintenance 2 | MAN | ||
| ,MAN3 | Maintenance 3 | MAN | ||
| MAN | Total maintenance | |||
| ;PB1 | Publicity 1 | PU | ||
| ;PB2 | Publicity 2 | PU | ||
| PU | Total publicity | |||
| VAT Code | Description | %VAT |
|---|---|---|
| Explanations | ||
| V = Sales (200) | ||
| VS = Discount sales and services (235) | ||
| B = Acquisition tax (38x) | ||
| M = Expenses for material and services (400) | ||
| I = Investments and other operating expenses (405) | ||
| K = Corrections (410, 415, 420) | ||
| Z = Not considered (910) | ||
| VAT codes information (do not modify) | ||
| id=vatcodes-che-2024.20230614 | ||
| Last update: 14.06.2023 | ||
| VAT Due | ||
| V0 | Exempt services (220) | |
| V0-E | Export services abroad (221) | |
| V0-T | Transfers in the reporting procedure (225) | |
| V0-N | Non-taxable services (230) | |
| Decrease of income from services, see discounts | ||
| V0-D | Various (280) | |
| V77 | Sales and services 7.7% | 7.70 |
| V81 | Sales and services 8.1% | 8.10 |
| V77-B | Sales and services 7.7% (chosen) | 7.70 |
| V81-B | Sales and services 8.1% (chosen) | 8.10 |
| V25-N | Sales and services 2.5% | 2.50 |
| V26 | Sales and services 2.6% | 2.60 |
| V37 | Sales and services 3.7% | 3.70 |
| V38 | Sales and services 3.8% | 3.80 |
| VS77 | Discount Sales and services 7.7% | 7.70 |
| VS81 | Discount Sales and services 8.1% | 8.10 |
| VS25-N | Discount Sales and services 2.5% | 2.50 |
| VS26 | Discount Sales and services 2.6% | 2.60 |
| VS37 | Discount Sales and services 3.7% | 3.70 |
| VS38 | Discount Sales and services 3.8% | 3.80 |
| Taxable turnover (299) | ||
| F1 | 1. Flat tax rate 2024 | |
| F2 | 2. Flat tax rate 2024 | |
| FS1 | Discount Sales and services 1. Flat tax rate 2024 | |
| FS2 | Discount Sales and services 2. Flat tax rate 2024 | |
| F3 | 1. Flat tax rate 2018 | |
| F4 | 2. Flat tax rate 2018 | |
| FS3 | Discount Sales and services 1. Flat tax rate 2018 | |
| FS4 | Discount Sales and services 2. Flat tax rate 2018 | |
| Total Flat tax rate (322-333) | ||
| B77 | Acquisition tax 7.7% (With VAT/Sales tax) | 7.70 |
| B77-1 | Acquisition tax 7.7% (Without VAT/Sales tax) | 7.70 |
| B77-2 | Acquisition tax 7.7% (VAT/Sales tax amount) | 7.70 |
| B81 | Acquisition tax 8.1% (With VAT/Sales tax) | 8.10 |
| B81-1 | Acquisition tax 8.1% (Without VAT/Sales tax) | 8.10 |
| B81-2 | Acquisition tax 8.1% (VAT/Sales tax amount) | 8.10 |
| Total Tax on purchases (382-383) | ||
| Total VAT Due (399) | ||
| Recoverable VAT | ||
| M0 | Exempt material- and service expenses | |
| I0 | Exempt investment and operating expenses | |
| M77 | Purchase of material and services 7.7% (With VAT/Sales tax) | 7.70 |
| M77-1 | Purchase of material and services 7.7% (Without VAT/Sales tax) | 7.70 |
| M77-2 | Purchase of material and services 7.7% (VAT/Sales tax amount) | 7.70 |
| M81 | Purchase of material and services 8.1% (With VAT/Sales tax) | 8.10 |
| M81-1 | Purchase of material and services 8.1% (Without VAT/Sales tax) | 8.10 |
| M81-2 | Purchase of material and services 8.1% (VAT/Sales tax amount) | 8.10 |
| M25 | Purchase of material and services 2.5% | 2.50 |
| M26 | Purchase of material and services 2.6% | 2.60 |
| M37 | Purchase of material and services 3.7% | 3.70 |
| M38 | Purchase of material and services 3.8% | 3.80 |
| Investment and operating expenses | ||
| I77 | Investment and operating expenses 7.7% | 7.70 |
| I77-1 | Investment and operating expenses 7.7% (Without VAT/Sales tax) | 7.70 |
| I77-2 | Investment and operating expenses 7.7% (VAT/Sales tax amount) | 7.70 |
| I81 | Investment and operating expenses 8.1% | 8.10 |
| I81-1 | Investment and operating expenses 8.1% (Without VAT/Sales tax) | 8.10 |
| I81-2 | Investment and operating expenses 8.1% (VAT/Sales tax amount) | 8.10 |
| I25 | Investment and operating expenses 2.5% | 2.50 |
| I26 | Investment and operating expenses 2.6% | 2.60 |
| I37 | Investment and operating expenses 3.7% | 3.70 |
| I38 | Investment and operating expenses 3.8% | 3.80 |
| Corrections and adjustments | ||
| K77-A | Subsequent adjustment of prior tax 7.7% (410) | 7.70 |
| K81-A | Subsequent adjustment of prior tax 8.1 % (410) | 8.10 |
| K77-B | Corrections of prior tax 7.7% (415) | 7.70 |
| K81-B | Corrections of prior tax 8.1% (415) | 8.10 |
| K77-C | Reductions of the deduction of prior tax 7.7% (420) | 7.70 |
| K81-C | Reductions of the deduction of prior tax 8.1% (420) | 8.10 |
| F1050 | Tax computation according to form Nr. 1050 | |
| F1055 | Tax computation according to form Nr. 1055 | |
| Total Recoverable VAT (479) | ||
| Total VAT payable (500) or VAT credit (510) | ||
| Other financial flows | ||
| Z0-A | Subsidies, tourist taxes collected by the tourism offices, contributions to the institutions responsible for the elimination of waste and for the supply of water (let. a - c) | |
| Z0 | Gifts, dividends, compensation for damages etc. | |
| Not considered | ||
| Final total for control | ||
Persone giuridiche | IVA aliquota saldo
In this article
Persone giuridiche | IVA aliquota saldo
Persone giuridiche | IVA aliquota saldo
Modello predefinito per gestire la contabilità con IVA l'aliquota saldo. Le impostazioni dei codici IVA e la nuova estensione per il metodo aliquota saldo sono state aggiornate alle nuove normative IVA, in vigore dal 01.01.2024. Banana contabilità Plus prepara tutti i calcoli, il riassunto IVA, il fac-simile formulario IVA e il file Xml per inoltrare i dati elettronicamente sul sito dell'AFC. Apri il modello dalla nostra WebApp, oppure dal programma e salva il file sul tuo computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
Le aziende che hanno una cifra d'affari annua (incluso IVA) non superiore a 5,024 milioni di franchi e con l'imposta dovuta non superiore a 103'000 franchi annui possono optare per l'IVA aliquota saldo, dietro richiesta e autorizzazione dall'AFC.
Maggiori informazioni sono disponibili sul sito della Confederazione alla pagina Aliquote saldo e aliquote forfettarie in materia di IVA.
Nel modello di Banana Contabilità Plus, il piano contabile e la tabella Codici IVA hanno tutte le impostazioni per gestire l'IVA in Svizzera con l'aliquota saldo.
Puoi decidere se nelle registrazioni:
- Avere la scomposizione IVA su ogni registrazione
Prima di iniziare a registrare, inserisci le tue aliquote IVA nella tabella Codici IVA e inserisci "SÌ" nella colonna Lordo. Ad ogni registrazione, ci sarà la scomposizione IVA, con l'importo IVA indicato nell'apposita colonna. - Calcolare l'IVA aliquota saldo alla fine del periodo
I Codici IVA devono essere inseriti nel dialogo del calcolo IVA, presente nell'estensione di Banana Contabilità Plus. Le registrazioni verranno registrate con gli importi al lordo IVA e non ci sarà la scomposizione degli importi IVA.
Maggiori informazioni sono disponibili alla pagina Formulario IVA - aliquota saldo/forfetaria.
A fine periodo il programma esegue in automatico il calcolo dell'IVA ad aliquota saldo e crea in PDF il fac-simile del formulario ufficiale e il file Xml per l'inoltro elettronico dei dati IVA all'AFC.
Il programma include tante funzioni per lavorare velocemente e ottenere risultati professionali.
Per alcune funzioni è necessario un abbonamento al piano Advanced di Banana contabilità Plus, come per esempio generare il fac-simile o il file XML del Rendiconto IVA, utilizzare le nuove funzioni delle Regole, Filtro e Ordina righe temporaneo. Guarda tutte le funzioni del piano Advanced.
Crea il tuo file
- Apri il modello con la WebApp di Banana Contabilità Plus
- Con il comando File > Proprietà file imposta il periodo, il nome della tua azienda e la moneta di base (puoi fare il budget e la contabilità in qualsiasi moneta desideri).
- Con il comando File > Salva con nome, salva il file. È utile indicare nel nome del file, il nome della Società e l'anno. Per esempio "Bernasconi-Sagl-20xx.ac2".
ATTENZIONE: se chiudi il browser senza salvare, perderai i dati immessi. Salva sempre il file sul tuo computer.
Altre informazioni e approfondimenti:
Template preview
Company SA
Divisa Base: CHF
Contabilità in partita doppia con IVA
| Gruppo | Conto | Descrizione | Somma in |
|---|---|---|---|
| BILANCIO | |||
| ATTIVI | |||
| 1000 | Cassa | 100 | |
| 1020 | Banca | 100 | |
| 1045 | Carte di credito / Carte di debito | 100 | |
| 100 | Liquidità | 10 | |
| 1060 | Titoli | 106 | |
| 106 | Attivi quotati in borsa detenuti a breve termine | 10 | |
| 1090 | Conto di trasferimento | 109 | |
| 1091 | Conto di giro salari | 109 | |
| 1099 | Conto di chiarimento | 109 | |
| 109 | Conti di trasferimento | 10 | |
| 1100 | Crediti da forniture e prestazioni (debitori) | 110 | |
| 1109 | Delcredere | 110 | |
| 110 | Crediti da forniture e prestazioni | 10 | |
| 1140 | Anticipi e prestiti | 114 | |
| 1176 | Imposta preventiva | 114 | |
| 1179 | Imposta alla fonte | 114 | |
| 1180 | Crediti da assicurazioni sociali e istituti di previdenza | 114 | |
| 1190 | Crediti diversi a breve termine | 114 | |
| 1191 | Cauzioni | 114 | |
| 114 | Altri crediti a breve termine | 10 | |
| 1200 | Merce di rivendita | 120 | |
| 1210 | Materia prima | 120 | |
| 1230 | Materia ausiliaria | 120 | |
| 1231 | Materiale di consumo | 120 | |
| 1260 | Prodotti finiti | 120 | |
| 1270 | Prodotti in corso di fabbricazione | 120 | |
| 1280 | Prestazioni di servizi non fatturate | 120 | |
| 120 | Scorte e prestazioni di servizi non fatturate | 10 | |
| 1300 | Costi anticipati | 130 | |
| 1301 | Ricavi da incassare | 130 | |
| 130 | Ratei e risconti attivi | 10 | |
| 10 | Attivo circolante | 1 | |
| 1400 | Titoli | 140 | |
| 1440 | Prestiti | 140 | |
| 1460 | Prestito/Prestito ipotecario a correntista | 140 | |
| 140 | Immobilizzazioni finanziarie | 14 | |
| 1480 | Partecipazioni | 148 | |
| 148 | Partecipazioni | 14 | |
| 1500 | Macchine e attrezzature | 150 | |
| 1510 | Mobilio e installazioni | 150 | |
| 1520 | Macchine ufficio, informatica e tecnologia della comunicazione | 150 | |
| 1530 | Veicoli | 150 | |
| 1540 | Utensili e apparecchiature | 150 | |
| 150 | Immobilizzazioni materiali mobiliari | 14 | |
| 1600 | Immobili aziendali | 160 | |
| 160 | Immobilizzazioni materiali immobiliari | 14 | |
| 1700 | Brevetti, know-how, licenze, diritti e sviluppo | 170 | |
| 1710 | Marchi | 170 | |
| 1712 | Modelli | 170 | |
| 1770 | Goodwill | 170 | |
| 170 | Immobilizzazioni immateriali | 14 | |
| 1850 | Capitale azionario, capitale sociale, diritti di partecipazione o capitale della fondazione non versati | 180 | |
| 180 | Capitale sociale o capitale della fondazione non versato | 14 | |
| 14 | Attivo fisso | 1 | |
| 1 | Totale attivi | 00 | |
| PASSIVI | |||
| 2000 | Debiti per forniture e prestazioni (creditori) | 200 | |
| 2030 | Anticipi da terzi | 200 | |
| 200 | Debiti per forniture e prestazioni | 20 | |
| 2100 | Banca passiva | 210 | |
| 2120 | Impegni leasing finanziari | 210 | |
| 2140 | Altri debiti onerosi | 210 | |
| 210 | Debiti onerosi a breve termine | 20 | |
| 2200 | IVA dovuta | 220 | |
| 2201 | Rendiconto IVA | 220 | |
| 2206 | Imposta preventiva | 220 | |
| 2208 | Imposte dirette | 220 | |
| 2209 | Imposta alla fonte | 220 | |
| 2210 | Altri debiti a breve termine | 220 | |
| 2260 | Debiti verso azionista | 220 | |
| 2269 | Dividendi | 220 | |
| 2270 | Conto corrente AVS, AI, IPG, AD | 220 | |
| 220 | Altri debiti a breve termine | 20 | |
| 2300 | Costi da pagare | 230 | |
| 2301 | Ricavi incassati anticipatamente | 230 | |
| 2330 | Accantonamenti a breve termine | 230 | |
| 230 | Ratei e risconti passivi, accantonamenti a breve termine | 20 | |
| 20 | Capitale di terzi a breve termine | 2A | |
| 2400 | Debiti bancari | 240 | |
| 2420 | Impegni leasing finanziari | 240 | |
| 2430 | Prestiti obbligazionari | 240 | |
| 2450 | Prestiti | 240 | |
| 2451 | Mutui ipotecari | 240 | |
| 240 | Debiti onerosi a lungo termine | 24 | |
| 2500 | Altri debiti a lungo termine (non onerosi) | 250 | |
| 250 | Altri debiti a lungo termine | 24 | |
| 2600 | Accantonamenti | 260 | |
| 260 | Accantonamenti a lungo termine e poste analoghe previste dalla legge | 24 | |
| 24 | Capitale di terzi a lungo termine | 2A | |
| 2A | Capitale dei terzi | 2 | |
| 2800 | Capitale azionario, capitale sociale, diritti di partecipazione o capitale della fondazione | 280 | |
| 280 | Capitale sociale o della fondazione | 28 | |
| 2900 | Aggio alla costituzione o in caso di aumento di capitale | 290 | |
| 2903 | Riserva legale da capitale | 290 | |
| 2950 | Riserva legale da utili | 290 | |
| 2955 | Riserve da rivalutazioni | 290 | |
| 2960 | Riserve facoltative da utili | 290 | |
| 290 | Riserve | 28 | |
| 2965 | Azioni proprie, parti sociali, diritti di partecipazione (posta negativa) | 296 | |
| 296 | Azioni proprie, parti sociali, diritti di partecipazione (posta negativa) | 28 | |
| 2970 | Utile/perdita riportata | 297 | |
| 2979 | Utile/perdita annuale | 297 | |
| 297 | Utile/perdita da bilancio | 28 | |
| 28 | Capitale proprio | 2 | |
| 2 | Totale passivi | 00 | |
| CONTO ECONOMICO | |||
| 3000 | Ricavi prodotti fabbricati | 30 | |
| 3200 | Ricavi merci di rivendita | 30 | |
| 3400 | Ricavi prestazioni di servizi | 30 | |
| 3600 | Altri ricavi e prestazioni di servizi | 30 | |
| 3710 | Consumo proprio | 30 | |
| 3800 | Diminuzione di ricavi | 30 | |
| 3805 | Perdite su debitori, variazione delcredere | 30 | |
| 3809 | IVA aliquota saldo | 30 | |
| 3810 | Commissioni carte di credito/debito | 30 | |
| 30 | Importo netto dei ricavi da forniture e prestazioni | 3 | |
| 3900 | Variazione delle scorte di prodotti finiti | 39 | |
| 3901 | Variazione delle scorte di prodotti in corso di fabbricazione | 39 | |
| 3940 | Variazione prestazioni di servizi non fatturate | 39 | |
| 39 | Variazione delle scorte e delle prestazioni di servizi | 3 | |
| 3 | Ricavo d'esercizio da forniture e prestazioni | E1 | |
| 4000 | Costi materiale per la fabbricazione | 4 | |
| 4200 | Costi delle merci di rivendita | 4 | |
| 4400 | Lavori di terzi / prestazioni di subappaltanti | 4 | |
| 4500 | Consumi energia per la produzione | 4 | |
| 4800 | Diminuzione di costi | 4 | |
| 4 | Costi per il materiale, la merce i servizi e l'energia | E1 | |
| E1 | Utile lordo d'esercizio dopo deduzione dei costi per il materiale e le merci di rivendita | E2 | |
| 5000 | Salari | 5 | |
| 5700 | Contributi AVS/AI/IPG/AD | 5 | |
| 5710 | Contributi cassa assegni familiari | 5 | |
| 5720 | Contributi previdenza professionale obbligatoria | 5 | |
| 5730 | Premi per l'assicurazione infortuni professionali | 5 | |
| 5740 | Assicurazione indennità giornaliera per malattia | 5 | |
| 5790 | Imposta alla fonte | 5 | |
| 5800 | Altri costi del personale | 5 | |
| 5810 | Formazione del personale | 5 | |
| 5820 | Spese di viaggio | 5 | |
| 5830 | Rimborsi spese forfettarie | 5 | |
| 5900 | Prestazioni di terzi | 5 | |
| 5 | Costi per il personale | E2 | |
| E2 | Utile lordo d'esercizio dopo deduzione dei costi per il personale | E3 | |
| 6000 | Costi dei locali | 60 | |
| 6040 | Pulizia locali | 60 | |
| 60 | Costi dei locali | 6 | |
| 6100 | Manutenzioni, riparazioni e sostituzione immobilizzazioni mobiliari | 61 | |
| 6105 | Costi leasing immobilizzazioni mobiliari | 61 | |
| 61 | Manutenzioni, riparazioni, sostituzioni (MRS); leasing di immobilizzazioni materiali mobiliari | 6 | |
| 6200 | Riparazioni | 62 | |
| 6210 | Benzina | 62 | |
| 6220 | Assicurazioni auto | 62 | |
| 6260 | Leasing e noleggio auto | 62 | |
| 6270 | Quota privata dei costi auto | 62 | |
| 6280 | Costi di trasporto | 62 | |
| 62 | Costi auto e di trasporto | 6 | |
| 6300 | Assicurazioni cose, contributi, tasse e autorizzazioni | 63 | |
| 63 | Assicurazioni cose, contributi, tasse e autorizzazioni | 6 | |
| 6402 | Elettricità | 64 | |
| 6410 | Riscaldamento | 64 | |
| 6430 | Acqua | 64 | |
| 6460 | Spazzatura | 64 | |
| 64 | Costi energia e smaltimento | 6 | |
| 6500 | Materiale d'ufficio | 65 | |
| 6503 | Riviste specialistiche, giornali, periodici | 65 | |
| 6510 | Telefono / internet | 65 | |
| 6511 | Hosting presso terzi | 65 | |
| 6513 | Porti (spese postali) | 65 | |
| 6570 | Costi informatici incluso leasing | 65 | |
| 6580 | Costi per licenze ed aggiornamenti | 65 | |
| 6583 | Materiale di consumo | 65 | |
| 65 | Costi amministrativi e informatici | 6 | |
| 6600 | Costi pubblicitari | 66 | |
| 6642 | Regali a clienti | 66 | |
| 66 | Costi pubblicitari | 6 | |
| 6700 | Altri costi d'esercizio | 67 | |
| 67 | Altri costi d'esercizio | 6 | |
| 6 | Costi diversi d'esercizio | E3 | |
| E3 | Risultato d'esercizio prima degli ammortamenti e rettifiche, risultati finanziari e imposte (EBITDA) | E4 | |
| 6800 | Ammortamenti e rettifiche di valore dell'attivo fisso | 68 | |
| 68 | Ammortamenti e rettifiche di valore dell'attivo fisso | E4 | |
| E4 | Risultato d'esercizio prima dei risultati finanziari e delle imposte (EBIT) | E5 | |
| 6900 | Costi per interessi bancari | 69 | |
| 6940 | Spese banca | 69 | |
| 6950 | Ricavi finanziari | 69 | |
| 69 | Costi e ricavi finanziari | E5 | |
| E5 | Risultato d'esercizio prima delle imposte (EBT) | E6 | |
| 7000 | Ricavi attività accessoria | 7 | |
| 7010 | Costi attività accessoria | 7 | |
| 7500 | Ricavi immobili aziendali | 7 | |
| 7510 | Costi immobili aziendali | 7 | |
| 7 | Risultato accessorio d'esercizio | E6 | |
| 8000 | Costi estranei | 8 | |
| 8100 | Ricavi estranei | 8 | |
| 8500 | Costi straordinari, unici o relativi ad altri periodi contabili | 8 | |
| 8510 | Ricavi straordinari, unici o relativi ad altri periodi contabili | 8 | |
| 8 | Risultato estraneo, straordinario, unico o relativo ad altri periodi contabili | E6 | |
| E6 | Utile o perdita prima delle imposte | E7 | |
| 8900 | Imposte dirette | 89 | |
| 89 | Imposte dirette | E7 | |
| E7 | Utile o perdita annuale | 2979 | |
| 00 | Differenza deve essere zero (cella vuota) | ||
| Partitario Clienti e Fornitori | |||
| Partitario clienti | |||
| ;110001 | Bianchi SA | CLI | |
| ;110002 | Rossi Francesco | CLI | |
| ;110003 | John Smith | CLI | |
| ;110004 | Rossier Anne | CLI | |
| ;110005 | Müller AG | CLI | |
| CLI | Totale clienti | ||
| Partitario fornitori | |||
| ;200001 | Alberti Sergio | FOR | |
| ;200002 | Fumagalli Lorenzo | FOR | |
| ;200003 | Color SA | FOR | |
| ;200004 | Martini Sagl | FOR | |
| FOR | Totale fornitori | ||
| CENTRI DI COSTO | |||
| .IMB | Imballaggi A | MAG | |
| .MP | Materie prime A | MAG | |
| .MS | Materie sussidiarie A | MAG | |
| MAG | Totale magazzino | ||
| ,MAN1 | Manutenzione 1 | MAN | |
| ,MAN2 | Manutenzione 2 | MAN | |
| ,MAN3 | Manutenzione 3 | MAN | |
| MAN | Totale spese di manutenzione | ||
| ;PB1 | Pubblicità tipo 1 | PU | |
| ;PB2 | Pubblicità tipo 2 | PU | |
| PU | Totale spese di pubblicità |
| Cod. IVA | Descrizione | %IVA |
|---|---|---|
| Spiegazioni (Cifra) | ||
| V = Cifra d'affari (Vendite e servizi) (200) | ||
| VS = Sconti su vendite e servizi (235) | ||
| B = Imposta sull’acquisto (38x) | ||
| M = Acquisti materiale e prestazioni di servizio (400) | ||
| I = Investimenti o costi d'esercizio (405) | ||
| K= Correzioni (410, 415 420) | ||
| Z = Fuori campo (910) | ||
| Informazioni codici iva (non modificare) | ||
| id=vatcodes-chi-2024.20230614 | ||
| Ultimo aggiornamento: 14.06.2023 | ||
| IVA dovuta | ||
| V0 | Prestazioni esenti (220) | |
| V0-E | Prestazioni all'estero (221) | |
| V0-T | Trasferimenti (225) | |
| V0-N | Prestazioni non imponibili (230) | |
| Diminuzioni della controprestazione vedi sconti | ||
| V0-D | Diversi (280) | |
| V77 | Vendite e servizi 7.7% | 7.70 |
| V81 | Vendite e servizi 8.1% | 8.10 |
| V77-B | Vendite e servizi 7.7% (optati ) | 7.70 |
| V81-B | Vendite e servizi 8.1% (optati ) | 8.10 |
| V25-N | Vendite e servizi 2.5% | 2.50 |
| V26 | Vendite e servizi 2.6% | 2.60 |
| V37 | Vendite e servizi 3.7% | 3.70 |
| V38 | Vendite e servizi 3.8% | 3.80 |
| VS77 | Sconto su vendite e servizi 7.7% | 7.70 |
| VS81 | Sconto su vendite e servizi 8.1% | 8.10 |
| VS25-N | Sconto su vendite e servizi 2.5% | 2.50 |
| VS26 | Sconto su vendite e servizi 2.6% | 2.60 |
| VS37 | Sconto su vendite e servizi 3.7% | 3.70 |
| VS38 | Sconto su vendite e servizi 3.8% | 3.80 |
| Cifra d’affari imponibile complessiva (299) | ||
| F1 | 1. Aliquota saldo 2024 | |
| F2 | 2. Aliquota saldo 2024 | |
| FS1 | Sconto su vendite e servizi 1. Aliquota saldo 2024 | |
| FS2 | Sconto su vendite e servizi 2. Aliquota saldo 2024 | |
| F3 | 1. Aliquota saldo 2018 | |
| F4 | 2. Aliquota saldo 2018 | |
| FS3 | Sconto su vendite e servizi 1. Aliquota saldo 2018 | |
| FS4 | Sconto su vendite e servizi 2. Aliquota saldo 2018 | |
| Totale cifra d'affari aliquota saldo (322-333) | ||
| B77 | Imposta sull'acquisto 7.7% (incluso IVA) | 7.70 |
| B77-1 | Imposta sull'acquisto 7.7% (escluso IVA) | 7.70 |
| B77-2 | Imposta sull'acquisto 7.7% (importo IVA) | 7.70 |
| B81 | Imposta sull'acquisto 8.1% (incluso IVA) | 8.10 |
| B81-1 | Imposta sull'acquisto 8.1% (escluso IVA) | 8.10 |
| B81-2 | Imposta sull'acquisto 8.1% (importo IVA) | 8.10 |
| Imposta sull’acquisto (382-383) | ||
| Totale dell’imposta dovuta (399) | ||
| IVA rimborsabile | ||
| M0 | Acquisti esenti | |
| I0 | Investimenti e costi d'esercizio esenti | |
| M77 | Acquisti merce e servizi 7.7% (incluso IVA) | 7.70 |
| M77-1 | Acquisti merce e servizi 7.7% (escluso IVA) | 7.70 |
| M77-2 | Acquisti merce e servizi 7.7% (importo IVA) | 7.70 |
| M81 | Acquisti merce e servizi 8.1% (incluso IVA) | 8.10 |
| M81-1 | Acquisti merce e servizi 8.1% (escluso IVA) | 8.10 |
| M81-2 | Acquisti merce e servizi 8.1% (importo IVA) | 8.10 |
| M25 | Acquisti merce e servizi 2.5% | 2.50 |
| M26 | Acquisti merce e servizi 2.6% | 2.60 |
| M37 | Acquisti merce e servizi 3.7% | 3.70 |
| M38 | Acquisti merce e servizi 3.8% | 3.80 |
| Costi d'esercizio e investimenti | ||
| I77 | Investimenti e costi d'esercizio 7.7% | 7.70 |
| I77-1 | Investimenti e costi d'esercizio 7.7% (escluso IVA) | 7.70 |
| I77-2 | Investimenti e costi d'esercizio 7.7% (Importo IVA) | 7.70 |
| I81 | Investimenti e costi d'esercizio 8.1% | 8.10 |
| I81-1 | Investimenti e costi d'esercizio 8.1% (escluso IVA) | 8.10 |
| I81-2 | Investimenti e costi d'esercizio 8.1% (Importo IVA) | 8.10 |
| I25 | Investimenti e costi d'esercizio 2.5% | 2.50 |
| I26 | Investimenti e costi d'esercizio 2.6% | 2.60 |
| I37 | Investimenti e costi d'esercizio 3.7% | 3.70 |
| I38 | Investimenti e costi d'esercizio 3.8% | 3.80 |
| Correzioni e Rettifiche | ||
| K77-A | Sgravio fiscale successivo 7.7% (410) | 7.70 |
| K81-A | Sgravio fiscale successivo 8.1% (410) | 8.10 |
| K77-B | Correzioni dell’imposta precedente 7.7% (415) | 7.70 |
| K81-B | Correzioni dell’imposta precedente 8.1% (415) | 8.10 |
| K77-D | Riduzioni della deduzione dell’imposta precedente 7.7% (420) | 7.70 |
| K81-D | Riduzioni della deduzione dell’imposta precedente 8.1% (420) | 8.10 |
| F1050 | Computo dell'imposta secondo modulo n. 1050 | |
| F1055 | Computo dell'imposta secondo modulo n. 1055 | |
| Totale Iva rimborsabile (479) | ||
| Totale da versare (500) o da ricevere (510) | ||
| Altri flussi finanziari | ||
| Z0-A | Sussidi, tasse turistiche incassate da uffici turistici, contributi per lo smaltimento dei rifiuti e le aziende fornitrici d'acqua | |
| Z0 | Doni, dividendi, risarcimenti dei danni ecc. | |
| Fuori campo | ||
| Totale finale per controllo | ||
| Gruppo | Articolo | Descrizione | Somma in |
|---|---|---|---|
| AD-1 | Sedie categoria A | 10 | |
| AD-2 | Sedie categoria B | 10 | |
| 10 | Totale sedie categoria A e B | ||
| AB-1 | Tavoli categoria A | 12 | |
| AB-2 | Tavoli categoria B | 12 | |
| 12 | Totale tavoli categoria A e B | ||
Small businesses | Double-entry bookkeeping | SME
In this article
Small businesses | Double-entry bookkeeping | SME
Small businesses | Double-entry bookkeeping | SME
The template, already set up with an SME chart of accounts, offers a simple and optimal structure and allows you to start recording transactions right away. The program automatically provides account cards, VAT report with the new 2024 rates (Advanced plan only), balance sheet, and profit and loss statement. Open the template from our WebApp or from the program and save the file to your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
The program includes many features to work quickly and achieve professional results:
- Import data from bank statements
- Create and print invoices with Swiss QR code
- Set up Rules to save and automate the completion of transactions imported from bank statements.
- Manage VAT according to the new VAT rates
- Manage cost centers , customizable to your needs to view specific details of certain accounts.
- Create budgets and financial forecasts
- Print all the reports you need : Bilanci, Giornale, Schede conto, Rendiconti IVA, Fatture aperte e tanto altro ancora.
For VAT management with the new rates, you can find detailed information on the web pages VAT Management
Some features require a subscription to the Advanced plan of Banana Accounting Plus , such as generating a preview or the XML file for the VAT report, and using the new Rules, Filter, and Temporary Sort features. See all the features of the Advanced plan .
Create your file
- Open the template with the Banana Accounting Plus WebApp
- Using the command File > File and accounting properties, set the period, your company name, and the base currency (you can do budgeting and accounting in any currency you like).
- Using the command File > Save as, save the file. It's helpful to include the company name and the year in the file name. For example, "Rossi-SA-20xx.ac2".
WARNING: if you close the browser without saving, you will lose the entered data. Always save the file to your computer.
In our Documentation you will find all the information and insights to manage your accounting efficiently:
Template preview
Company XX
Accounting 2024
Basic Currency: CHF
Double-entry with VAT/Sales tax
| Group | Account | Description | Sum In | Gr1 |
|---|---|---|---|---|
| BALANCE SHEET | ||||
| ASSETS | ||||
| 1000 | Cash on hand | 10 | ||
| 1010 | Postal account | 10 | ||
| 1020 | Bank account | 10 | ||
| 1090 | Internal transfers | 10 | ||
| 1091 | Transfer account for salaries | 10 | ||
| 1099 | Amounts to be clarified | 10 | ||
| 1100 | Due from Clients or Debtors | 10 | ||
| 1176 | Withholding tax | 10 | ||
| 1199 | Securities | 10 | ||
| 1300 | Prepaid expenses | 10 | ||
| 10 | Current assets | 1 | ||
| 1500 | Machinery | 14 | ||
| 1510 | Office equipment | 14 | ||
| 1512 | Store fixtures | 14 | ||
| 1520 | Office machinery | 14 | ||
| 1521 | IT Hardware | 14 | ||
| 1526 | Software | 14 | ||
| 1530 | Vehicles | 14 | ||
| 14 | Fixed Assets | 1 | ||
| 1 | TOTAL ASSETS | 00 | 1 | |
| LIABILITIES | ||||
| 2000 | Suppliers | 20 | ||
| 2100 | Due to banks short-term | 20 | ||
| 2200 | VAT Due | 20 | ||
| 2201 | VAT according to VAT report | 20 | ||
| 2300 | Accrued expenses | 20 | ||
| 20 | Short-term third party capital | 2 | ||
| 2400 | Due to banks | 24 | ||
| 2500 | Other long-term debts (non-onorous) | 24 | ||
| 2600 | Provisions | 24 | ||
| 24 | Long-term third party capital | 2 | ||
| 2800 | Share capital | 28 | ||
| 2850 | Private account | 28 | ||
| 2970 | Profit (Loss) carried forward | 28 | ||
| 297 | Profit/Loss for the period | 28 | 1 | |
| 28 | Equity | 2 | ||
| 2 | TOTAL LIALIBILITIES | 00 | 1 | |
| PROFIT & LOSS STATEMENT | ||||
| REVENUE | ||||
| 3000 | Earnings from own products | 3 | ||
| 3400 | Earnings from services rendered | 3 | ||
| 3490 | Discounts | 3 | ||
| 3600 | Other revenues and services | 3 | ||
| 3710 | Own consumption | 3 | ||
| 3809 | VAT flat tax rate | 3 | ||
| 3 | TOTAL REVENUE | 02 | 1 | |
| EXPENSES | ||||
| 4000 | Purchases | 4 | ||
| 4 | Total Purchases | 4-6 | ||
| 5600 | Salaries - Administration | 5 | ||
| 5710 | Family allowances | 5 | ||
| 5720 | Contribution to pension funds | 5 | ||
| 5730 | Contribution to accident insurance | 5 | ||
| 5740 | Contribution to voluntary daily benefits insurance | 5 | ||
| 5790 | Source tax | 5 | ||
| 5820 | Travel and entertainment expenses effective | 5 | ||
| 5830 | Travel and entertainment expense allowance | 5 | ||
| 5880 | Other personal expenses | 5 | ||
| 5900 | Temporary staff | 5 | ||
| 5 | Total expenses for personnel | 4-6 | 1 | |
| 6000 | Rental | 6 | ||
| 6030 | Incidental rent costs | 6 | ||
| 6100 | Maintenance, repairs and replacement of tangible assets | 6 | ||
| 6200 | Repairs & maintenance vehicles | 6 | ||
| 6210 | Vehicle fuel | 6 | ||
| 6220 | Vehicle insurance | 6 | ||
| 6282 | Transportation expenses | 6 | ||
| 6300 | Insurance for damage of items | 6 | ||
| 6400 | Energy and disposal costs | 6 | ||
| 6500 | Office supplies | 6 | ||
| 6503 | Technical magazines, newspapers, periodicals | 6 | ||
| 6510 | Phone | 6 | ||
| 6511 | Hosting at third-party | 6 | ||
| 6513 | Postal charges | 6 | ||
| 6520 | Fees and contributions | 6 | ||
| 6521 | Donations | 6 | ||
| 6530 | Book-keeping fees | 6 | ||
| 6574 | Small investments | 6 | ||
| 6583 | Consumables | 6 | ||
| 6600 | Advertising | 6 | ||
| 6641 | Customer support | 6 | ||
| 6642 | Gifts to customers | 6 | ||
| 6800 | Depreciation and value adjustments of fixed assets | 6 | ||
| 6900 | Financial costs | 6 | ||
| 6950 | Financial revenue | 6 | ||
| 8900 | Cantonal and communal taxes | 6 | ||
| 6 | Total general expenses | 4-6 | 1 | |
| 4-6 | TOTAL EXPENSES | 02 | ||
| 02 | Profit/Loss for Profit & Loss Statement | 297 | 1 | |
| 00 | Difference should be = 0 (blank cell) | |||
| COST CENTERS | ||||
| .PAC | Packaging A | INV | ||
| .RM | Raw materials A | INV | ||
| .AM | Auxiliairy materials A | INV | ||
| INV | Total inventories | |||
| ,MAN1 | Maintenance 1 | MAN | ||
| ,MAN2 | Maintenance 2 | MAN | ||
| ,MAN3 | Maintenance 3 | MAN | ||
| MAN | Total maintenance | |||
| ;PB1 | Publicity 1 | PU | ||
| ;PB2 | Publicity 2 | PU | ||
| PU | Total publicity | |||
| VAT Code | Description | %VAT |
|---|---|---|
| Explanations | ||
| V = Sales (200) | ||
| VS = Discount sales and services (235) | ||
| B = Acquisition tax (38x) | ||
| M = Expenses for material and services (400) | ||
| I = Investments and other operating expenses (405) | ||
| K = Corrections (410, 415, 420) | ||
| Z = Not considered (910) | ||
| VAT codes information (do not modify) | ||
| id=vatcodes-che-2024.20230614 | ||
| Last update: 14.06.2023 | ||
| VAT Due | ||
| V0 | Exempt services (220) | |
| V0-E | Export services abroad (221) | |
| V0-T | Transfers in the reporting procedure (225) | |
| V0-N | Non-taxable services (230) | |
| Decrease of income from services, see discounts | ||
| V0-D | Various (280) | |
| V77 | Sales and services 7.7% | 7.70 |
| V81 | Sales and services 8.1% | 8.10 |
| V77-B | Sales and services 7.7% (chosen) | 7.70 |
| V81-B | Sales and services 8.1% (chosen) | 8.10 |
| V25-N | Sales and services 2.5% | 2.50 |
| V26 | Sales and services 2.6% | 2.60 |
| V37 | Sales and services 3.7% | 3.70 |
| V38 | Sales and services 3.8% | 3.80 |
| VS77 | Discount Sales and services 7.7% | 7.70 |
| VS81 | Discount Sales and services 8.1% | 8.10 |
| VS25-N | Discount Sales and services 2.5% | 2.50 |
| VS26 | Discount Sales and services 2.6% | 2.60 |
| VS37 | Discount Sales and services 3.7% | 3.70 |
| VS38 | Discount Sales and services 3.8% | 3.80 |
| Taxable turnover (299) | ||
| F1 | 1. Flat tax rate 2024 | |
| F2 | 2. Flat tax rate 2024 | |
| FS1 | Discount Sales and services 1. Flat tax rate 2024 | |
| FS2 | Discount Sales and services 2. Flat tax rate 2024 | |
| F3 | 1. Flat tax rate 2018 | |
| F4 | 2. Flat tax rate 2018 | |
| FS3 | Discount Sales and services 1. Flat tax rate 2018 | |
| FS4 | Discount Sales and services 2. Flat tax rate 2018 | |
| Total Flat tax rate (322-333) | ||
| B77 | Acquisition tax 7.7% (With VAT/Sales tax) | 7.70 |
| B77-1 | Acquisition tax 7.7% (Without VAT/Sales tax) | 7.70 |
| B77-2 | Acquisition tax 7.7% (VAT/Sales tax amount) | 7.70 |
| B81 | Acquisition tax 8.1% (With VAT/Sales tax) | 8.10 |
| B81-1 | Acquisition tax 8.1% (Without VAT/Sales tax) | 8.10 |
| B81-2 | Acquisition tax 8.1% (VAT/Sales tax amount) | 8.10 |
| Total Tax on purchases (382-383) | ||
| Total VAT Due (399) | ||
| Recoverable VAT | ||
| M0 | Exempt material- and service expenses | |
| I0 | Exempt investment and operating expenses | |
| M77 | Purchase of material and services 7.7% (With VAT/Sales tax) | 7.70 |
| M77-1 | Purchase of material and services 7.7% (Without VAT/Sales tax) | 7.70 |
| M77-2 | Purchase of material and services 7.7% (VAT/Sales tax amount) | 7.70 |
| M81 | Purchase of material and services 8.1% (With VAT/Sales tax) | 8.10 |
| M81-1 | Purchase of material and services 8.1% (Without VAT/Sales tax) | 8.10 |
| M81-2 | Purchase of material and services 8.1% (VAT/Sales tax amount) | 8.10 |
| M25 | Purchase of material and services 2.5% | 2.50 |
| M26 | Purchase of material and services 2.6% | 2.60 |
| M37 | Purchase of material and services 3.7% | 3.70 |
| M38 | Purchase of material and services 3.8% | 3.80 |
| Investment and operating expenses | ||
| I77 | Investment and operating expenses 7.7% | 7.70 |
| I77-1 | Investment and operating expenses 7.7% (Without VAT/Sales tax) | 7.70 |
| I77-2 | Investment and operating expenses 7.7% (VAT/Sales tax amount) | 7.70 |
| I81 | Investment and operating expenses 8.1% | 8.10 |
| I81-1 | Investment and operating expenses 8.1% (Without VAT/Sales tax) | 8.10 |
| I81-2 | Investment and operating expenses 8.1% (VAT/Sales tax amount) | 8.10 |
| I25 | Investment and operating expenses 2.5% | 2.50 |
| I26 | Investment and operating expenses 2.6% | 2.60 |
| I37 | Investment and operating expenses 3.7% | 3.70 |
| I38 | Investment and operating expenses 3.8% | 3.80 |
| Corrections and adjustments | ||
| K77-A | Subsequent adjustment of prior tax 7.7% (410) | 7.70 |
| K81-A | Subsequent adjustment of prior tax 8.1 % (410) | 8.10 |
| K77-B | Corrections of prior tax 7.7% (415) | 7.70 |
| K81-B | Corrections of prior tax 8.1% (415) | 8.10 |
| K77-C | Reductions of the deduction of prior tax 7.7% (420) | 7.70 |
| K81-C | Reductions of the deduction of prior tax 8.1% (420) | 8.10 |
| F1050 | Tax computation according to form Nr. 1050 | |
| F1055 | Tax computation according to form Nr. 1055 | |
| Total Recoverable VAT (479) | ||
| Total VAT payable (500) or VAT credit (510) | ||
| Other financial flows | ||
| Z0-A | Subsidies, tourist taxes collected by the tourism offices, contributions to the institutions responsible for the elimination of waste and for the supply of water (let. a - c) | |
| Z0 | Gifts, dividends, compensation for damages etc. | |
| Not considered | ||
| Final total for control | ||
Partnerships (general partnerships and limited partnerships) | Double-entry multi-currency accounting | VAT
In this article
Partnerships (general partnerships and limited partnerships) | Double-entry multi-currency accounting | VAT
Partnerships (general partnerships and limited partnerships) | Double-entry multi-currency accounting | VAT
Template for accounting of a partnership with foreign currency accounts and VAT management, using the new rates from 2024. Automated functions simplify and speed up entries, highlight errors, and minimize the margin for mistakes. You can create invoices in foreign currencies as well as in the national currency, send reminders, and generate quotes and cash flow forecasts. Online VAT returns are available with the Advanced plan. Get the balance sheet, income statement, account ledgers, journal, and other reports. Cost/profit centers help monitor performance. The budget feature helps forecast costs, revenues, and future liquidity. Open the template from our WebApp or the program and save the file to your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
Ideal template for a partnership. It includes all the columns and features to manage foreign currency accounts and VAT in compliance with the 2024 regulations. Automatic calculations and exchange rate differences.
Create your file
- Open the template with the Banana Accounting Plus WebApp
- From the File > File Properties menu, set the period, your company's name and the base currency in any currency you prefer.
- From the File > Save As menu, save the file. It is helpful to include the company name and year in the file name. For example "Rossi-SA-20xx.ac2".
- In the Exchange Rates table, set up the foreign currencies always with reference to the base currency and the rates. Opening exchange rates are set only the first time you use Banana Accounting. When moving to a new year, these will be automatically carried forward based on the closing exchange rates entered on 31.12.
WARNING: if you close your browser without saving, you will lose all entered data. Always save the file on your computer.
To reopen the saved file, click File > Open.
For VAT management with the new rates, you can find detailed information on the web page VAT Management.
Some features require a subscription to the Advanced plan of Banana Accounting Plus, such as generating the preview or the XML file for the VAT Report, and using the new features for Rules, Filter, and Temporary Row Sorting. See all features of the Advanced plan.
Accounts Table
In the Accounts table, customize the chart of accounts to your needs and add your customer and supplier accounts with all the necessary data, using the columns in the Address view.
The first time you use Banana Accounting, you need to enter the opening balances in the Opening column, which should match the closing balances from the previous year.
In the following year, when you move to the new accounting period, the program will automatically bring forward the closing balances from the previous year into the Opening column.
Project management can also be done using Segments and Cost Centers.
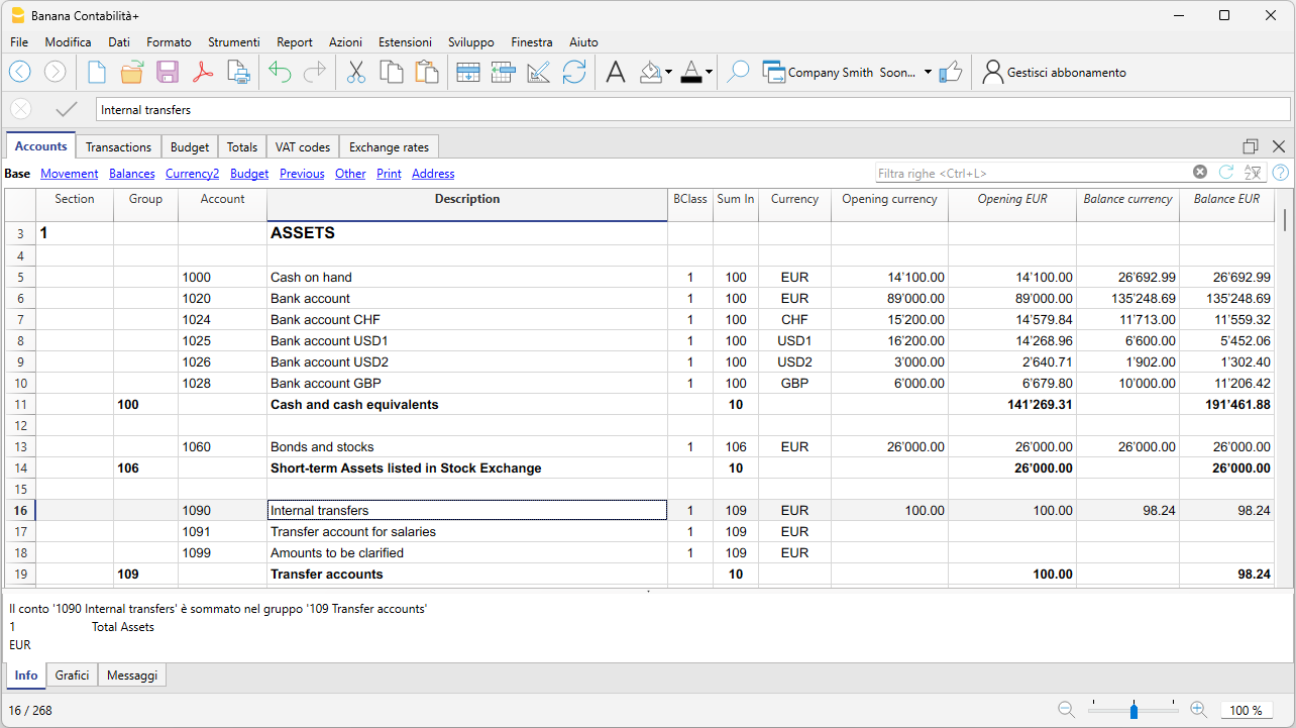
Transactions Table
In the Transactions table, daily entries are recorded. For quick data entry, refer to the web pages Text entry, editing and smart fill, and Recurring transactions.
You can make either simple transactions (one debit and one credit on the same row), or compound transactions (multiple debits and/or credits across several rows).
The Transactions table includes specific columns for multi-currency transactions.

Balance Sheet
The Balance Sheet is generated from the Reports > Enhanced Balance Sheet by Groups menu and can be customized in its presentation. Each layout can be saved through Customizations, allowing you to reuse it as needed (e.g., quarterly, semi-annual balance sheet, audit, etc.).
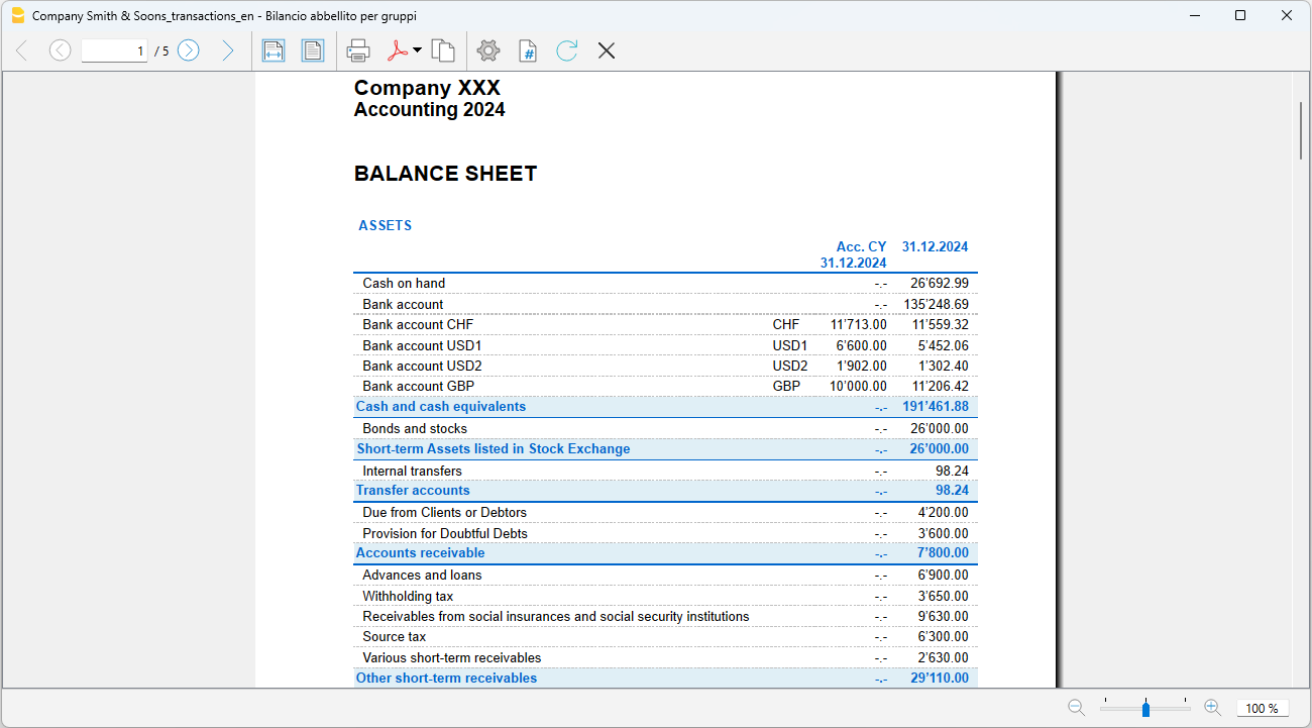
Profit and Loss Statement
The Profit and Loss Statement is generated from the Reports > Enhanced Balance Sheet by Groups menu and can be customized in its presentation. Each layout can be saved through Customizations, allowing you to reuse it as needed (e.g., quarterly, semi-annual balance sheet, audit, etc.).
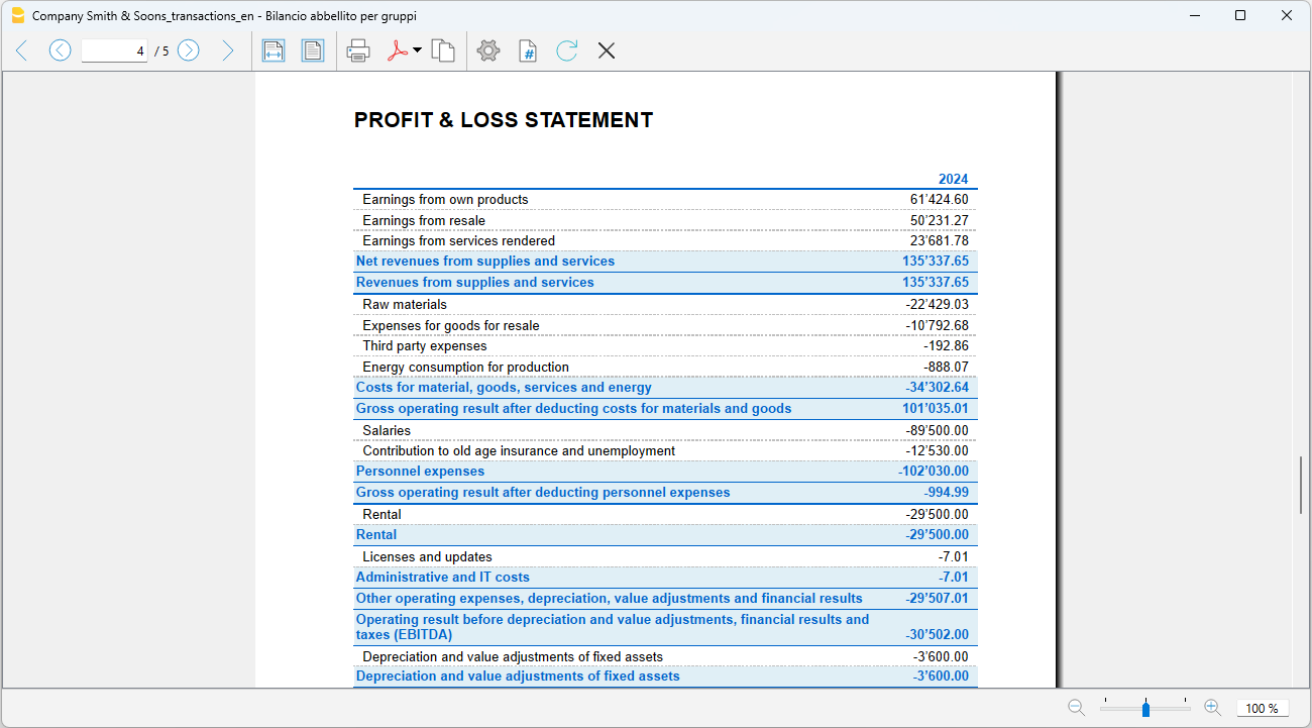
PDF Archive
At the end of the year, or whenever needed, you can archive all your accounting data by creating a PDF file from the File > Create PDF dossier menu.
The PDF dossier can be sent via email to the auditor and reused in case of tax inspections.
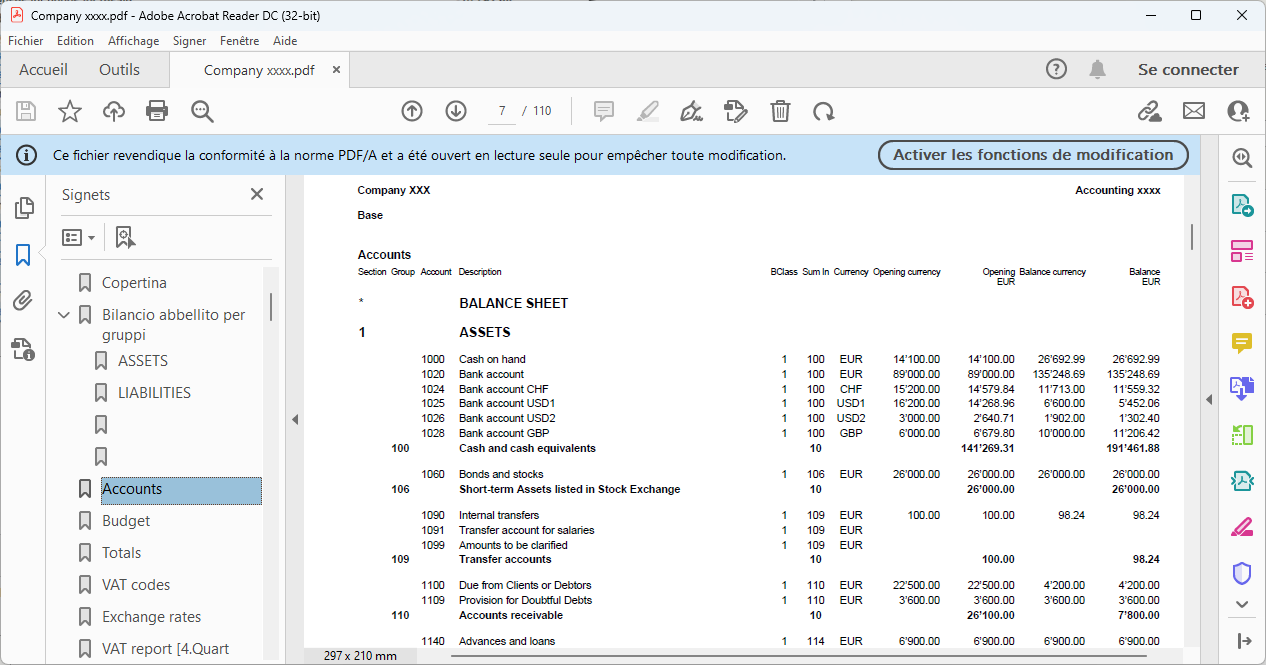
Additional Resources
In our Documentation you will find all insights and topics related to multi-currency accounting, in particular:
Template preview
Company XXX
Accounting 2024
Basic Currency: CHF
Double-entry with foreign currencies and VAT/Sales tax
| Group | Account | Description | Currency | Sum In | Gr1 |
|---|---|---|---|---|---|
| BALANCE SHEET | |||||
| ASSETS | |||||
| 1000 | Cash on hand | CHF | 100 | ||
| 1020 | Bank account | CHF | 100 | ||
| 1024 | Bank account Euro | EUR | 100 | ||
| 1025 | Bank account USD | USD | 100 | ||
| 100 | Cash and cash equivalents | 10 | 1 | ||
| 1060 | Bonds and stocks | CHF | 106 | ||
| 106 | Short-term Assets listed in Stock Exchange | 10 | |||
| 1090 | Internal transfers | CHF | 109 | ||
| 1091 | Transfer account for salaries | CHF | 109 | ||
| 1099 | Amounts to be clarified | CHF | 109 | ||
| 109 | Transfer accounts | 10 | |||
| 1100 | Due from Clients or Debtors | CHF | 110 | ||
| 1109 | Provision for Doubtful Debts | CHF | 110 | ||
| 110 | Accounts receivable | 10 | |||
| 1140 | Advances and loans | CHF | 114 | ||
| 1176 | Withholding tax | CHF | 114 | ||
| 1180 | Receivables from social insurances and social security institutions | CHF | 114 | ||
| 1188 | Source tax | CHF | 114 | ||
| 1190 | Various short-term receivables | CHF | 114 | ||
| 1191 | Securities | CHF | 114 | ||
| 114 | Other short-term receivables | 10 | |||
| 1200 | Goods for resale | CHF | 120 | ||
| 1210 | Raw materials | CHF | 120 | ||
| 1220 | Auxiliary material | CHF | 120 | ||
| 1230 | Consumables | CHF | 120 | ||
| 1260 | Finished products | CHF | 120 | ||
| 1270 | In-process products | CHF | 120 | ||
| 1280 | Non-invoiced services | CHF | 120 | ||
| 120 | Inventories | 10 | 1 | ||
| 1300 | Prepaid expenses | CHF | 130 | ||
| 1301 | Accrued income | CHF | 130 | ||
| 130 | Prepaid Expenses | 10 | 1 | ||
| 10 | Current assets | 1 | 1 | ||
| 1400 | Bonds and stocks | CHF | 140 | ||
| 1440 | Loans | CHF | 140 | ||
| 1460 | Loan to partner | CHF | 140 | ||
| 140 | Financial assets | 14 | |||
| 1480 | Investments | CHF | 148 | ||
| 148 | Investments | 14 | |||
| 1500 | Machinery | CHF | 150 | ||
| 1510 | Office furniture and equipment | CHF | 150 | ||
| 1520 | Office machinery, information and communication technology | CHF | 150 | ||
| 1530 | Motor vehicles | CHF | 150 | ||
| 1540 | Tools and equipment | CHF | 150 | ||
| 150 | Tangible assets | 14 | |||
| 1600 | Commercial buildings | CHF | 160 | ||
| 160 | Tangible fixed asset management | 14 | |||
| 1700 | Patents, know-how, licences, rights and development | CHF | 170 | ||
| 1710 | Brands | CHF | 170 | ||
| 1712 | Models | CHF | 170 | ||
| 1770 | Goodwill | CHF | 170 | ||
| 170 | Intangible fixed assets | 14 | |||
| 1850 | Share capital, rights not paid or non-paid Foundation capital | CHF | 180 | ||
| 180 | Capital or non-paid Foundation capital | 14 | |||
| 14 | Fixed Assets | 1 | |||
| 1 | Total Assets | 00 | |||
| LIABILITIES | |||||
| 2000 | Suppliers or creditors | CHF | 200 | ||
| 2030 | Deposits received | CHF | 200 | ||
| 200 | Suppliers or creditors | 20 | 1 | ||
| 2100 | Due to banks short/term | CHF | 210 | ||
| 2120 | Financial leasing commitments | CHF | 210 | ||
| 2140 | Other onerous debts | CHF | 210 | ||
| 210 | Short-term onorous debts | 20 | |||
| 2200 | VAT Due | CHF | 220 | ||
| 2201 | VAT according to VAT report | CHF | 220 | ||
| 2206 | Withholding tax | CHF | 220 | ||
| 2208 | Direct taxes | CHF | 220 | ||
| 2210 | Other short-term debts | CHF | 220 | ||
| 2260 | Due to partner | CHF | 220 | ||
| 2270 | Social insurances and social security institutions | CHF | 220 | ||
| 2279 | Source tax | CHF | 220 | ||
| 220 | Other short-term debts | 20 | |||
| 2300 | Accrued expenses | CHF | 230 | ||
| 2301 | Next year's revenues collected | CHF | 230 | ||
| 2330 | Short-term provisions | CHF | 230 | ||
| 230 | Accruals and deferred income | 20 | |||
| 20 | Short-term third party capital | 2A | |||
| 2400 | Due to banks | CHF | 240 | ||
| 2420 | Financial leasing commitments | CHF | 240 | ||
| 2430 | Debenture loans | CHF | 240 | ||
| 2450 | Loans | CHF | 240 | ||
| 2451 | Mortgage | CHF | 240 | ||
| 240 | Long-term onorous debts | 24 | |||
| 2500 | Other long-term debts (non-onorous) | CHF | 250 | ||
| 250 | Other long-term debts | 24 | |||
| 2600 | Provisions | CHF | 260 | ||
| 260 | Provisions and similar statutory posts | 24 | |||
| 24 | Long-term third party capital | 2A | |||
| 2A | Third party capital | 2 | |||
| 2800 | Equity partner A at the beginning of the year | CHF | 28 | ||
| 2810 | Contributions to equity/equity withdrawals partner A | CHF | 28 | ||
| 2820 | Private account partner A | CHF | 28 | ||
| 2831 | Profit / Loss for the year partner A | CHF | 28 | ||
| 2850 | Equity sponsor A at the beginning of the year | CHF | 28 | ||
| 2860 | Contributions to equity/equity withdrawals sponsor A | CHF | 28 | ||
| 2870 | Private account sponsor A | CHF | 28 | ||
| 2881 | Profit / Loss for the year sponsor A | CHF | 28 | ||
| 297 | Profit/loss for the period | 28 | |||
| 28 | Equity | 2 | |||
| 2 | Total liabilities | 00 | 1 | ||
| PROFIT & LOSS STATEMENT | |||||
| 3000 | Earnings from own products | CHF | 30 | ||
| 3200 | Earnings from resale | CHF | 30 | ||
| 3400 | Earnings from services rendered | CHF | 30 | ||
| 3600 | Other revenues and services | CHF | 30 | ||
| 3710 | Own consumption | CHF | 30 | ||
| 3800 | Decrease in revenues | CHF | 30 | ||
| 3805 | Losses on accounts receivable, credit variation | CHF | 30 | ||
| 3809 | VAT flat tax rate | CHF | 30 | ||
| 30 | Net revenues from supplies and services | 3 | |||
| 3900 | Change in inventories of in-process products | CHF | 39 | ||
| 3901 | Change in inventories of finished products | CHF | 39 | ||
| 3940 | Non-invoiced services variations | CHF | 39 | ||
| 39 | Change in inventories and Non-invoiced services | 3 | |||
| 3 | Revenues from supplies and services | E1 | |||
| 4000 | Raw materials | CHF | 4 | ||
| 4200 | Expenses for goods for resale | CHF | 4 | ||
| 4400 | Third party expenses | CHF | 4 | ||
| 4500 | Energy consumption for production | CHF | 4 | ||
| 4900 | Reduction of costs | CHF | 4 | ||
| 4 | Costs for material, goods, services and energy | E1 | |||
| E1 | Gross operating result after deducting costs for materials and goods | E2 | |||
| 5000 | Salaries | CHF | 5 | ||
| 5700 | Contribution to old age insurance and unemployment | CHF | 5 | ||
| 5710 | Family equalization fund | CHF | 5 | ||
| 5720 | Contribution to pension funds | CHF | 5 | ||
| 5730 | Contribution to accident insurance | CHF | 5 | ||
| 5740 | Contribution to voluntary daily benefits insurance | CHF | 5 | ||
| 5790 | Source tax | CHF | 5 | ||
| 5800 | Other personnel expenses | CHF | 5 | ||
| 5810 | Training of personnel | CHF | 5 | ||
| 5820 | Travel and entertainment expenses effective | CHF | 5 | ||
| 5830 | Travel and entertainment expense allowance | CHF | 5 | ||
| 5900 | Temporary staff | CHF | 5 | ||
| 5 | Personnel expenses | E2 | |||
| E2 | Gross operating result after deducting personnel expenses | E3 | |||
| 6000 | Rental | CHF | 60 | ||
| 6040 | Cleaning of facilities | CHF | 60 | ||
| 60 | Rental | 6 | |||
| 6100 | Maintenance, repairs and replacement of tangible assets | CHF | 61 | ||
| 6105 | Leasing costs tangible assets | CHF | 61 | ||
| 61 | Maintenance, repairs and replacement of tangible assets | 6 | |||
| 6200 | Repairs | CHF | 62 | ||
| 6210 | Fuel | CHF | 62 | ||
| 6220 | Car insurance | CHF | 62 | ||
| 6260 | Car leasing and rental | CHF | 62 | ||
| 6270 | Car costs - private part | CHF | 62 | ||
| 6282 | Transportation expenses | CHF | 62 | ||
| 62 | Vehicle and transportation expenses | 6 | |||
| 6300 | Insurance for damage of items | CHF | 63 | ||
| 63 | Insurance for damage of items | 6 | |||
| 6402 | Electricity | CHF | 64 | ||
| 6410 | Heating expenses | CHF | 64 | ||
| 6430 | Water | CHF | 64 | ||
| 6460 | Garbage | CHF | 64 | ||
| 64 | Energy and disposal costs | 6 | |||
| 6500 | Office supplies | CHF | 65 | ||
| 6503 | Technical magazines, newspapers, periodicals | CHF | 65 | ||
| 6510 | Telephone / internet | CHF | 65 | ||
| 6511 | Hosting at third-party | CHF | 65 | ||
| 6513 | Postal charges | CHF | 65 | ||
| 6570 | IT charges including leasing | CHF | 65 | ||
| 6580 | Licenses and updates | CHF | 65 | ||
| 6583 | Consumables | CHF | 65 | ||
| 65 | Administrative and IT costs | 6 | |||
| 6600 | Advertising | CHF | 66 | ||
| 6642 | Gifts to customers | CHF | 66 | ||
| 66 | Advertising | 6 | |||
| 6700 | Various costs for the financial year | CHF | 67 | ||
| 67 | Various costs for the financial year | 6 | |||
| 6 | Other operating expenses, depreciation, value adjustments and financial results | E3 | |||
| E3 | Operating result before depreciation and value adjustments, financial results and taxes (EBITDA) | E4 | |||
| 6800 | Depreciation and value adjustments of fixed assets | CHF | 68 | ||
| 68 | Depreciation and value adjustments of fixed assets | E4 | |||
| E4 | Operating result before financial results and taxes (EBIT) | E5 | |||
| 6900 | Costs for bank interest | CHF | 69 | ||
| 6940 | Bank costs | CHF | 69 | ||
| 6949 | Exchange rate loss | CHF | 69 | ||
| 6950 | Financial revenue | CHF | 69 | ||
| 6999 | Exchange rate profit | CHF | 69 | ||
| 69 | Financial costs and revenue | E5 | |||
| E5 | Operating result before taxes (EBT) | E6 | |||
| 7000 | Non-operating revenue | CHF | 7 | ||
| 7010 | Non-operating costs | CHF | 7 | ||
| 7500 | Corporate real estate revenues | CHF | 7 | ||
| 7510 | Corporate real estate costs | CHF | 7 | ||
| 7 | Non-operating items | E6 | |||
| 8000 | Extraneous costs | CHF | 8 | ||
| 8100 | Extraneous revenue | CHF | 8 | ||
| 8500 | Extraordinary, unique costs or costs relating to other accounting periods | CHF | 8 | ||
| 8510 | Extraordinary, unique revenue or revenue relating to other accounting periods | CHF | 8 | ||
| 8 | Results of extraneous, extraordinary or unique character, or for other accounting periods | E6 | |||
| E6 | Profit or loss before taxes | E7 | |||
| 8900 | Direct taxes | CHF | 89 | ||
| 89 | Direct taxes | E7 | |||
| E7 | Annual profit or loss | 297 | |||
| 00 | Difference should be = 0 (blank cell) | ||||
| 1 | |||||
| COST CENTERS | |||||
| .PAC | Packaging A | CHF | INV | ||
| .RM | Raw materials A | CHF | INV | ||
| .AM | Auxiliairy materials A | CHF | INV | ||
| INV | Total inventories | ||||
| ,MAN1 | Maintenance 1 | CHF | MAN | ||
| ,MAN2 | Maintenance 2 | CHF | MAN | ||
| ,MAN3 | Maintenance 3 | CHF | MAN | ||
| MAN | Total maintenance | ||||
| ;PB1 | Publicity 1 | CHF | PU | ||
| ;PB2 | Publicity 2 | CHF | PU | ||
| PU | Total publicity | ||||
| VAT Code | Description | %VAT |
|---|---|---|
| Explanations | ||
| V = Sales (200) | ||
| VS = Discount sales and services (235) | ||
| B = Acquisition tax (38x) | ||
| M = Expenses for material and services (400) | ||
| I = Investments and other operating expenses (405) | ||
| K = Corrections (410, 415, 420) | ||
| Z = Not considered (910) | ||
| VAT codes information (do not modify) | ||
| id=vatcodes-che-2024.20230614 | ||
| Last update: 14.06.2023 | ||
| VAT Due | ||
| V0 | Exempt services (220) | |
| V0-E | Export services abroad (221) | |
| V0-T | Transfers in the reporting procedure (225) | |
| V0-N | Non-taxable services (230) | |
| Decrease of income from services, see discounts | ||
| V0-D | Various (280) | |
| V77 | Sales and services 7.7% | 7.70 |
| V81 | Sales and services 8.1% | 8.10 |
| V77-B | Sales and services 7.7% (chosen) | 7.70 |
| V81-B | Sales and services 8.1% (chosen) | 8.10 |
| V25-N | Sales and services 2.5% | 2.50 |
| V26 | Sales and services 2.6% | 2.60 |
| V37 | Sales and services 3.7% | 3.70 |
| V38 | Sales and services 3.8% | 3.80 |
| VS77 | Discount Sales and services 7.7% | 7.70 |
| VS81 | Discount Sales and services 8.1% | 8.10 |
| VS25-N | Discount Sales and services 2.5% | 2.50 |
| VS26 | Discount Sales and services 2.6% | 2.60 |
| VS37 | Discount Sales and services 3.7% | 3.70 |
| VS38 | Discount Sales and services 3.8% | 3.80 |
| Taxable turnover (299) | ||
| F1 | 1. Flat tax rate 2024 | |
| F2 | 2. Flat tax rate 2024 | |
| FS1 | Discount Sales and services 1. Flat tax rate 2024 | |
| FS2 | Discount Sales and services 2. Flat tax rate 2024 | |
| F3 | 1. Flat tax rate 2018 | |
| F4 | 2. Flat tax rate 2018 | |
| FS3 | Discount Sales and services 1. Flat tax rate 2018 | |
| FS4 | Discount Sales and services 2. Flat tax rate 2018 | |
| Total Flat tax rate (322-333) | ||
| B77 | Acquisition tax 7.7% (With VAT/Sales tax) | 7.70 |
| B77-1 | Acquisition tax 7.7% (Without VAT/Sales tax) | 7.70 |
| B77-2 | Acquisition tax 7.7% (VAT/Sales tax amount) | 7.70 |
| B81 | Acquisition tax 8.1% (With VAT/Sales tax) | 8.10 |
| B81-1 | Acquisition tax 8.1% (Without VAT/Sales tax) | 8.10 |
| B81-2 | Acquisition tax 8.1% (VAT/Sales tax amount) | 8.10 |
| Total Tax on purchases (382-383) | ||
| Total VAT Due (399) | ||
| Recoverable VAT | ||
| M0 | Exempt material- and service expenses | |
| I0 | Exempt investment and operating expenses | |
| M77 | Purchase of material and services 7.7% (With VAT/Sales tax) | 7.70 |
| M77-1 | Purchase of material and services 7.7% (Without VAT/Sales tax) | 7.70 |
| M77-2 | Purchase of material and services 7.7% (VAT/Sales tax amount) | 7.70 |
| M81 | Purchase of material and services 8.1% (With VAT/Sales tax) | 8.10 |
| M81-1 | Purchase of material and services 8.1% (Without VAT/Sales tax) | 8.10 |
| M81-2 | Purchase of material and services 8.1% (VAT/Sales tax amount) | 8.10 |
| M25 | Purchase of material and services 2.5% | 2.50 |
| M26 | Purchase of material and services 2.6% | 2.60 |
| M37 | Purchase of material and services 3.7% | 3.70 |
| M38 | Purchase of material and services 3.8% | 3.80 |
| Investment and operating expenses | ||
| I77 | Investment and operating expenses 7.7% | 7.70 |
| I77-1 | Investment and operating expenses 7.7% (Without VAT/Sales tax) | 7.70 |
| I77-2 | Investment and operating expenses 7.7% (VAT/Sales tax amount) | 7.70 |
| I81 | Investment and operating expenses 8.1% | 8.10 |
| I81-1 | Investment and operating expenses 8.1% (Without VAT/Sales tax) | 8.10 |
| I81-2 | Investment and operating expenses 8.1% (VAT/Sales tax amount) | 8.10 |
| I25 | Investment and operating expenses 2.5% | 2.50 |
| I26 | Investment and operating expenses 2.6% | 2.60 |
| I37 | Investment and operating expenses 3.7% | 3.70 |
| I38 | Investment and operating expenses 3.8% | 3.80 |
| Corrections and adjustments | ||
| K77-A | Subsequent adjustment of prior tax 7.7% (410) | 7.70 |
| K81-A | Subsequent adjustment of prior tax 8.1 % (410) | 8.10 |
| K77-B | Corrections of prior tax 7.7% (415) | 7.70 |
| K81-B | Corrections of prior tax 8.1% (415) | 8.10 |
| K77-C | Reductions of the deduction of prior tax 7.7% (420) | 7.70 |
| K81-C | Reductions of the deduction of prior tax 8.1% (420) | 8.10 |
| F1050 | Tax computation according to form Nr. 1050 | |
| F1055 | Tax computation according to form Nr. 1055 | |
| Total Recoverable VAT (479) | ||
| Total VAT payable (500) or VAT credit (510) | ||
| Other financial flows | ||
| Z0-A | Subsidies, tourist taxes collected by the tourism offices, contributions to the institutions responsible for the elimination of waste and for the supply of water (let. a - c) | |
| Z0 | Gifts, dividends, compensation for damages etc. | |
| Not considered | ||
| Final total for control | ||
| Ref.Currency | Currency | Text |
|---|---|---|
| CHF | EUR | Euro |
| CHF | USD | US Dollar |
Sole proprietorship | Double-entry multi-currency accounting | VAT
In this article
Sole proprietorship | Double-entry multi-currency accounting | VAT
Sole proprietorship | Double-entry multi-currency accounting | VAT
Model for managing accounting with base currency accounts and any foreign currencies, including virtual ones. You set the exchange rate for each currency, and every time you enter a transaction, the program automatically calculates the equivalent amount in the base currency. Exchange rate differences are also handled automatically. Automated checks and controls are available to avoid unrecorded exchange rate differences and other accounting errors or discrepancies. You can also set up accounting in a second currency for reports to be submitted abroad. Automated VAT management for calculations, reports, and electronic VAT returns. Open the template from our WebApp or the program and save the file on your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
The preconfigured chart of accounts allows you to manage accounting for a turnover of at least 500,000 CHF, in accordance with the rules established in the Swiss Code of Obligations (art. 957 and following). The structure of the chart is in a stepped format, allowing you to view the composition of the operating result even in intermediate stages.
Entirely based on double-entry accounting, you register according to international standards and obtain professional results. Unlimited management of foreign currency accounts.
All the settings and functions are available for:
- Creating and printing invoices with the Swiss QR code
- Importing data from bank statements
- Setting up Rules to store and automate the completion of transactions imported from bank statements.
- Managing VAT according to the new VAT rates
- Managing cost centers, customizable according to your needs to get detailed insights on specific accounts.
- Creating budgets and financial forecasts
- Printing all the reports you need: Balance sheets, Journal, Account cards, VAT statements, open invoices and much more.
For VAT management with the new rates, you can find detailed information on the web page VAT Management
Some features require a subscription to the Advanced plan of Banana Accounting Plus, such as generating the preview or the XML file for the VAT report, and using the new functions like Rules, Filter, and Temporary Row Sort. See all features of the Advanced plan.
Create Your File
- Open the template with the Banana Accounting Plus WebApp
- From the File > File Properties menu, set the period, your company name, and the base currency in any currency you like.
- From the File > Save As menu, save the file. It is useful to include the company name and year in the file name. For example "Rossi-SA-20xx.ac2".
- In the Exchange Rates table, set foreign currencies always with reference to the base currency and exchange rates. Opening rates are set only the first time you use Banana Accounting. When moving to a new year, these will be automatically carried forward based on the closing rates entered on 31.12.
WARNING: If you close your browser without saving, you will lose the data entered. Always save the file on your computer.
In our Documentation you will find all the information and insights to manage your accounting effectively:
Template preview
Company XXX
Accounting 2025
Basic Currency: CHF
Double-entry with foreign currencies and VAT/Sales tax
| Group | Account | Description | Currency | Sum In | Gr1 |
|---|---|---|---|---|---|
| BALANCE SHEET | |||||
| ASSETS | |||||
| 1000 | Cash on hand | CHF | 100 | ||
| 1020 | Bank account | CHF | 100 | ||
| 1024 | Bank account Euro | EUR | 100 | ||
| 1025 | Bank account USD | USD | 100 | ||
| 100 | Cash and cash equivalents | 10 | 1 | ||
| 1060 | Bonds and stocks | CHF | 106 | ||
| 106 | Short-term Assets listed in Stock Exchange | 10 | |||
| 1090 | Internal transfers | CHF | 109 | ||
| 1091 | Transfer account for salaries | CHF | 109 | ||
| 1099 | Amounts to be clarified | CHF | 109 | ||
| 109 | Transfer accounts | 10 | |||
| 1100 | Due from Clients or Debtors | CHF | 110 | ||
| 1109 | Provision for Doubtful Debts | CHF | 110 | ||
| 110 | Accounts receivable | 10 | |||
| 1140 | Advances and loans | CHF | 114 | ||
| 1176 | Withholding tax | CHF | 114 | ||
| 1180 | Receivables from social insurances and social security institutions | CHF | 114 | ||
| 1188 | Source tax | CHF | 114 | ||
| 1190 | Various short-term receivables | CHF | 114 | ||
| 1191 | Securities | CHF | 114 | ||
| 114 | Other short-term receivables | 10 | |||
| 1200 | Goods for resale | CHF | 120 | ||
| 1210 | Raw materials | CHF | 120 | ||
| 1220 | Auxiliary material | CHF | 120 | ||
| 1230 | Consumables | CHF | 120 | ||
| 1260 | Finished products | CHF | 120 | ||
| 1270 | In-process products | CHF | 120 | ||
| 1280 | Non-invoiced services | CHF | 120 | ||
| 120 | Inventories | 10 | 1 | ||
| 1300 | Prepaid expenses | CHF | 130 | ||
| 1301 | Accrued income | CHF | 130 | ||
| 130 | Prepaid Expenses | 10 | 1 | ||
| 10 | Current assets | 1 | 1 | ||
| 1400 | Bonds and stocks | CHF | 140 | ||
| 1440 | Loans | CHF | 140 | ||
| 140 | Financial assets | 14 | |||
| 1480 | Investments | CHF | 148 | ||
| 148 | Investments | 14 | |||
| 1500 | Machinery | CHF | 150 | ||
| 1510 | Office furniture and equipment | CHF | 150 | ||
| 1520 | Office machinery, information and communication technology | CHF | 150 | ||
| 1530 | Motor vehicles | CHF | 150 | ||
| 1540 | Tools and equipment | CHF | 150 | ||
| 150 | Tangible assets | 14 | |||
| 1600 | Commercial buildings | CHF | 160 | ||
| 160 | Tangible fixed asset management | 14 | |||
| 14 | Fixed Assets | 1 | |||
| 1 | Total Assets | 00 | |||
| LIABILITIES | |||||
| 2000 | Suppliers or creditors | CHF | 200 | ||
| 2030 | Deposits received | CHF | 200 | ||
| 200 | Suppliers or creditors | 20 | 1 | ||
| 2100 | Due to banks short/term | CHF | 210 | ||
| 2120 | Financial leasing commitments | CHF | 210 | ||
| 2140 | Other onerous debts | CHF | 210 | ||
| 210 | Short-term onorous debts | 20 | |||
| 2200 | VAT Due | CHF | 220 | ||
| 2201 | VAT according to VAT report | CHF | 220 | ||
| 2206 | Withholding tax | CHF | 220 | ||
| 2208 | Direct taxes | CHF | 220 | ||
| 2210 | Other short-term debts | CHF | 220 | ||
| 2270 | Social insurances and social security institutions | CHF | 220 | ||
| 2279 | Source tax | CHF | 220 | ||
| 220 | Other short-term debts | 20 | |||
| 2300 | Accrued expenses | CHF | 230 | ||
| 2301 | Next year's revenues collected | CHF | 230 | ||
| 2330 | Short-term provisions | CHF | 230 | ||
| 230 | Accruals and deferred income | 20 | |||
| 20 | Short-term third party capital | 2A | |||
| 2400 | Due to banks | CHF | 240 | ||
| 2420 | Financial leasing commitments | CHF | 240 | ||
| 2430 | Debenture loans | CHF | 240 | ||
| 2450 | Loans | CHF | 240 | ||
| 2451 | Mortgage | CHF | 240 | ||
| 240 | Long-term onorous debts | 24 | |||
| 2500 | Other long-term debts (non-onorous) | CHF | 250 | ||
| 250 | Other long-term debts | 24 | |||
| 2600 | Provisions | CHF | 260 | ||
| 260 | Provisions and similar statutory posts | 24 | |||
| 24 | Long-term third party capital | 2A | |||
| 2A | Third party capital | 2 | |||
| 2800 | Equity at the beginning of the financial year | CHF | 28 | ||
| 2850 | Private account | CHF | 28 | ||
| 2970 | Profit / Loss for the year | CHF | 28 | ||
| 2891 | Profit/loss for the period | 28 | |||
| 28 | Equity | 2 | |||
| 2 | Total liabilities | 00 | 1 | ||
| PROFIT & LOSS STATEMENT | |||||
| 3000 | Earnings from own products | CHF | 30 | ||
| 3200 | Earnings from resale | CHF | 30 | ||
| 3400 | Earnings from services rendered | CHF | 30 | ||
| 3600 | Other revenues and services | CHF | 30 | ||
| 3700 | Internal work | CHF | 30 | ||
| 3710 | Own consumption | CHF | 30 | ||
| 3800 | Decrease in revenues | CHF | 30 | ||
| 3805 | Losses on accounts receivable, credit variation | CHF | 30 | ||
| 3809 | VAT flat tax rate | CHF | 30 | ||
| 30 | Net revenues from supplies and services | 3 | |||
| 3900 | Change in inventories of in-process products | CHF | 39 | ||
| 3901 | Change in inventories of finished products | CHF | 39 | ||
| 3940 | Non-invoiced services variations | CHF | 39 | ||
| 39 | Change in inventories and Non-invoiced services | 3 | |||
| 3 | Revenues from supplies and services | E1 | |||
| 4000 | Raw materials | CHF | 4 | ||
| 4200 | Expenses for goods for resale | CHF | 4 | ||
| 4400 | Third party expenses | CHF | 4 | ||
| 4500 | Energy consumption for production | CHF | 4 | ||
| 4900 | Reduction of costs | CHF | 4 | ||
| 4 | Costs for material, goods, services and energy | E1 | |||
| E1 | Gross operating result after deducting costs for materials and goods | E2 | |||
| 5000 | Salaries | CHF | 5 | ||
| 5700 | Contribution to old age insurance and unemployment | CHF | 5 | ||
| 5710 | Family equalization fund | CHF | 5 | ||
| 5720 | Contribution to pension funds | CHF | 5 | ||
| 5730 | Contribution to accident insurance | CHF | 5 | ||
| 5740 | Contribution to voluntary daily benefits insurance | CHF | 5 | ||
| 5790 | Source tax | CHF | 5 | ||
| 5800 | Other personnel expenses | CHF | 5 | ||
| 5810 | Training of personnel | CHF | 5 | ||
| 5820 | Travel and entertainment expenses effective | CHF | 5 | ||
| 5830 | Travel and entertainment expense allowance | CHF | 5 | ||
| 5900 | Temporary staff | CHF | 5 | ||
| 5 | Personnel expenses | E2 | |||
| E2 | Gross operating result after deducting personnel expenses | E3 | |||
| 6000 | Rental | CHF | 60 | ||
| 6040 | Cleaning of facilities | CHF | 60 | ||
| 60 | Rental | 6 | |||
| 6100 | Maintenance, repairs and replacement of tangible assets | CHF | 61 | ||
| 6105 | Leasing costs tangible assets | CHF | 61 | ||
| 61 | Maintenance, repairs and replacement of tangible assets | 6 | |||
| 6200 | Repairs | CHF | 62 | ||
| 6210 | Fuel | CHF | 62 | ||
| 6220 | Car insurance | CHF | 62 | ||
| 6260 | Car leasing and rental | CHF | 62 | ||
| 6270 | Car costs - private part | CHF | 62 | ||
| 6282 | Transportation expenses | CHF | 62 | ||
| 62 | Vehicle and transportation expenses | 6 | |||
| 6300 | Insurance for damage of items | CHF | 63 | ||
| 63 | Insurance for damage of items | 6 | |||
| 6402 | Electricity | CHF | 64 | ||
| 6410 | Heating expenses | CHF | 64 | ||
| 6430 | Water | CHF | 64 | ||
| 6460 | Garbage | CHF | 64 | ||
| 64 | Energy and disposal costs | 6 | |||
| 6500 | Office supplies | CHF | 65 | ||
| 6503 | Technical magazines, newspapers, periodicals | CHF | 65 | ||
| 6510 | Telephone / internet | CHF | 65 | ||
| 6511 | Hosting at third-party | CHF | 65 | ||
| 6513 | Postal charges | CHF | 65 | ||
| 6570 | IT charges including leasing | CHF | 65 | ||
| 6580 | Licenses and updates | CHF | 65 | ||
| 6583 | Consumables | CHF | 65 | ||
| 65 | Administrative and IT costs | 6 | |||
| 6600 | Advertising | CHF | 66 | ||
| 6642 | Gifts to customers | CHF | 66 | ||
| 66 | Advertising | 6 | |||
| 6700 | Various costs for the financial year | CHF | 67 | ||
| 67 | Various costs for the financial year | 6 | |||
| 6 | Other operating expenses, depreciation, value adjustments and financial results | E3 | |||
| E3 | Operating result before depreciation and value adjustments, financial results and taxes (EBITDA) | E4 | |||
| 6800 | Depreciation and value adjustments of fixed assets | CHF | 68 | ||
| 68 | Depreciation and value adjustments of fixed assets | E4 | |||
| E4 | Operating result before financial results and taxes (EBIT) | E5 | |||
| 6900 | Costs for bank interest | CHF | 69 | ||
| 6940 | Bank costs | CHF | 69 | ||
| 6949 | Exchange rate loss | CHF | 69 | ||
| 6950 | Financial revenue | CHF | 69 | ||
| 6999 | Exchange rate profit | CHF | 69 | ||
| 69 | Financial costs and revenue | E5 | 1 | ||
| E5 | Operating result before taxes (EBT) | E6 | |||
| 7000 | Non-operating revenue | CHF | 7 | ||
| 7010 | Non-operating costs | CHF | 7 | ||
| 7500 | Corporate real estate revenues | CHF | 7 | ||
| 7510 | Corporate real estate costs | CHF | 7 | ||
| 7 | Non-operating items | E6 | |||
| 8000 | Extraneous costs | CHF | 8 | ||
| 8100 | Extraneous revenue | CHF | 8 | ||
| 8500 | Extraordinary, unique costs or costs relating to other accounting periods | CHF | 8 | ||
| 8510 | Extraordinary, unique revenue or revenue relating to other accounting periods | CHF | 8 | ||
| 8 | Results of extraneous, extraordinary or unique character, or for other accounting periods | E6 | |||
| E6 | Profit or loss before taxes | E7 | |||
| 8900 | Direct taxes | CHF | 89 | ||
| 89 | Direct taxes | E7 | |||
| E7 | Annual profit or loss | 2891 | |||
| 00 | Difference should be = 0 (blank cell) | ||||
| COST CENTERS | |||||
| .PAC | Packaging A | CHF | INV | ||
| .RM | Raw materials A | CHF | INV | ||
| .AM | Auxiliairy materials A | CHF | INV | ||
| INV | Total inventories | ||||
| ,MAN1 | Maintenance 1 | CHF | MAN | ||
| ,MAN2 | Maintenance 2 | CHF | MAN | ||
| ,MAN3 | Maintenance 3 | CHF | MAN | ||
| MAN | Total maintenance | ||||
| ;PB1 | Publicity 1 | CHF | PU | ||
| ;PB2 | Publicity 2 | CHF | PU | ||
| PU | Total publicity | ||||
| VAT Code | Description | %VAT |
|---|---|---|
| Explanations | ||
| V = Sales (200) | ||
| VS = Discount sales and services (235) | ||
| B = Acquisition tax (38x) | ||
| M = Expenses for material and services (400) | ||
| I = Investments and other operating expenses (405) | ||
| K = Corrections (410, 415, 420) | ||
| Z = Not considered (910) | ||
| VAT codes information (do not modify) | ||
| id=vatcodes-che-2024.20230614 | ||
| Last update: 14.06.2023 | ||
| VAT Due | ||
| V0 | Exempt services (220) | |
| V0-E | Export services abroad (221) | |
| V0-T | Transfers in the reporting procedure (225) | |
| V0-N | Non-taxable services (230) | |
| Decrease of income from services, see discounts | ||
| V0-D | Various (280) | |
| V77 | Sales and services 7.7% | 7.70 |
| V81 | Sales and services 8.1% | 8.10 |
| V77-B | Sales and services 7.7% (chosen) | 7.70 |
| V81-B | Sales and services 8.1% (chosen) | 8.10 |
| V25-N | Sales and services 2.5% | 2.50 |
| V26 | Sales and services 2.6% | 2.60 |
| V37 | Sales and services 3.7% | 3.70 |
| V38 | Sales and services 3.8% | 3.80 |
| VS77 | Discount Sales and services 7.7% | 7.70 |
| VS81 | Discount Sales and services 8.1% | 8.10 |
| VS25-N | Discount Sales and services 2.5% | 2.50 |
| VS26 | Discount Sales and services 2.6% | 2.60 |
| VS37 | Discount Sales and services 3.7% | 3.70 |
| VS38 | Discount Sales and services 3.8% | 3.80 |
| Taxable turnover (299) | ||
| F1 | 1. Flat tax rate 2024 | |
| F2 | 2. Flat tax rate 2024 | |
| FS1 | Discount Sales and services 1. Flat tax rate 2024 | |
| FS2 | Discount Sales and services 2. Flat tax rate 2024 | |
| F3 | 1. Flat tax rate 2018 | |
| F4 | 2. Flat tax rate 2018 | |
| FS3 | Discount Sales and services 1. Flat tax rate 2018 | |
| FS4 | Discount Sales and services 2. Flat tax rate 2018 | |
| Total Flat tax rate (322-333) | ||
| B77 | Acquisition tax 7.7% (With VAT/Sales tax) | 7.70 |
| B77-1 | Acquisition tax 7.7% (Without VAT/Sales tax) | 7.70 |
| B77-2 | Acquisition tax 7.7% (VAT/Sales tax amount) | 7.70 |
| B81 | Acquisition tax 8.1% (With VAT/Sales tax) | 8.10 |
| B81-1 | Acquisition tax 8.1% (Without VAT/Sales tax) | 8.10 |
| B81-2 | Acquisition tax 8.1% (VAT/Sales tax amount) | 8.10 |
| Total Tax on purchases (382-383) | ||
| Total VAT Due (399) | ||
| Recoverable VAT | ||
| M0 | Exempt material- and service expenses | |
| I0 | Exempt investment and operating expenses | |
| M77 | Purchase of material and services 7.7% (With VAT/Sales tax) | 7.70 |
| M77-1 | Purchase of material and services 7.7% (Without VAT/Sales tax) | 7.70 |
| M77-2 | Purchase of material and services 7.7% (VAT/Sales tax amount) | 7.70 |
| M81 | Purchase of material and services 8.1% (With VAT/Sales tax) | 8.10 |
| M81-1 | Purchase of material and services 8.1% (Without VAT/Sales tax) | 8.10 |
| M81-2 | Purchase of material and services 8.1% (VAT/Sales tax amount) | 8.10 |
| M25 | Purchase of material and services 2.5% | 2.50 |
| M26 | Purchase of material and services 2.6% | 2.60 |
| M37 | Purchase of material and services 3.7% | 3.70 |
| M38 | Purchase of material and services 3.8% | 3.80 |
| Investment and operating expenses | ||
| I77 | Investment and operating expenses 7.7% | 7.70 |
| I77-1 | Investment and operating expenses 7.7% (Without VAT/Sales tax) | 7.70 |
| I77-2 | Investment and operating expenses 7.7% (VAT/Sales tax amount) | 7.70 |
| I81 | Investment and operating expenses 8.1% | 8.10 |
| I81-1 | Investment and operating expenses 8.1% (Without VAT/Sales tax) | 8.10 |
| I81-2 | Investment and operating expenses 8.1% (VAT/Sales tax amount) | 8.10 |
| I25 | Investment and operating expenses 2.5% | 2.50 |
| I26 | Investment and operating expenses 2.6% | 2.60 |
| I37 | Investment and operating expenses 3.7% | 3.70 |
| I38 | Investment and operating expenses 3.8% | 3.80 |
| Corrections and adjustments | ||
| K77-A | Subsequent adjustment of prior tax 7.7% (410) | 7.70 |
| K81-A | Subsequent adjustment of prior tax 8.1 % (410) | 8.10 |
| K77-B | Corrections of prior tax 7.7% (415) | 7.70 |
| K81-B | Corrections of prior tax 8.1% (415) | 8.10 |
| K77-C | Reductions of the deduction of prior tax 7.7% (420) | 7.70 |
| K81-C | Reductions of the deduction of prior tax 8.1% (420) | 8.10 |
| F1050 | Tax computation according to form Nr. 1050 | |
| F1055 | Tax computation according to form Nr. 1055 | |
| Total Recoverable VAT (479) | ||
| Total VAT payable (500) or VAT credit (510) | ||
| Other financial flows | ||
| Z0-A | Subsidies, tourist taxes collected by the tourism offices, contributions to the institutions responsible for the elimination of waste and for the supply of water (let. a - c) | |
| Z0 | Gifts, dividends, compensation for damages etc. | |
| Not considered | ||
| Final total for control | ||
| Ref.Currency | Currency | Text |
|---|---|---|
| CHF | EUR | Euro |
| CHF | USD | US Dollar |
Legal entities SA and Sagl | Accrual-based subledger | Double-entry multi-currency accounting | VAT
In this article
Legal entities SA and Sagl | Accrual-based subledger | Double-entry multi-currency accounting | VAT
Legal entities SA and Sagl | Accrual-based subledger | Double-entry multi-currency accounting | VAT
Template to be used for the accounting of an SA or SAGL with an annual turnover of at least CHF 500,000 and VAT management. Includes tables and features for handling foreign currencies. You can freely set exchange rates, and the program automatically calculates the equivalent value in the base currency for each transaction. Exchange rate differences and VAT management are fully automated. Additionally, you can set up a second currency for international reports and financial statements, displaying balances in both currencies. Open the template from our WebApp or from the program and save the file on your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
Ideal template for managing accounting with an annual turnover equal to or greater than CHF 500,000. The chart of accounts is structured according to the SME scheme and includes the customer/supplier subledger, suitable for accrual-based accounting. All the settings and features are available for:
All the settings and features are available for:
- Creating and printing invoices with the Swiss QR code
- Importing data from bank statements
- Setting up Rules to store and automate the completion of imported transactions from bank statements.
- Managing VAT according to the new VAT rates
- Managing cost centers, customizable according to your needs to gain specific insights on selected accounts.
- Creating budgets and financial forecasts
- Printing all the reports you need: Balance sheets, Journal, Account cards, VAT reports, Open invoices, and much more.
Create your file
- Open the template with the Banana Accounting Plus WebApp
- From the File > File Properties menu, set the period, your company name, and the base currency in any currency you prefer.
- From the File > Save As menu, save the file. It's useful to include the company name and year in the file name. For example, "Rossi-SA-20xx.ac2".
- In the Exchange Rates table, set the foreign currencies always in reference to the base currency and exchange rates. Opening rates are only set the first time you use Banana Accounting. When transitioning to a new year, they are automatically carried forward based on the closing rates entered on 31.12.
WARNING: If you close the browser without saving, you will lose the entered data. Always save the file on your computer.
For VAT management with the new rates, detailed information is available on the web page VAT Management.
Some features require a subscription to the Advanced plan of Banana Accounting Plus, such as generating previews or the XML file for the VAT report, using the new features like Rules, Filter, and Temporary Row Sort. See all Advanced plan features.
Resources
In our Documentation you’ll find all the information and insights to manage your accounting efficiently:
Template preview
Company XXX
Accounting 2024
Basic Currency: CHF
Double-entry with foreign currencies and VAT/Sales tax
| Group | Account | Description | Currency | Sum In | Gr1 |
|---|---|---|---|---|---|
| BALANCE SHEET | |||||
| ASSETS | |||||
| 1000 | Cash on hand | CHF | 100 | ||
| 1020 | Bank account | CHF | 100 | ||
| 1024 | Bank account Euro | EUR | 100 | ||
| 1025 | Bank account USD | USD | 100 | ||
| 100 | Cash and cash equivalents | 10 | 1 | ||
| 1060 | Bonds and stocks | CHF | 106 | ||
| 106 | Short-term Assets listed in Stock Exchange | 10 | |||
| 1090 | Internal transfers | CHF | 109 | ||
| 1091 | Transfer account for salaries | CHF | 109 | ||
| 1099 | Amounts to be clarified | CHF | 109 | ||
| 109 | Transfer accounts | 10 | |||
| 1100 | Due from Clients or Debitors | CHF | 110 | ||
| 1109 | Provision for Doubtful Debts | CHF | 110 | ||
| 110A | Clients or Debtors | 110 | |||
| 110 | Accounts receivable | 10 | |||
| 1140 | Advances and loans | CHF | 114 | ||
| 1176 | Withholding tax | CHF | 114 | ||
| 1180 | Receivables from social insurances and social security institutions | CHF | 114 | ||
| 1188 | Source tax | CHF | 114 | ||
| 1190 | Various short-term receivables | CHF | 114 | ||
| 1191 | Securities | CHF | 114 | ||
| 114 | Other short-term receivables | 10 | |||
| 1200 | Goods for resale | CHF | 120 | ||
| 1210 | Raw materials | CHF | 120 | ||
| 1220 | Auxiliary material | CHF | 120 | ||
| 1230 | Consumables | CHF | 120 | ||
| 1260 | Finished products | CHF | 120 | ||
| 1270 | In-process products | CHF | 120 | ||
| 1280 | Non-invoiced services | CHF | 120 | ||
| 120 | Inventories | 10 | 1 | ||
| 1300 | Prepaid expenses | CHF | 130 | ||
| 1301 | Accrued income | CHF | 130 | ||
| 130 | Prepaid Expenses | 10 | 1 | ||
| 10 | Current assets | 1 | 1 | ||
| 1400 | Bonds and stocks | CHF | 140 | ||
| 1440 | Loans | CHF | 140 | ||
| 1460 | Loan to share-holder | CHF | 140 | ||
| 140 | Financial assets | 14 | |||
| 1480 | Investments | CHF | 148 | ||
| 148 | Investments | 14 | |||
| 1500 | Machinery | CHF | 150 | ||
| 1510 | Office furniture and equipment | CHF | 150 | ||
| 1520 | Office machinery, information and communication technology | CHF | 150 | ||
| 1530 | Motor vehicles | CHF | 150 | ||
| 1540 | Tools and equipment | CHF | 150 | ||
| 150 | Tangible assets | 14 | |||
| 1600 | Commercial buildings | CHF | 160 | ||
| 160 | Tangible fixed asset management | 14 | |||
| 1700 | Patents, know-how, licences, rights and development | CHF | 170 | ||
| 1710 | Brands | CHF | 170 | ||
| 1712 | Models | CHF | 170 | ||
| 1770 | Goodwill | CHF | 170 | ||
| 170 | Intangible fixed assets | 14 | |||
| 1850 | Share capital, rights not paid or non-paid Foundation capital | CHF | 180 | ||
| 180 | Capital or non-paid Foundation capital | 14 | |||
| 14 | Fixed Assets | 1 | |||
| 1 | Total Assets | 00 | |||
| LIABILITIES | |||||
| 2000 | Suppliers or creditors | CHF | 200 | ||
| 2030 | Deposits received | CHF | 200 | ||
| 200A | Suppliers or creditors | 200 | |||
| 200 | Suppliers or creditors | 20 | 1 | ||
| 2100 | Due to banks short/term | CHF | 210 | ||
| 2120 | Financial leasing commitments | CHF | 210 | ||
| 2140 | Other onerous debts | CHF | 210 | ||
| 210 | Short-term onorous debts | 20 | |||
| 2200 | VAT Due | CHF | 220 | ||
| 2201 | VAT according to VAT report | CHF | 220 | ||
| 2206 | Withholding tax | CHF | 220 | ||
| 2208 | Direct taxes | CHF | 220 | ||
| 2210 | Other short-term debts | CHF | 220 | ||
| 2260 | Due to share-holder | CHF | 220 | ||
| 2261 | Dividends | CHF | 220 | ||
| 2270 | Social insurances and social security institutions | CHF | 220 | ||
| 2279 | Source tax | CHF | 220 | ||
| 220 | Other short-term debts | 20 | |||
| 2300 | Accrued expenses | CHF | 230 | ||
| 2301 | Next year's revenues collected | CHF | 230 | ||
| 2330 | Short-term provisions | CHF | 230 | ||
| 230 | Accruals and deferred income | 20 | |||
| 20 | Short-term third party capital | 2A | |||
| 2400 | Due to banks | CHF | 240 | ||
| 2420 | Financial leasing commitments | CHF | 240 | ||
| 2430 | Debenture loans | CHF | 240 | ||
| 2450 | Loans | CHF | 240 | ||
| 2451 | Mortgage | CHF | 240 | ||
| 240 | Long-term onorous debts | 24 | |||
| 2500 | Other long-term debts (non-onorous) | CHF | 250 | ||
| 250 | Other long-term debts | 24 | |||
| 2600 | Provisions | CHF | 260 | ||
| 260 | Provisions and similar statutory posts | 24 | |||
| 24 | Long-term third party capital | 2A | |||
| 2A | Third party capital | 2 | |||
| 2800 | Share capital, rights, foundation capital | CHF | 280 | ||
| 280 | Capital or capital of the foundation | 28 | |||
| 2900 | Legal reserves | CHF | 290 | ||
| 2940 | Revaluation reserves | CHF | 290 | ||
| 290 | Legal reserves | 28 | |||
| 2950 | Legal reserve from profit | CHF | 295 | ||
| 295 | Legal reserve from profit | 28 | |||
| 2960 | Optional reserves from profit | CHF | 296 | ||
| 296 | Optional reserves from profit | 28 | |||
| 2970 | Profit / Loss carried forward | CHF | 297 | ||
| 29A | Profit / Loss for the year | 297 | |||
| 297 | Profit / Loss from Balance Sheet | 28 | |||
| 2980 | Treasury stock, shares, rights of investment (negative) | CHF | 298 | 1 | |
| 298 | Treasury stock, shares, rights of investment (negative) | 28 | |||
| 28 | Equity | 2 | |||
| 2 | Total liabilities | 00 | |||
| PROFIT & LOSS STATEMENT | |||||
| 3000 | Earnings from own products | CHF | 30 | ||
| 3200 | Earnings from resale | CHF | 30 | ||
| 3400 | Earnings from services rendered | CHF | 30 | ||
| 3600 | Other revenues and services | CHF | 30 | ||
| 3710 | Own consumption | CHF | 30 | ||
| 3800 | Decrease in revenues | CHF | 30 | ||
| 3805 | Losses on accounts receivable, credit variation | CHF | 30 | ||
| 3809 | VAT flat tax rate | CHF | 30 | ||
| 30 | Net revenues from supplies and services | 3 | |||
| 3900 | Change in inventories of in-process products | CHF | 39 | ||
| 3901 | Change in inventories of finished products | CHF | 39 | ||
| 3940 | Non-invoiced services variations | CHF | 39 | ||
| 39 | Change in inventories and Non-invoiced services | 3 | |||
| 3 | Revenues from supplies and services | E1 | |||
| 4000 | Raw materials | CHF | 4 | ||
| 4200 | Expenses for goods for resale | CHF | 4 | ||
| 4400 | Third party expenses | CHF | 4 | ||
| 4500 | Energy consumption for production | CHF | 4 | ||
| 4900 | Reduction of costs | CHF | 4 | ||
| 4 | Costs for material, goods, services and energy | E1 | |||
| E1 | Gross operating result after deducting costs for materials and goods | E2 | |||
| 5000 | Salaries | CHF | 5 | ||
| 5700 | Contribution to old age insurance and unemployment | CHF | 5 | ||
| 5710 | Family equalization fund | CHF | 5 | ||
| 5720 | Contribution to pension funds | CHF | 5 | ||
| 5730 | Contribution to accident insurance | CHF | 5 | ||
| 5740 | Contribution to voluntary daily benefits insurance | CHF | 5 | ||
| 5790 | Source tax | CHF | 5 | ||
| 5800 | Other personnel expenses | CHF | 5 | ||
| 5810 | Training of personnel | CHF | 5 | ||
| 5820 | Travel and entertainment expenses effective | CHF | 5 | ||
| 5830 | Travel and entertainment expense allowance | CHF | 5 | ||
| 5900 | Temporary staff | CHF | 5 | ||
| 5 | Personnel expenses | E2 | |||
| E2 | Gross operating result after deducting personnel expenses | E3 | |||
| 6000 | Rental | CHF | 60 | ||
| 6040 | Cleaning of facilities | CHF | 60 | ||
| 60 | Rental | 6 | |||
| 6100 | Maintenance, repairs and replacement of tangible assets | CHF | 61 | ||
| 6105 | Leasing costs tangible assets | CHF | 61 | ||
| 61 | Maintenance, repairs and replacement of tangible assets | 6 | |||
| 6200 | Repairs | CHF | 62 | ||
| 6210 | Fuel | CHF | 62 | ||
| 6220 | Car insurance | CHF | 62 | ||
| 6260 | Car leasing and rental | CHF | 62 | ||
| 6270 | Car costs - private part | CHF | 62 | ||
| 6282 | Transportation expenses | CHF | 62 | ||
| 62 | Vehicle and transportation expenses | 6 | |||
| 6300 | Insurance for damage of items | CHF | 63 | ||
| 63 | Insurance for damage of items | 6 | |||
| 6402 | Electricity | CHF | 64 | ||
| 6410 | Heating expenses | CHF | 64 | ||
| 6430 | Water | CHF | 64 | ||
| 6460 | Garbage | CHF | 64 | ||
| 64 | Energy and disposal costs | 6 | |||
| 6500 | Office supplies | CHF | 65 | ||
| 6503 | Technical magazines, newspapers, periodicals | CHF | 65 | ||
| 6510 | Telephone / internet | CHF | 65 | ||
| 6511 | Hosting at third-party | CHF | 65 | ||
| 6513 | Postal charges | CHF | 65 | ||
| 6570 | IT charges including leasing | CHF | 65 | ||
| 6580 | Licenses and updates | CHF | 65 | ||
| 6583 | Consumables | CHF | 65 | ||
| 65 | Administrative and IT costs | 6 | |||
| 6600 | Advertising | CHF | 66 | ||
| 6642 | Gifts to customers | CHF | 66 | ||
| 66 | Advertising | 6 | |||
| 6700 | Various costs for the financial year | CHF | 67 | ||
| 67 | Various costs for the financial year | 6 | |||
| 6 | Other operating expenses, depreciation, value adjustments and financial results | E3 | |||
| E3 | Operating result before depreciation and value adjustments, financial results and taxes (EBITDA) | E4 | |||
| 6800 | Depreciation and value adjustments of fixed assets | CHF | 68 | ||
| 68 | Depreciation and value adjustments of fixed assets | E4 | |||
| E4 | Operating result before financial results and taxes (EBIT) | E5 | |||
| 6900 | Costs for bank interest | CHF | 69 | ||
| 6940 | Bank costs | CHF | 69 | ||
| 6949 | Exchange rate loss | CHF | 69 | ||
| 6950 | Financial revenue | CHF | 69 | ||
| 6999 | Exchange rate profit | CHF | 69 | ||
| 69 | Financial costs and revenue | E5 | |||
| E5 | Operating result before taxes (EBT) | E6 | |||
| 7000 | Non-operating revenue | CHF | 7 | ||
| 7010 | Non-operating costs | CHF | 7 | ||
| 7500 | Corporate real estate revenues | CHF | 7 | ||
| 7510 | Corporate real estate costs | CHF | 7 | ||
| 7 | Non-operating items | E6 | |||
| 8000 | Extraneous costs | CHF | 8 | ||
| 8100 | Extraneous revenue | CHF | 8 | ||
| 8500 | Extraordinary, unique costs or costs relating to other accounting periods | CHF | 8 | ||
| 8510 | Extraordinary, unique revenue or revenue relating to other accounting periods | CHF | 8 | ||
| 8 | Results of extraneous, extraordinary or unique character, or for other accounting periods | E6 | |||
| E6 | Profit or loss before taxes | E7 | |||
| 8900 | Direct taxes | CHF | 89 | ||
| 89 | Direct taxes | E7 | |||
| E7 | Annual profit or loss | 29A | |||
| 00 | Difference should be = 0 (blank cell) | ||||
| 1 | |||||
| CLIENTS/DEBTORS | |||||
| 110001 | Company 1 | CHF | DEB1 | ||
| 110002 | Company 2 | CHF | DEB1 | ||
| 110003 | Company 3 | CHF | DEB1 | ||
| DEB1 | Total Clients/Debtors | 110A | |||
| SUPPLIERS/CREDITORS | |||||
| 200001 | Company 1 | CHF | CRE1 | ||
| 200002 | Company 2 | CHF | CRE1 | ||
| 200003 | Company 3 | CHF | CRE1 | ||
| CRE1 | Total suppliers/Creditors | 200A | |||
| COST CENTERS | |||||
| .PAC | Packaging A | CHF | INV | ||
| .RM | Raw materials A | CHF | INV | ||
| .AM | Auxiliairy materials A | CHF | INV | ||
| INV | Total inventories | ||||
| ,MAN1 | Maintenance 1 | CHF | MAN | ||
| ,MAN2 | Maintenance 2 | CHF | MAN | ||
| ,MAN3 | Maintenance 3 | CHF | MAN | ||
| MAN | Total maintenance | ||||
| ;PB1 | Publicity 1 | CHF | PU | ||
| ;PB2 | Publicity 2 | CHF | PU | ||
| PU | Total publicity | ||||
| VAT Code | Description | %VAT |
|---|---|---|
| Explanations | ||
| V = Sales (200) | ||
| VS = Discount sales and services (235) | ||
| B = Acquisition tax (38x) | ||
| M = Expenses for material and services (400) | ||
| I = Investments and other operating expenses (405) | ||
| K = Corrections (410, 415, 420) | ||
| Z = Not considered (910) | ||
| VAT codes information (do not modify) | ||
| id=vatcodes-che-2024.20230614 | ||
| Last update: 14.06.2023 | ||
| VAT Due | ||
| V0 | Exempt services (220) | |
| V0-E | Export services abroad (221) | |
| V0-T | Transfers in the reporting procedure (225) | |
| V0-N | Non-taxable services (230) | |
| Decrease of income from services, see discounts | ||
| V0-D | Various (280) | |
| V77 | Sales and services 7.7% | 7.70 |
| V81 | Sales and services 8.1% | 8.10 |
| V77-B | Sales and services 7.7% (chosen) | 7.70 |
| V81-B | Sales and services 8.1% (chosen) | 8.10 |
| V25-N | Sales and services 2.5% | 2.50 |
| V26 | Sales and services 2.6% | 2.60 |
| V37 | Sales and services 3.7% | 3.70 |
| V38 | Sales and services 3.8% | 3.80 |
| VS77 | Discount Sales and services 7.7% | 7.70 |
| VS81 | Discount Sales and services 8.1% | 8.10 |
| VS25-N | Discount Sales and services 2.5% | 2.50 |
| VS26 | Discount Sales and services 2.6% | 2.60 |
| VS37 | Discount Sales and services 3.7% | 3.70 |
| VS38 | Discount Sales and services 3.8% | 3.80 |
| Taxable turnover (299) | ||
| F1 | 1. Flat tax rate 2024 | |
| F2 | 2. Flat tax rate 2024 | |
| FS1 | Discount Sales and services 1. Flat tax rate 2024 | |
| FS2 | Discount Sales and services 2. Flat tax rate 2024 | |
| F3 | 1. Flat tax rate 2018 | |
| F4 | 2. Flat tax rate 2018 | |
| FS3 | Discount Sales and services 1. Flat tax rate 2018 | |
| FS4 | Discount Sales and services 2. Flat tax rate 2018 | |
| Total Flat tax rate (322-333) | ||
| B77 | Acquisition tax 7.7% (With VAT/Sales tax) | 7.70 |
| B77-1 | Acquisition tax 7.7% (Without VAT/Sales tax) | 7.70 |
| B77-2 | Acquisition tax 7.7% (VAT/Sales tax amount) | 7.70 |
| B81 | Acquisition tax 8.1% (With VAT/Sales tax) | 8.10 |
| B81-1 | Acquisition tax 8.1% (Without VAT/Sales tax) | 8.10 |
| B81-2 | Acquisition tax 8.1% (VAT/Sales tax amount) | 8.10 |
| Total Tax on purchases (382-383) | ||
| Total VAT Due (399) | ||
| Recoverable VAT | ||
| M0 | Exempt material- and service expenses | |
| I0 | Exempt investment and operating expenses | |
| M77 | Purchase of material and services 7.7% (With VAT/Sales tax) | 7.70 |
| M77-1 | Purchase of material and services 7.7% (Without VAT/Sales tax) | 7.70 |
| M77-2 | Purchase of material and services 7.7% (VAT/Sales tax amount) | 7.70 |
| M81 | Purchase of material and services 8.1% (With VAT/Sales tax) | 8.10 |
| M81-1 | Purchase of material and services 8.1% (Without VAT/Sales tax) | 8.10 |
| M81-2 | Purchase of material and services 8.1% (VAT/Sales tax amount) | 8.10 |
| M25 | Purchase of material and services 2.5% | 2.50 |
| M26 | Purchase of material and services 2.6% | 2.60 |
| M37 | Purchase of material and services 3.7% | 3.70 |
| M38 | Purchase of material and services 3.8% | 3.80 |
| Investment and operating expenses | ||
| I77 | Investment and operating expenses 7.7% | 7.70 |
| I77-1 | Investment and operating expenses 7.7% (Without VAT/Sales tax) | 7.70 |
| I77-2 | Investment and operating expenses 7.7% (VAT/Sales tax amount) | 7.70 |
| I81 | Investment and operating expenses 8.1% | 8.10 |
| I81-1 | Investment and operating expenses 8.1% (Without VAT/Sales tax) | 8.10 |
| I81-2 | Investment and operating expenses 8.1% (VAT/Sales tax amount) | 8.10 |
| I25 | Investment and operating expenses 2.5% | 2.50 |
| I26 | Investment and operating expenses 2.6% | 2.60 |
| I37 | Investment and operating expenses 3.7% | 3.70 |
| I38 | Investment and operating expenses 3.8% | 3.80 |
| Corrections and adjustments | ||
| K77-A | Subsequent adjustment of prior tax 7.7% (410) | 7.70 |
| K81-A | Subsequent adjustment of prior tax 8.1 % (410) | 8.10 |
| K77-B | Corrections of prior tax 7.7% (415) | 7.70 |
| K81-B | Corrections of prior tax 8.1% (415) | 8.10 |
| K77-C | Reductions of the deduction of prior tax 7.7% (420) | 7.70 |
| K81-C | Reductions of the deduction of prior tax 8.1% (420) | 8.10 |
| F1050 | Tax computation according to form Nr. 1050 | |
| F1055 | Tax computation according to form Nr. 1055 | |
| Total Recoverable VAT (479) | ||
| Total VAT payable (500) or VAT credit (510) | ||
| Other financial flows | ||
| Z0-A | Subsidies, tourist taxes collected by the tourism offices, contributions to the institutions responsible for the elimination of waste and for the supply of water (let. a - c) | |
| Z0 | Gifts, dividends, compensation for damages etc. | |
| Not considered | ||
| Final total for control | ||
| Ref.Currency | Currency | Text |
|---|---|---|
| CHF | EUR | Euro |
| CHF | USD | US Dollar |
Legal entities SA and Sagl | SMEs | Cash-based accounting
In this article
Legal entities SA and Sagl | SMEs | Cash-based accounting
Legal entities SA and Sagl | SMEs | Cash-based accounting
Model for managing the accounting of an SA or SAGL with an annual turnover equal to or greater than CHF 500,000 and VAT on a cash basis. It includes columns and the Exchange Rates table to handle accounts in foreign currencies. For each currency, you can freely set the exchange rate, and every time you record a transaction, the program automatically calculates the base currency equivalent and exchange rate differences. Specific functions are available for automated checks and controls to ensure your accounting is always accurate. If you need to produce reports and financial statements abroad, you can set up accounting in a second currency, allowing you to have balances in both the base currency and a secondary currency. Automated VAT management. Open the template from our WebApp or the program and save the file to your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
Ideal template for managing the accounting of an SA or Sagl with VAT and foreign currencies, with an annual turnover equal to or greater than CHF 500,000. The chart of accounts is structured according to the SME scheme and includes the customer/supplier subledger, suitable for cash-based accounting. All the settings and features are available for:
- Creating and printing invoices with the Swiss QR code
- Importing data from bank statements
- Setting up Rules to store and automate the completion of imported transactions from bank statements.
- Managing VAT according to the new VAT rates
- Managing cost centers, customizable according to your needs to gain specific insights into selected accounts.
- Creating budgets and financial forecasts
- Printing all the reports you need: Balance Sheets, Journal, Account Cards, VAT Statements, Open Invoices, and much more.
For VAT management with the new rates, you can find detailed information on the page VAT Management.
Some features require a subscription to the Advanced plan of Banana Accounting Plus, such as generating the invoice preview or the XML file for the VAT Statement, using the new Rules, Filter and Temporary Row Sort features. See all the Advanced plan features.
Create your file
- Open the template with the Banana Accounting Plus WebApp
- From the File > File Properties menu, set the period, your company name and the base currency in any currency you prefer.
- From the File > Save As menu, save the file. It's helpful to include the company name and year in the file name. For example, "Rossi-SA-20xx.ac2".
- In the Exchange Rates table, set foreign currencies with reference to the base currency and the exchange rates. Opening rates are set only the first time you use Banana Accounting. When transitioning to a new year, they are automatically carried forward based on the closing rates entered on 31.12.
WARNING: If you close your browser without saving, you will lose the data entered. Always save the file on your computer.
Template preview
Accounting 2025
Basic Currency: CHF
Double-entry with foreign currencies and VAT/Sales tax
| Group | Account | Description | Currency | Sum In | Gr1 |
|---|---|---|---|---|---|
| BALANCE SHEET | |||||
| ASSETS | |||||
| 1000 | Cash on hand | CHF | 100 | ||
| 1020 | Bank account | CHF | 100 | ||
| 1025 | Bank account EUR | EUR | 100 | ||
| 1026 | Bank account USD | USD | 100 | ||
| 1045 | Credit cards / Debit cards | CHF | 100 | ||
| 100 | Cash and cash equivalents | 10 | 1 | ||
| 1060 | Bonds and stocks | CHF | 106 | ||
| 106 | Short-term assets listed in stock exchange | 10 | |||
| 1090 | Internal transfers | CHF | 109 | ||
| 1091 | Transfer account for salaries | CHF | 109 | ||
| 1099 | Amounts to be clarified | CHF | 109 | ||
| 109 | Transfer accounts | 10 | |||
| 1100 | Receivables from deliveries and services | CHF | 110 | ||
| 1109 | Provision for doubtful debts | CHF | 110 | ||
| 110 | Receivables from deliveries and services | 10 | |||
| 1140 | Advances and loans | CHF | 114 | ||
| 1176 | Withholding tax | CHF | 114 | ||
| 1179 | Source tax | CHF | 114 | ||
| 1180 | Receivables from social insurances and social security institutions | CHF | 114 | ||
| 1190 | Various short-term receivables | CHF | 114 | ||
| 1191 | Deposits | CHF | 114 | ||
| 114 | Other short-term receivables | 10 | |||
| 1200 | Goods for resale | CHF | 120 | ||
| 1210 | Raw materials | CHF | 120 | ||
| 1230 | Auxiliary material | CHF | 120 | ||
| 1231 | Consumables | CHF | 120 | ||
| 1260 | Finished products | CHF | 120 | ||
| 1270 | In-process products | CHF | 120 | ||
| 1280 | Non-invoiced services | CHF | 120 | ||
| 120 | Inventories | 10 | 1 | ||
| 1300 | Prepaid expenses | CHF | 130 | ||
| 1301 | Accrued income | CHF | 130 | ||
| 130 | Accrued income and prepaid expenses | 10 | 1 | ||
| 10 | Current assets | 1 | 1 | ||
| 1400 | Bonds and stocks | CHF | 140 | ||
| 1440 | Loans | CHF | 140 | ||
| 1460 | Loans/Mortgages to person involved | CHF | 140 | ||
| 140 | Financial assets | 14 | |||
| 1480 | Participations | CHF | 148 | ||
| 148 | Participations | 14 | |||
| 1500 | Machinery and equipment | CHF | 150 | ||
| 1510 | Furniture and installations | CHF | 150 | ||
| 1520 | Office machines, information and communication technology | CHF | 150 | ||
| 1530 | Vehicles | CHF | 150 | ||
| 1540 | Tools and equipment | CHF | 150 | ||
| 150 | Movable tangible assets | 14 | |||
| 1600 | Commercial buildings | CHF | 160 | ||
| 160 | Fixed tangible assets | 14 | |||
| 1700 | Patents, know-how, licences, rights and development | CHF | 170 | ||
| 1710 | Brands | CHF | 170 | ||
| 1712 | Models | CHF | 170 | ||
| 1770 | Goodwill | CHF | 170 | ||
| 170 | Intangible assets | 14 | |||
| 1850 | Unpaid share capital, nominal capital, participation certificate capital | CHF | 180 | ||
| 180 | Unpaid share capital | 14 | |||
| 14 | Fixed assets | 1 | |||
| 1 | Total assets | 00 | |||
| LIABILITIES | |||||
| 2000 | Suppliers or creditors | CHF | 200 | ||
| 2030 | Advance payments from third parties | CHF | 200 | ||
| 200 | Accounts payable | 20 | 1 | ||
| 2100 | Short-term bank debts | CHF | 210 | ||
| 2120 | Financial leasing commitments | CHF | 210 | ||
| 2140 | Other onerous debts | CHF | 210 | ||
| 210 | Short-term interest-bearing debts | 20 | |||
| 2200 | VAT due | CHF | 220 | ||
| 2201 | VAT settlement account | CHF | 220 | ||
| 2206 | Withholding tax | CHF | 220 | ||
| 2208 | Direct taxes | CHF | 220 | ||
| 2209 | Tax at source | CHF | 220 | ||
| 2210 | Other short-term debts | CHF | 220 | ||
| 2260 | Debts due to person involved | CHF | 220 | ||
| 2269 | Dividends | CHF | 220 | ||
| 2270 | Social insurances and social security institutions | CHF | 220 | ||
| 220 | Other short-term debts | 20 | |||
| 2300 | Accrued expenses | CHF | 230 | ||
| 2301 | Revenues received in advance | CHF | 230 | ||
| 2330 | Short-term provisions | CHF | 230 | ||
| 230 | Accruals and deferred income, short-term provisions | 20 | |||
| 20 | Short-term third party capital | 2A | |||
| 2400 | Bank debts | CHF | 240 | ||
| 2420 | Financial leasing commitments | CHF | 240 | ||
| 2430 | Debenture loans | CHF | 240 | ||
| 2450 | Loans | CHF | 240 | ||
| 2451 | Mortgages | CHF | 240 | ||
| 240 | Long-term interest-bearing debts | 24 | |||
| 2500 | Other long-term debts (not onerous) | CHF | 250 | ||
| 250 | Other long-term debts | 24 | |||
| 2600 | Provisions | CHF | 260 | ||
| 260 | Long-term provisions and similar statutory positions | 24 | |||
| 24 | Long-term third party capital | 2A | |||
| 2A | Third party capital | 2 | |||
| 2800 | Share capital, nominal capital, participation certificate capital | CHF | 280 | ||
| 280 | Share capital | 28 | |||
| 2900 | Premium at foundation or in the event of a capital increase | CHF | 290 | ||
| 2903 | Reserves from capital contributions | CHF | 290 | ||
| 2950 | Legal retained earnings | CHF | 290 | ||
| 2955 | Revaluation reserve | CHF | 290 | ||
| 2960 | Optional reserves from profit | CHF | 290 | ||
| 290 | Reserves | 28 | |||
| 2965 | Treasury stock, shares, rights of investment (negative) | CHF | 296 | ||
| 296 | Treasury stock, shares, rights of investment (negative) | 28 | |||
| 2970 | Profit / Loss carried forward | CHF | 297 | ||
| 2979 | Profit / Loss for the year | 297 | |||
| 297 | Profit / Loss from Balance Sheet | 28 | |||
| 28 | Equity | 2 | |||
| 2 | Total liabilities | 00 | 1 | ||
| PROFIT & LOSS STATEMENT | |||||
| 3000 | Manufactured products revenues | CHF | 30 | ||
| 3200 | Revenues from resale of goods | CHF | 30 | ||
| 3400 | Revenues from provided services | CHF | 30 | ||
| 3600 | Other revenues from deliveries and services | CHF | 30 | ||
| 3710 | Own consumption | CHF | 30 | ||
| 3800 | Decrease in revenues | CHF | 30 | ||
| 3805 | Losses on receivables, changes in value adjustments | CHF | 30 | ||
| 3810 | Credit/debit card fees | CHF | 30 | ||
| 30 | Net revenues from supplies and services | 3 | |||
| 3900 | Changes in finished products inventories | CHF | 39 | ||
| 3901 | Changes in semi-finished products inventories | CHF | 39 | ||
| 3940 | Changes in non-invoiced services value | CHF | 39 | ||
| 39 | Changes in inventories and value of non-invoiced services | 3 | |||
| 3 | Revenues from supplies and services | E1 | |||
| 4000 | Raw materials | CHF | 4 | ||
| 4200 | Costs of goods for resale | CHF | 4 | ||
| 4400 | Expenses for purchased services | CHF | 4 | ||
| 4500 | Energy consumption for production | CHF | 4 | ||
| 4800 | Costs reductions | CHF | 4 | ||
| 4 | Costs for material, goods, services and energy | E1 | |||
| E1 | Gross operating result after deducting costs for materials and goods for resale | E2 | |||
| 5000 | Salaries | CHF | 5 | ||
| 5700 | Contribution to old age insurance and unemployment | CHF | 5 | ||
| 5710 | Family allowance | CHF | 5 | ||
| 5720 | Contribution to pension funds | CHF | 5 | ||
| 5730 | Contribution to accident insurance | CHF | 5 | ||
| 5740 | Contribution to daily sickness benefits insurance | CHF | 5 | ||
| 5790 | Tax at source | CHF | 5 | ||
| 5800 | Other personnel expenses | CHF | 5 | ||
| 5810 | Training of personnel | CHF | 5 | ||
| 5820 | Travel expenses | CHF | 5 | ||
| 5830 | Management flat-rate expenses reimbursement | CHF | 5 | ||
| 5900 | Benefits from third parties | CHF | 5 | ||
| 5 | Personnel expenses | E2 | |||
| E2 | Gross operating result after deduction of personnel expenses | E3 | |||
| 6000 | Rent | CHF | 60 | ||
| 6040 | Cleaning of facilities | CHF | 60 | ||
| 60 | Facility expenses | 6 | |||
| 6100 | Maintenance, repairs and replacement of movable tangible assets | CHF | 61 | ||
| 6105 | Leasing costs tangible assets | CHF | 61 | ||
| 61 | Maintenance, repairs and replacement of movable tangible assets | 6 | |||
| 6200 | Repairs | CHF | 62 | ||
| 6210 | Fuel | CHF | 62 | ||
| 6220 | Car insurance | CHF | 62 | ||
| 6260 | Car leasing and rental | CHF | 62 | ||
| 6270 | Private share of vehicle expenses | CHF | 62 | ||
| 6280 | Transportation expenses | CHF | 62 | ||
| 62 | Vehicle and transportation expenses | 6 | |||
| 6300 | Property insurance, charges, fees, permits | CHF | 63 | ||
| 63 | Property insurance, charges, fees, permits | 6 | |||
| 6402 | Electricity | CHF | 64 | ||
| 6410 | Heating expenses | CHF | 64 | ||
| 6430 | Water | CHF | 64 | ||
| 6460 | Garbage | CHF | 64 | ||
| 64 | Energy and disposal costs | 6 | |||
| 6500 | Office equipment | CHF | 65 | ||
| 6503 | Specialist publications, newspapers, periodicals | CHF | 65 | ||
| 6510 | Telephone | CHF | 65 | ||
| 6512 | Internet | CHF | 65 | ||
| 6513 | Postal charges | CHF | 65 | ||
| 6570 | IT charges including leasing | CHF | 65 | ||
| 6580 | Licenses and updates expenses | CHF | 65 | ||
| 6583 | Consumables | CHF | 65 | ||
| 65 | Administrative and IT expenses | 6 | |||
| 6600 | Advertisements | CHF | 66 | ||
| 6642 | Gifts to customers | CHF | 66 | ||
| 66 | Advertising expenses | 6 | |||
| 6700 | Various operating expenses | CHF | 67 | ||
| 67 | Various operating expenses | 6 | |||
| 6 | Other operating expenses | E3 | |||
| E3 | Operating result before depreciation and value adjustments, financial results and taxes (EBITDA) | E4 | |||
| 6800 | Depreciation and value adjustments of fixed assets | CHF | 68 | ||
| 68 | Depreciation and value adjustments of fixed assets | E4 | |||
| E4 | Operating result before financial results and taxes (EBIT) | E5 | |||
| 6900 | Bank interest fees | CHF | 69 | ||
| 6940 | Bank charges | CHF | 69 | ||
| 6949 | Currency losses | CHF | 69 | ||
| 6950 | Financial revenues | CHF | 69 | ||
| 6999 | Currency gains | CHF | 69 | ||
| 69 | Financial expenses and revenues | E5 | |||
| E5 | Operating result before taxes (EBT) | E6 | |||
| 7000 | Ancillary revenues | CHF | 7 | ||
| 7010 | Ancillary expenses | CHF | 7 | ||
| 7500 | Operational real estate revenues | CHF | 7 | ||
| 7510 | Operational real estate expenses | CHF | 7 | ||
| 7 | Ancillary operating result | E6 | |||
| 8000 | Non-operating costs | CHF | 8 | ||
| 8100 | Non-operating revenues | CHF | 8 | ||
| 8500 | Extraordinary, non-recurring or unrelated to the period expenses | CHF | 8 | ||
| 8510 | Extraordinary, non-recurring or unrelated to the period revenues | CHF | 8 | ||
| 8 | Non-operating, extraordinary, non-recurring or unrelated to the period result | E6 | |||
| E6 | Profit or loss before taxes | E7 | |||
| 8900 | Direct taxes | CHF | 89 | ||
| 89 | Direct taxes | E7 | |||
| E7 | Annual profit or loss | 2979 | 1 | ||
| 00 | Difference should be = 0 (blank cell) | ||||
| CLIENTS AND SUPPLIERS LEDGER | |||||
| Clients ledger | |||||
| ;110001 | Bianchi Ltd. | CHF | CLI | ||
| ;110002 | Rossi Francesco | CHF | CLI | ||
| ;110003 | John Smith | CHF | CLI | ||
| ;110004 | Rossier Anne | CHF | CLI | ||
| ;110005 | Müller Ltd. | CHF | CLI | ||
| CLI | Total clients | ||||
| Suppliers ledger | |||||
| ;200001 | Alberti Sergio | CHF | SUP | ||
| ;200002 | Fumagalli Lorenzo | CHF | SUP | ||
| ;200003 | Color Ltd. | CHF | SUP | ||
| ;200004 | Martini LLC. | CHF | SUP | ||
| SUP | Total suppliers | ||||
| COST CENTERS | |||||
| .PAC | Packaging A | CHF | INV | ||
| .RM | Raw materials A | CHF | INV | ||
| .AM | Auxiliairy materials A | CHF | INV | ||
| INV | Total inventories | ||||
| ,MAN1 | Maintenance 1 | CHF | MAN | ||
| ,MAN2 | Maintenance 2 | CHF | MAN | ||
| ,MAN3 | Maintenance 3 | CHF | MAN | ||
| MAN | Total maintenance expenses | ||||
| ;AD1 | Advertising type 1 | CHF | ADV | ||
| ;AD2 | Advertising type 2 | CHF | ADV | ||
| ADV | Total advertising expenses | ||||
| VAT Code | Description | %VAT |
|---|---|---|
| Explanations | ||
| V = Sales (200) | ||
| VS = Discount sales and services (235) | ||
| B = Acquisition tax (38x) | ||
| M = Expenses for material and services (400) | ||
| I = Investments and other operating expenses (405) | ||
| K = Corrections (410, 415, 420) | ||
| Z = Not considered (910) | ||
| VAT codes information (do not modify) | ||
| id=vatcodes-che-2025.20250312 | ||
| Last update: 12.03.2025 | ||
| VAT Due | ||
| V0 | Exempt services (220) | |
| V0-E | Export services abroad (221) | |
| V0-T | Transfers in the reporting procedure (225) | |
| V0-N | Non-taxable services (230) | |
| Decrease of income from services, see discounts | ||
| V0-D | Various (280) | |
| V77 | Sales and services 7.7% | 7.70 |
| V81 | Sales and services 8.1% | 8.10 |
| V77-B | Sales and services 7.7% (chosen) | 7.70 |
| V81-B | Sales and services 8.1% (chosen) | 8.10 |
| V25-N | Sales and services 2.5% | 2.50 |
| V26 | Sales and services 2.6% | 2.60 |
| V37 | Sales and services 3.7% | 3.70 |
| V38 | Sales and services 3.8% | 3.80 |
| VS77 | Discount Sales and services 7.7% | 7.70 |
| VS81 | Discount Sales and services 8.1% | 8.10 |
| VS25-N | Discount Sales and services 2.5% | 2.50 |
| VS26 | Discount Sales and services 2.6% | 2.60 |
| VS37 | Discount Sales and services 3.7% | 3.70 |
| VS38 | Discount Sales and services 3.8% | 3.80 |
| Taxable turnover (299) | ||
| F1 | 1. Flat tax rate | |
| F2 | 2. Flat tax rate | |
| F3 | 3. Flat tax rate | |
| F4 | 4. Flat tax rate | |
| F5 | 5. Flat tax rate | |
| F6 | 6. Flat tax rate | |
| F7 | 7. Flat tax rate | |
| F8 | 8. Flat tax rate | |
| F9 | 9. Flat tax rate | |
| FS1 | Discount Sales and services 1. Flat tax rate | |
| FS2 | Discount Sales and services 2. Flat tax rate | |
| FS3 | Discount Sales and services 3. Flat tax rate | |
| FS4 | Discount Sales and services 4. Flat tax rate | |
| FS5 | Discount Sales and services 5. Flat tax rate | |
| FS6 | Discount Sales and services 6. Flat tax rate | |
| FS7 | Discount Sales and services 7. Flat tax rate | |
| FS8 | Discount Sales and services 8. Flat tax rate | |
| FS9 | Discount Sales and services 9. Flat tax rate | |
| Total Flat tax rate (322-335) | ||
| B77 | Acquisition tax 7.7% (With VAT/Sales tax) | 7.70 |
| B77-1 | Acquisition tax 7.7% (Without VAT/Sales tax) | 7.70 |
| B77-2 | Acquisition tax 7.7% (VAT/Sales tax amount) | 7.70 |
| B81 | Acquisition tax 8.1% (With VAT/Sales tax) | 8.10 |
| B81-1 | Acquisition tax 8.1% (Without VAT/Sales tax) | 8.10 |
| B81-2 | Acquisition tax 8.1% (VAT/Sales tax amount) | 8.10 |
| Total Tax on purchases (382-383) | ||
| Total VAT Due (399) | ||
| Recoverable VAT | ||
| M0 | Exempt material- and service expenses | |
| I0 | Exempt investment and operating expenses | |
| M77 | Purchase of material and services 7.7% (With VAT/Sales tax) | 7.70 |
| M77-1 | Purchase of material and services 7.7% (Without VAT/Sales tax) | 7.70 |
| M77-2 | Purchase of material and services 7.7% (VAT/Sales tax amount) | 7.70 |
| M81 | Purchase of material and services 8.1% (With VAT/Sales tax) | 8.10 |
| M81-1 | Purchase of material and services 8.1% (Without VAT/Sales tax) | 8.10 |
| M81-2 | Purchase of material and services 8.1% (VAT/Sales tax amount) | 8.10 |
| M25 | Purchase of material and services 2.5% | 2.50 |
| M26 | Purchase of material and services 2.6% | 2.60 |
| M37 | Purchase of material and services 3.7% | 3.70 |
| M38 | Purchase of material and services 3.8% | 3.80 |
| Investment and operating expenses | ||
| I77 | Investment and operating expenses 7.7% | 7.70 |
| I77-1 | Investment and operating expenses 7.7% (Without VAT/Sales tax) | 7.70 |
| I77-2 | Investment and operating expenses 7.7% (VAT/Sales tax amount) | 7.70 |
| I81 | Investment and operating expenses 8.1% | 8.10 |
| I81-1 | Investment and operating expenses 8.1% (Without VAT/Sales tax) | 8.10 |
| I81-2 | Investment and operating expenses 8.1% (VAT/Sales tax amount) | 8.10 |
| I25 | Investment and operating expenses 2.5% | 2.50 |
| I26 | Investment and operating expenses 2.6% | 2.60 |
| I37 | Investment and operating expenses 3.7% | 3.70 |
| I38 | Investment and operating expenses 3.8% | 3.80 |
| Corrections and adjustments | ||
| K77-A | Subsequent adjustment of prior tax 7.7% (410) | 7.70 |
| K81-A | Subsequent adjustment of prior tax 8.1 % (410) | 8.10 |
| K77-B | Corrections of prior tax 7.7% (415) | 7.70 |
| K81-B | Corrections of prior tax 8.1% (415) | 8.10 |
| K77-C | Reductions of the deduction of prior tax 7.7% (420) | 7.70 |
| K81-C | Reductions of the deduction of prior tax 8.1% (420) | 8.10 |
| F1050 | Tax computation according to form Nr. 1050 | |
| F1055 | Tax computation according to form Nr. 1055 | |
| Total Recoverable VAT (479) | ||
| Total VAT payable (500) or VAT credit (510) | ||
| Other financial flows | ||
| Z0-A | Subsidies, tourist taxes collected by the tourism offices, contributions to the institutions responsible for the elimination of waste and for the supply of water (let. a - c) | |
| Z0 | Gifts, dividends, compensation for damages etc. | |
| Not considered | ||
| Final total for control | ||
| Ref.Currency | Currency | Text |
|---|---|---|
| CHF | EUR | Euro |
| CHF | USD | U.S. Dollar |
Company | Double-entry multi-currency accounting | VAT
In this article
Company | Double-entry multi-currency accounting | VAT
Company | Double-entry multi-currency accounting | VAT
Template with an SME chart of accounts that includes management of foreign currency accounts and VAT with the new rates from 2024. Exchange rate calculations and exchange differences are handled automatically. Reports can also be generated in a second currency. VAT reports are automated, and data can be submitted electronically using the XML file (Advanced plan only). Automated checks and validations are available to minimize the risk of errors. Work efficiently with automated importing and rule-based processing. Open the template from our WebApp or the program, and save the file to your computer.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebAppTemplate documentation
Template featuring a chart of accounts structure with all the settings and columns for managing accounts in the base currency and any foreign currency, including virtual currencies. Further insights on the various aspects of multi-currency management are available on our pages dedicated to Multi-currency.
For VAT management with the new rates, detailed information is available on the web page VAT Management.
Create your file
- Open the template with the Banana Accounting Plus WebApp.
- Using the File > File Properties command, set the period, your company name, and the base currency (you can do budgeting and accounting in any currency).
- Using the File > Save As command, save the file. It is useful to include the company name and year in the file name. For example, "Rossi-SA-20xx.ac2".
- In the Exchange Rates table, set the foreign currencies always with reference to the base currency and exchange rates. Opening rates are set only the first time Banana Accounting is used. At the turn of the new year, they will be automatically carried forward according to the closing rates entered on 31.12.
WARNING: If you close the browser without saving, you will lose the entered data. Always save the file on your computer.
To reopen the saved file click on File > Open.
All the settings and features are available for:
- Creating and printing invoices with the Swiss QR code
- Importing data from bank statements
- Setting up Rules to store and automate the completion of imported bank transactions.
- Managing VAT according to the new VAT rates
- Managing cost centers, customizable according to your needs to get detailed insights on specific accounts.
- Creating budgets and financial forecasts
- Printing all the reports you need: Balance sheets, Journal, Account cards, VAT reports, Open invoices, and much more.
Some features require a subscription to the Advanced plan of Banana Accounting Plus, such as generating previews or the XML file of the VAT Statement, using the new Rules, Filter, and Temporary Row Sorting functions. See all the features of the Advanced plan.
You can record all possible cases of foreign currency transactions, including transfers and operations that do not involve the base currency.
In our Documentation you will find all insights and topics related to multi-currency accounting, including:
Template preview
Company XX
Accounting 2024
Basic Currency: CHF
Double-entry with foreign currencies and VAT/Sales tax
| Group | Account | Description | Currency | Sum In | Gr1 |
|---|---|---|---|---|---|
| BALANCE SHEET | |||||
| ASSETS | |||||
| 1000 | Cash on hand | CHF | 10 | ||
| 1010 | Post office current account | CHF | 10 | ||
| 1020 | Bank account | CHF | 10 | ||
| 1030 | Bank account EUR | CHF | 10 | ||
| 1040 | Bank account USD | CHF | 10 | ||
| 1090 | Internal transfers | EUR | 10 | ||
| 1091 | Transfer account for salaries | USD | 10 | ||
| 1099 | Amounts to be clarified | CHF | 10 | ||
| 1100 | Due from Clients or Debtors | CHF | 10 | ||
| 1176 | Withholding tax | CHF | 10 | ||
| 1191 | Securities | CHF | 10 | ||
| 1300 | Prepaid expenses | CHF | 10 | ||
| 10 | Current assets | 1 | |||
| 1500 | Machinery | CHF | 14 | ||
| 1510 | Office equipment | CHF | 14 | ||
| 1512 | Store fixtures | CHF | 14 | ||
| 1520 | Office machinery | CHF | 14 | ||
| 1521 | IT Hardware | CHF | 14 | ||
| 1526 | Software | CHF | 14 | ||
| 1530 | Vehicles | CHF | 14 | ||
| 14 | Fixed Assets | 1 | |||
| 1 | TOTAL ASSETS | 00 | 1 | ||
| LIABILITIES | |||||
| 2000 | Suppliers | CHF | 20 | ||
| 2100 | Due to banks short-term | CHF | 20 | ||
| 2200 | VAT Due | CHF | 20 | ||
| 2201 | VAT according to VAT report | CHF | 20 | ||
| 2300 | Accrued expenses | CHF | 20 | ||
| 20 | Short-term third party capital | 2 | |||
| 2400 | Due to banks | CHF | 24 | ||
| 2420 | Financial leasing commitments | CHF | 24 | ||
| 2600 | Provisions | CHF | 24 | ||
| 24 | Long-term third party capital | 2 | |||
| 2800 | Share capital | CHF | 28 | ||
| 2850 | Private account | CHF | 28 | ||
| 2970 | Profit (Loss) carried forward | CHF | 28 | ||
| 297 | Profit/Loss for the period | CHF | 28 | 1 | |
| 28 | Equity | 2 | |||
| 2 | TOTAL LIABILITIES | 00 | 1 | ||
| PROFIT & LOSS STATEMENT | |||||
| REVENUE | |||||
| 3000 | Earnings from own products | CHF | 3 | ||
| 3400 | Earnings from services rendered | CHF | 3 | ||
| 3490 | Discounts | CHF | 3 | ||
| 3600 | Other revenues and services | CHF | 3 | ||
| 3710 | Own consumption | CHF | 3 | ||
| 3809 | VAT flat tax rate | CHF | 3 | ||
| 3 | TOTAL REVENUE | 02 | 1 | ||
| EXPENSES | |||||
| 4000 | Purchases | CHF | 4 | ||
| 4 | Total Purchases | 4-6 | |||
| 5600 | Salaries - Administration | CHF | 5 | ||
| 5700 | Contribution to old age insurance and unemployment | CHF | 5 | ||
| 5710 | Family allowances | CHF | 5 | ||
| 5720 | Contribution to pension funds | CHF | 5 | ||
| 5730 | Contribution to accident insurance | CHF | 5 | ||
| 5740 | Contribution to voluntary daily benefits insurance | CHF | 5 | ||
| 5790 | Source tax | CHF | 5 | ||
| 5820 | Travel and entertainment expenses effective | CHF | 5 | ||
| 5830 | Travel and entertainment expense allowance | CHF | 5 | ||
| 5880 | Other personal expenses | CHF | 5 | ||
| 5900 | Temporary staff | CHF | 5 | ||
| 5 | Total expenses for personnel | 4-6 | 1 | ||
| 6000 | Rental | CHF | 6 | ||
| 6030 | Incidental rent costs | CHF | 6 | ||
| 6100 | Maintenance, repairs and replacement of tangible assets | CHF | 6 | ||
| 6200 | Repairs | CHF | 6 | ||
| 6210 | Fuel | CHF | 6 | ||
| 6220 | Car insurance | CHF | 6 | ||
| 6300 | Insurance for damage of items | CHF | 6 | ||
| 6402 | Electricity | CHF | 6 | ||
| 6410 | Heating expenses | CHF | 6 | ||
| 6430 | Water | CHF | 6 | ||
| 6460 | Garbage | CHF | 6 | ||
| 6500 | Office supplies | CHF | 6 | ||
| 6503 | Technical magazines, newspapers, periodicals | CHF | 6 | ||
| 6510 | Phone | CHF | 6 | ||
| 6511 | Hosting at third party | CHF | 6 | ||
| 6513 | Postage | CHF | 6 | ||
| 6520 | Taxes and fees | CHF | 6 | ||
| 6521 | Donations | CHF | 6 | ||
| 6530 | Book-keeping fees | CHF | 6 | ||
| 6570 | IT costs including leasing | CHF | 6 | ||
| 6574 | Small investments | CHF | 6 | ||
| 6580 | Licenses and updates | CHF | 6 | ||
| 6583 | Consumables | CHF | 6 | ||
| 6641 | Customer support | CHF | 6 | ||
| 6642 | Gifts to customers | CHF | 6 | ||
| 6800 | Depreciation and value adjustments of fixed assets | CHF | 6 | ||
| 6900 | Costs for bank interests | CHF | 6 | ||
| 6949 | Exchange rate loss | CHF | 6 | ||
| 6950 | Financial revenue | CHF | 6 | ||
| 6999 | Exchange rate profit | CHF | 6 | ||
| 8900 | Cantonal and communal taxes | CHF | 6 | ||
| 6 | Total general expenses | 4-6 | 1 | ||
| 4-6 | TOTAL EXPENSES | 02 | |||
| 02 | Profit/Loss for Profit & Loss Statement | 297 | 1 | ||
| 00 | Difference should be = 0 (blank cell) | ||||
| COST CENTERS | |||||
| ,MAN1 | Maintenance 1 | CHF | MAN | ||
| ,MAN2 | Maintenance 2 | CHF | MAN | ||
| ,MAN3 | Maintenance 3 | CHF | MAN | ||
| MAN | Total maintenance | ||||
| ;PB1 | Publicity 1 | CHF | PU | ||
| ;PB2 | Publicity 2 | CHF | PU | ||
| PU | Total publicity |
| VAT Code | Description | %VAT |
|---|---|---|
| Explanations | ||
| V = Sales (200) | ||
| VS = Discount sales and services (235) | ||
| B = Acquisition tax (38x) | ||
| M = Expenses for material and services (400) | ||
| I = Investments and other operating expenses (405) | ||
| K = Corrections (410, 415, 420) | ||
| Z = Not considered (910) | ||
| VAT codes information (do not modify) | ||
| id=vatcodes-che-2024.20230614 | ||
| Last update: 14.06.2023 | ||
| VAT Due | ||
| V0 | Exempt services (220) | |
| V0-E | Export services abroad (221) | |
| V0-T | Transfers in the reporting procedure (225) | |
| V0-N | Non-taxable services (230) | |
| Decrease of income from services, see discounts | ||
| V0-D | Various (280) | |
| V77 | Sales and services 7.7% | 7.70 |
| V81 | Sales and services 8.1% | 8.10 |
| V77-B | Sales and services 7.7% (chosen) | 7.70 |
| V81-B | Sales and services 8.1% (chosen) | 8.10 |
| V25-N | Sales and services 2.5% | 2.50 |
| V26 | Sales and services 2.6% | 2.60 |
| V37 | Sales and services 3.7% | 3.70 |
| V38 | Sales and services 3.8% | 3.80 |
| VS77 | Discount Sales and services 7.7% | 7.70 |
| VS81 | Discount Sales and services 8.1% | 8.10 |
| VS25-N | Discount Sales and services 2.5% | 2.50 |
| VS26 | Discount Sales and services 2.6% | 2.60 |
| VS37 | Discount Sales and services 3.7% | 3.70 |
| VS38 | Discount Sales and services 3.8% | 3.80 |
| Taxable turnover (299) | ||
| F1 | 1. Flat tax rate 2024 | |
| F2 | 2. Flat tax rate 2024 | |
| FS1 | Discount Sales and services 1. Flat tax rate 2024 | |
| FS2 | Discount Sales and services 2. Flat tax rate 2024 | |
| F3 | 1. Flat tax rate 2018 | |
| F4 | 2. Flat tax rate 2018 | |
| FS3 | Discount Sales and services 1. Flat tax rate 2018 | |
| FS4 | Discount Sales and services 2. Flat tax rate 2018 | |
| Total Flat tax rate (322-333) | ||
| B77 | Acquisition tax 7.7% (With VAT/Sales tax) | 7.70 |
| B77-1 | Acquisition tax 7.7% (Without VAT/Sales tax) | 7.70 |
| B77-2 | Acquisition tax 7.7% (VAT/Sales tax amount) | 7.70 |
| B81 | Acquisition tax 8.1% (With VAT/Sales tax) | 8.10 |
| B81-1 | Acquisition tax 8.1% (Without VAT/Sales tax) | 8.10 |
| B81-2 | Acquisition tax 8.1% (VAT/Sales tax amount) | 8.10 |
| Total Tax on purchases (382-383) | ||
| Total VAT Due (399) | ||
| Recoverable VAT | ||
| M0 | Exempt material- and service expenses | |
| I0 | Exempt investment and operating expenses | |
| M77 | Purchase of material and services 7.7% (With VAT/Sales tax) | 7.70 |
| M77-1 | Purchase of material and services 7.7% (Without VAT/Sales tax) | 7.70 |
| M77-2 | Purchase of material and services 7.7% (VAT/Sales tax amount) | 7.70 |
| M81 | Purchase of material and services 8.1% (With VAT/Sales tax) | 8.10 |
| M81-1 | Purchase of material and services 8.1% (Without VAT/Sales tax) | 8.10 |
| M81-2 | Purchase of material and services 8.1% (VAT/Sales tax amount) | 8.10 |
| M25 | Purchase of material and services 2.5% | 2.50 |
| M26 | Purchase of material and services 2.6% | 2.60 |
| M37 | Purchase of material and services 3.7% | 3.70 |
| M38 | Purchase of material and services 3.8% | 3.80 |
| Investment and operating expenses | ||
| I77 | Investment and operating expenses 7.7% | 7.70 |
| I77-1 | Investment and operating expenses 7.7% (Without VAT/Sales tax) | 7.70 |
| I77-2 | Investment and operating expenses 7.7% (VAT/Sales tax amount) | 7.70 |
| I81 | Investment and operating expenses 8.1% | 8.10 |
| I81-1 | Investment and operating expenses 8.1% (Without VAT/Sales tax) | 8.10 |
| I81-2 | Investment and operating expenses 8.1% (VAT/Sales tax amount) | 8.10 |
| I25 | Investment and operating expenses 2.5% | 2.50 |
| I26 | Investment and operating expenses 2.6% | 2.60 |
| I37 | Investment and operating expenses 3.7% | 3.70 |
| I38 | Investment and operating expenses 3.8% | 3.80 |
| Corrections and adjustments | ||
| K77-A | Subsequent adjustment of prior tax 7.7% (410) | 7.70 |
| K81-A | Subsequent adjustment of prior tax 8.1 % (410) | 8.10 |
| K77-B | Corrections of prior tax 7.7% (415) | 7.70 |
| K81-B | Corrections of prior tax 8.1% (415) | 8.10 |
| K77-C | Reductions of the deduction of prior tax 7.7% (420) | 7.70 |
| K81-C | Reductions of the deduction of prior tax 8.1% (420) | 8.10 |
| F1050 | Tax computation according to form Nr. 1050 | |
| F1055 | Tax computation according to form Nr. 1055 | |
| Total Recoverable VAT (479) | ||
| Total VAT payable (500) or VAT credit (510) | ||
| Other financial flows | ||
| Z0-A | Subsidies, tourist taxes collected by the tourism offices, contributions to the institutions responsible for the elimination of waste and for the supply of water (let. a - c) | |
| Z0 | Gifts, dividends, compensation for damages etc. | |
| Not considered | ||
| Final total for control | ||
| Ref.Currency | Currency | Text |
|---|---|---|
| CHF | EUR | Euro |
| CHF | USD | US Dollar |