全球: 商业会计
无增值税的商业会计模板
商店会计
在此文中
商店会计
商店会计
使用现金账簿方法来完美管理商店或店铺的通用会计模板。
模板预览
XX店铺
本位币: USD
现金日记账
| 总组 | 账号 | 摘要 | 总和 |
|---|---|---|---|
| 现金 | 现金 | ||
| 总组 | 科目 | 摘要 | 总和 |
|---|---|---|---|
| 经营业绩 | |||
| 收入 | |||
| 销售收入 | 销售收入 | 4 | |
| 从银行账户提款 | 从银行账户提款 | 4 | |
| 服务收入 | 服务收入 | 4 | |
| 其他收入 | 其他收入 | 4 | |
| 4 | 总收入 | 00 | |
| 费用 | |||
| 转账到银行账户 | 转账到银行账户 | 3 | |
| 购买邮票 | 购买邮票 | 3 | |
| 邮政费用 | 信件和包裹 | 3 | |
| 快递费 | 邮递物品 | 3 | |
| 办公用品 | 文具,电器,清洁 | 3 | |
| 租金及水电费 | 租金,电费,水费 | 3 | |
| 电话费 | 电话和传真费 | 3 | |
| 房屋保养 | 房屋保养 | 3 | |
| 橱窗装饰 | 橱窗装饰 | 3 | |
| 宣传费 | 宣传,传单 | 3 | |
| 中介费 | 中介费 | 3 | |
| 支付货款 | 支付货款 | 3 | |
| 薪资及个人贷款 | 薪资及个人贷款 | 3 | |
| 其他许可证费用 | 其他许可证费用 | 3 | |
| 3 | 总费用 | 00 | |
| 00 | 业绩 | ||
| 成本和利润中心 | |||
| 部门 | |||
| .店铺及人事管理 | 店铺及人事管理 | T1 | |
| .货物管理 | 货物管理 | T1 | |
| .投资 | 投资 | T1 | |
| T1 | 总部门 | ||
Simple Accounting for a Shop | Universal
在此文中
Simple Accounting for a Shop | Universal
Simple Accounting for a Shop | Universal
General template perfect to manage the accounting of a shop or a store, with the simple accounting method. This is a universal template, easily adaptable in any country.
直接在网页中打开Banana财务会计+
无需任何安装,可以直接在您的浏览器上运行 Banana财务会计+。客制化您的模板,输入发生业务并将文件保存在您的电脑上。
在浏览器中打开模板 Open tutorial in WebApp模板预览
Shop XX
| Group | Account | Description | Sum In |
|---|---|---|---|
| Cash | Cash | ||
| Group | Category | Description | Sum In |
|---|---|---|---|
| OPERATING RESULT | |||
| INCOME | |||
| Sales | Sales | Total Income | |
| Withdrawal | Withdrawal from current account | Total Income | |
| Services | Services | Total Income | |
| Other | Other | Total Income | |
| Total Income | TOTAL INCOME | Result | |
| EXPENSES | |||
| Good Purchase | Payments for goods | Total Expenses | |
| Transfers to post | Tranfers to post office account | Total Expenses | |
| Salaries | Salaries and personal loans | Total Expenses | |
| Stamps | Purchase stamps | Total Expenses | |
| Mailing supplies | Mailing supplies | Total Expenses | |
| Stationery | Stationery, appliances | Total Expenses | |
| Publicity | Publicity, flyers | Total Expenses | |
| Window dressing | Window dressing | Total Expenses | |
| Cleaning | Cleaning | Total Expenses | |
| Rent | Rent | Total Expenses | |
| Energy | Electricity, water, gas | Total Expenses | |
| Telephone | Telephone and fax | Total Expenses | |
| Internet | Internet | Total Expenses | |
| Real estate | Real estate upkeep | Total Expenses | |
| Agency fees | Agency fees | Total Expenses | |
| Taxes | Taxes | Total Expenses | |
| Insurance | Insurance | Total Expenses | |
| Total Expenses | TOTAL EXPENSES | Result | |
| Result | RESULT | ||
| COST AND PROFIT CENTERS | |||
| DIVISION | |||
| .S | Shop and personnel management | T1 | |
| .G | Goods management | T1 | |
| .I | Investments | T1 | |
| T1 | TOTAL DIVISION | ||
公司的收益&费用记账模板
在此文中
公司的收益&费用记账模板
公司的收益&费用记账模板
轻松地、免费地开始您公司的收益&费用核算,并立即获得损益表和资产负债表。收入和支出核算系统是专业会计知识有限用户的理想选择。可以根据您的具体需要对这个现成的模板进行编辑,用来管理您的公司、独资企业、合伙企业或中小型企业的会计。Banana财务会+ 是一个专业的软件,由于它类似于Excel,所以使用起来非常直观和快速。如果在做账中出现了错误,也可以随时纠正,直到获得完美的会计报表。
直接在网页中打开Banana财务会计+
无需任何安装,可以直接在您的浏览器上运行 Banana财务会计+。客制化您的模板,输入发生业务并将文件保存在您的电脑上。
在浏览器中打开模板 Open tutorial in WebApp模板预览
XX 公司
本位币: USD
收益 & 费用核算
| 总组 | 账号 | 摘要 | 总和 |
|---|---|---|---|
| 资产负债表 | |||
| 资产 | |||
| 银行账户 | |||
| 商业账户 | 商业账户 | 银行 | |
| 商业存储账户 | 商业存储账户 | 银行 | |
| 工资账户 | 工资账户 | 银行 | |
| 现金 | 小额现金 - 自付費用 | 银行 | |
| 易货贸易 | 易货贸易账户 | 银行 | |
| 银行 | 银行账户总计 | 资产 | |
| 应收账款 | |||
| 客户 | 应收账款 (客户登记) | 应收 | |
| 应收 | 应收账款总计 | 资产 | |
| 流动资产 | |||
| 库存 | 库存 | 流动资产 | |
| 未存入的资金 | 未存入的资金 | 流动资产 | |
| 流动资产 | 流动资产总计 | 资产 | |
| 固定资产 | |||
| 设备 | 设备 | 固定 | |
| 家具 | 家具和固定装置 | 固定 | |
| 车辆 | 车辆 | 固定 | |
| 累计折旧 | 累计折旧 | 固定 | |
| 固定 | 固定资产总计 | 资产 | |
| 其它资产 | |||
| 启动 | 启动成本 (会计人员使用) | 其它 | |
| 摊销 | 累计摊销 | 其它 | |
| 应收票据1 | 应收票据1 (高级职员、所有者、关联方) | 其它 | |
| 应收票据2 | 应收票据2 | 其它 | |
| 其它 | 其它资产总计 | 资产 | |
| 资产 | 总资产 | 净资产 | |
| 负债 | |||
| 应付账款 | |||
| 供应商 | 供应商登记 | 应付 | |
| 应付 | 应付账款总计 | 负债 | |
| 用于采购的信用卡 | |||
| 美国运通 | 美国运通 - 信用卡贷款 | 信用卡 | |
| Visa | Visa - 信用卡贷款 | 信用卡 | |
| 信用卡 | 信用卡总计 | 负债 | |
| 流动负债 | |||
| 应计 | 应计费用 | 流动负债 | |
| 应付薪资税 | 应付薪资税 | 流动负债 | |
| 应付营业税 | 应付营业税 | 流动负债 | |
| 押金 | 客户押金 | 流动负债 | |
| 长期部分 | 长期负债的流动部分 | 流动负债 | |
| 流动负债 | 流动负债总计 | 负债 | |
| 长期负债 | |||
| 银行贷款 | 银行贷款 | 长期负债 | |
| 应付票据1 | 应付票据1 | 长期负债 | |
| 应付票据2 | 应付票据2 | 长期负债 | |
| 长期负债 | 长期负债总计 | 负债 | |
| 负债 | 总负债 | 净资产 | |
| 股权 | |||
| 资本 | 股本/资本合伙人 | 股权 | |
| 附加资本 | 额外出资/额外支付资本 | 股权 | |
| 留存收益 | 留存收益 | 股权 | |
| 期初权益 | 期初余额权益 | 股权 | |
| 股东1 | 分配股东 1 / 股息 / 提款 | 股权 | |
| 结转 | 结转盈亏 | 股权 | |
| 股权 | 股权总计 | 净资产 | |
| 净资产 | 净资产 | ||
| 客户登记 | |||
| 客户-Redford | Redford 公司 | 客户总计 | |
| 客户-Smith | John Smith | 客户总计 | |
| 客户-Black | Simon Black | 客户总计 | |
| 客户总计 | 客户总计 | 客户 | |
| 供应商登记 | |||
| 供应商-Johnson | Johnson 公司 | 供应商总计 | |
| 供应商-Marble | Marble | 供应商总计 | |
| 供应商-Taylor | Mary Taylor | 供应商总计 | |
| 供应商总计 | 供应商总计 | 供应商 | |
| 总组 | 科目 | 摘要 | 总和 |
|---|---|---|---|
| 损益表 | |||
| 收入 | |||
| 服务 | 服务收入 | 收入 | |
| 售出的产品 | 零件/产品销售收入 | 收入 | |
| 销售冲销 | 销售冲销 | 收入 | |
| 收入 | 总收入 | 毛利润 | |
| 销货成本 | |||
| 材料费 | 材料、直接产品/服务成本 | 销货成本 | |
| 人工费 | 人工成本 | 销货成本 | |
| 外部服务 | 外部服务/分包商 | 销货成本 | |
| 供应品 | 耗材成本 | 销货成本 | |
| 小型工具 | 小型工具 | 销货成本 | |
| 销货成本 | 销货成本总计 | 毛利润 | |
| 损益表 | |||
| 毛利润 | 毛利润 | 息税前利润 | |
| 费用 | |||
| 广告 | 广告、促销、营销费用 | 费用 | |
| 汽车 | 汽车费用 | 费用 | |
| 银行收费 | 银行服务费 | 费用 | |
| 清洁费 | 清洁费 | 费用 | |
| 捐款 | 捐款 | 费用 | |
| 折旧 | 折旧费用 | 费用 | |
| 折扣 | 采取的折扣 | 费用 | |
| 订阅费 | 捐款和订阅费 | 费用 | |
| 保险费 | 汽车保险、人寿、医疗 | 费用 | |
| 利息支出 | 利息支出 | 费用 | |
| 许可证 | 商业执照和许可证 | 费用 | |
| 维修费 | 维护和修理 | 费用 | |
| 餐费 | 膳食和娱乐 | 费用 | |
| 商户费用 | 商家信用卡费用 | 费用 | |
| 办公室 | 办公费用(电脑、邮资、快递、用品)。 | 费用 | |
| 薪资税 | 薪资税 | 费用 | |
| 专业费用 | 专业费用 | 费用 | |
| 租金 | 租金支付 | 费用 | |
| 工资 | 工资 | 费用 | |
| 电话费 | 电话、传真 | 费用 | |
| 旅行 | 旅行 | 费用 | |
| 公用事业 | 公用事业 | 费用 | |
| 费用 | 总费用 | 息税前利润 | |
| 息税前利润 | 息税前利润 | 结果 | |
| 其它收入 | |||
| 利息收入 | 利息收入 | 其它收入 | |
| 其它收入 | 其它收入总计 | 结果 | |
| 其它费用 | |||
| 会计师咨询 | 会计师咨询 | 其它费用 | |
| 其它费用 | 其它费用总计 | 结果 | |
| 结果 | 净利 (盈利(-) 亏损(+) ) | ||
| 成本中心 | |||
| 产品 | |||
| .产品 A | 产品 A | 产品 | |
| .产品 B | 产品 B | 产品 | |
| .产品 C | 产品 C | 产品 | |
| 产品 | 产品总计 | ||
| 项目 | |||
| ;项目 A | 项目 A | 项目 | |
| ;项目 B | 项目 B | 项目 | |
| 项目 | 项目总计 | ||
| 部门 | |||
| 分公司 | |||
| :分公司 A | 分公司 A | 分公司 | |
| :分公司 B | 分公司 B | 分公司 | |
| 分公司 | 分公司总计 | ||
房地产管理的收益&费用核算
在此文中
房地产管理的收益&费用核算
房地产管理的收益&费用核算
管理资产或公寓(房地产)会计的理想模板,只需输入收入和费用即可。租户列表由成本中心管理。
直接在网页中打开Banana财务会计+
无需任何安装,可以直接在您的浏览器上运行 Banana财务会计+。客制化您的模板,输入发生业务并将文件保存在您的电脑上。
在浏览器中打开模板 Open tutorial in WebApp模板预览
Property XXX
Accounting 2022
| 总组 | 账号 | 摘要 | 总和 |
|---|---|---|---|
| 资产 | |||
| 现金 | 现金 | 总资产 | |
| 邮政账户 | 邮政储蓄账户 | 总资产 | |
| 银行 | 银行 | 总资产 | |
| 应收租赁款 | 应收租赁款 | 总资产 | |
| 机器 | 机器和设备 | 总资产 | |
| 办公室设备 | 办公室设备 | 总资产 | |
| 电脑 | 电脑 | 总资产 | |
| 软件 | 软件 | 总资产 | |
| 建筑物 | 建筑物 | 总资产 | |
| 土地 | 土地 | 总资产 | |
| 总资产 | 总资产 | 净资产 | |
| 负债 | |||
| 供应商 | 供应商 | 总负债 | |
| 抵押贷款 | 抵押贷款 | 总负债 | |
| 租户提供的押金 | 租户提供的押金 | 总负债 | |
| 总负债 | 总负债 | 净资产 | |
| 净资产 | 净资产 | ||
| 总组 | 科目 | 摘要 | 总和 |
|---|---|---|---|
| 经营结果 | |||
| 收入 | |||
| 租赁收入 | 租赁收入 | 总收入 | |
| 其它租赁收入 | 其它租赁相关收入 | 总收入 | |
| 其它收入 | 其它收入 | 总收入 | |
| 总收入 | 总收入 | 结果 | |
| 费用 | |||
| 广告 | 租赁广告费 | 总费用 | |
| 房地产中介费 | 房地产中介费用/佣金 | 总费用 | |
| 法律费用 | 法律费用 | 总费用 | |
| 保险费 | 保险费 | 总费用 | |
| 土地税 | 土地税 | 总费用 | |
| 执照和许可费 | 执照和许可费 | 总费用 | |
| 折旧费 | 折旧费 | 总费用 | |
| 维修费 | 维修费 | 总费用 | |
| 电费 | 电费 | 总费用 | |
| 水费 | 水费 | 总费用 | |
| 供暖费用 | 供暖费用 | 总费用 | |
| 清洁费 | 清洁费 | 总费用 | |
| 园艺/草坪修剪费 | 园艺/草坪修剪费 | 总费用 | |
| 害虫防治费 | 害虫防治费 | 总费用 | |
| 文具,电话和邮费 | 文具,电话和邮费 | 总费用 | |
| 材料费 | 材料费 | 总费用 | |
| 抵押贷款利息 | 抵押贷款利息 | 总费用 | |
| 杂项费用 | 杂项费用 | 总费用 | |
| 总费用 | 总费用 | 结果 | |
| 结果 | 总经营结果 | ||
| 利润和成本中心 | |||
| 租户 | |||
| ;T01 | 租户 1 | T | |
| ;T02 | 租户 2 | T | |
| ;T03 | 租户 3 | T | |
| ;T04 | 租户 4 | T | |
| T | 总租户 |
Comptabilité pour sociétés anonymes
在此文中
Comptabilité pour sociétés anonymes
Comptabilité pour sociétés anonymes
Modèle idéal pour la gestion de la comptabilité des sociétés anonymes. Le plan comptable est structuré selon le schéma PME et présente les registres clients/fournisseurs. Il y a des comptes en devises étrangères et des centres de coûts.
模板预览
DeviseBase: EUR
Comptabilité en partie double avec multidevise
| Groupe | Compte | Libellé | Devise | Add. dans |
|---|---|---|---|---|
| BILAN | ||||
| ACTIFS | ||||
| 1000 | Caisse | EUR | 100 | |
| 1020 | Banque | EUR | 100 | |
| 1024 | Banque CHF | CHF | 100 | |
| 1025 | Banque USD | USD | 100 | |
| 100 | Liquidités | 10 | ||
| 1060 | Titres | EUR | 106 | |
| 106 | Avoirs à court terme cotés en bourse | 10 | ||
| 1090 | Compte d'attente en monnaie | EUR | 109 | |
| 1091 | Compte d'attente salaires | EUR | 109 | |
| 1099 | Compte de passage pour éclaircissements | EUR | 109 | |
| 109 | Comptes de transit et d’attente | 10 | ||
| 1100 | Créances provenant de livraisons et de prestations (Débiteurs) | EUR | 110 | |
| 1109 | Ducroire | EUR | 110 | |
| 100A | Clients | 110 | ||
| 110 | Créances résultant de livraisons et prestations | 10 | ||
| 1140 | Avances et prêts | EUR | 114 | |
| 1176 | Impôt anticipé | EUR | 114 | |
| 1180 | Créances envers les assurances sociales et institutions de prévoyance | EUR | 114 | |
| 1188 | Impôt à la source | EUR | 114 | |
| 1190 | Autres créances à court terme | EUR | 114 | |
| 1191 | Cautionnements en espèces | EUR | 114 | |
| 114 | Autres créances à court terme | 10 | ||
| 1200 | Marchandises commerciales | EUR | 120 | |
| 1210 | Matières premières | EUR | 120 | |
| 1220 | Matières auxiliaires | EUR | 120 | |
| 1230 | Matières consommables | EUR | 120 | |
| 1260 | Stocks de produits finis | EUR | 120 | |
| 1270 | Stocks de produits pas finis | EUR | 120 | |
| 1280 | Travaux en cours | EUR | 120 | |
| 120 | Stocks et prestations non facturées | 10 | ||
| 1300 | Charges payées d‘avance | EUR | 130 | |
| 1301 | Produits à recevoir | EUR | 130 | |
| 130 | Compte de régularisation de l’actif | 10 | ||
| 10 | Actifs circulants | 1 | ||
| 1400 | Titres à long terme | EUR | 140 | |
| 1440 | Prêts | EUR | 140 | |
| 1441 | Hypothèques | EUR | 140 | |
| 1460 | Prêts à actionnaire | EUR | 140 | |
| 140 | Immobilisations financières | 14 | ||
| 1480 | Participations | EUR | 148 | |
| 148 | Participations | 14 | ||
| 1500 | Machines et appareils | EUR | 150 | |
| 1510 | Mobilier et installations | EUR | 150 | |
| 1520 | Machines de bureau, informatique, systèmes de communication | EUR | 150 | |
| 1530 | Véhicules | EUR | 150 | |
| 1540 | Outillages et appareils | EUR | 150 | |
| 150 | Immobilisations corporelles meubles | 14 | ||
| 1600 | Immeubles d’exploitation | EUR | 160 | |
| 160 | Immobilisations corporelles immeubles | 14 | ||
| 1700 | Brevets, know-how, licences, droits, développement | EUR | 170 | |
| 1710 | Marques commerciales | EUR | 170 | |
| 1712 | Modèles | EUR | 170 | |
| 1770 | Goodwill | EUR | 170 | |
| 170 | Immobilisations incorporelles | 14 | ||
| 1850 | Capital actions, capital social, droits de participations ou capital de fondation non versés | EUR | 180 | |
| 180 | Capital non versé : capital social, capital de fondation | 14 | ||
| 14 | Actifs immobilisés | 1 | ||
| 1 | Total actifs | 00 | ||
| PASSIFS | ||||
| 2000 | Dettes résultant d’achats et de prestation de services (créanciers) | EUR | 200 | |
| 2030 | Acomptes de clients | EUR | 200 | |
| 200A | Créanciers | 200 | ||
| 200 | Dettes à court terme résultant d’achats et de prestations de services | 20 | ||
| 2100 | Dettes bancaires | EUR | 210 | |
| 2120 | Engagements de financement par leasing | EUR | 210 | |
| 2140 | Autres dettes à court terme rémunérées | EUR | 210 | |
| 210 | Dettes à court terme rémunérés | 20 | ||
| 2200 | TVA due | EUR | 220 | |
| 2201 | Décompte TVA | EUR | 220 | |
| 2206 | Impôt anticipé dû | EUR | 220 | |
| 2208 | Impôts directs | EUR | 220 | |
| 2210 | Autres dettes à court terme | EUR | 220 | |
| 2260 | Dettes envers actionnaire | EUR | 220 | |
| 2261 | Dividendes | EUR | 220 | |
| 2270 | Assurances sociales et institutions de prévoyance | EUR | 220 | |
| 2279 | Impôt à la source | EUR | 220 | |
| 220 | Autres dettes à court terme | 20 | ||
| 2300 | Charges à payer | EUR | 230 | |
| 2301 | Produits encaissés d’avance | EUR | 230 | |
| 2330 | Provisions à court terme | EUR | 230 | |
| 230 | Passifs de régularisation et provisions à court terme | 20 | ||
| 20 | Dettes à court terme | 2A | ||
| 2400 | Dettes bancaires | EUR | 240 | |
| 2420 | Engagements de financement par leasing | EUR | 240 | |
| 2430 | Emprunts obligataires | EUR | 240 | |
| 2450 | Emprunts | EUR | 240 | |
| 2451 | Hypothèques | EUR | 240 | |
| 240 | Dettes à long terme rémunérées | 24 | ||
| 2500 | Autres dettes à long terme | EUR | 250 | |
| 250 | Autres dettes à long terme | 24 | ||
| 2600 | Provisions | EUR | 260 | |
| 260 | Provisions à long termes et provisions légales | 24 | ||
| 24 | Dettes à long terme | 2A | ||
| 2A | Fonds étrangers | 2 | ||
| 2800 | Capital-actions, capital social, capital de fondation | EUR | 280 | |
| 280 | Capital social ou capital de fondation | 28 | ||
| 2900 | Réserves légales issues du capital | EUR | 290 | |
| 2940 | Réserves d‘évaluation | EUR | 290 | |
| 290 | Réserves légales issues du capital | 28 | ||
| 2950 | Réserves légales issues du bénéfice | EUR | 295 | |
| 295 | Réserves légales issues du bénéfice | 28 | ||
| 2960 | Réserves libres | EUR | 296 | |
| 296 | Réserves libres | 28 | ||
| 2970 | Bénéfice / perte reporté | EUR | 297 | |
| 29A | Bénéfice / perte de l’exercice | 297 | ||
| 297 | Bénéfice / perte du bilan | 28 | ||
| 2980 | Propres actions, parts sociales, droits de participations (poste négatif) | EUR | 298 | |
| 298 | Propres actions, parts sociales, droits de participations (poste négatif) | 28 | ||
| 28 | Fonds propres | 2 | ||
| 2 | Total passifs | 00 | ||
| COMPTE DE PERTES ET PROFITS | ||||
| 3000 | Ventes de produits fabriqués | EUR | 30 | |
| 3200 | Ventes de marchandises | EUR | 30 | |
| 3400 | Ventes de prestations | EUR | 30 | |
| 3600 | Autres ventes et prestations de services | EUR | 30 | |
| 3700 | Prestations propres | EUR | 30 | |
| 3710 | Consommations propres | EUR | 30 | |
| 3800 | Déductions sur ventes | EUR | 30 | |
| 3805 | Pertes sur clients, variation du ducroire | EUR | 30 | |
| 30 | Chiffre d'affaires net résultant des ventes et prestations de services | 3 | ||
| 3900 | Variation des stocks de produits semi-finis | EUR | 39 | |
| 3901 | Variation des stocks de produits finis | EUR | 39 | |
| 3940 | Variation de la valeur des prestations non facturées | EUR | 39 | |
| 39 | Variation des travaux en cours et des prestations non facturées | 3 | ||
| 3 | Produit net des ventes et des prestations de service | E1 | ||
| 4000 | Charges de matériel de l'atelier | EUR | 4 | |
| 4200 | Achats de marchandises destinées à la revente | EUR | 4 | |
| 4400 | Prestations / travaux de tiers | EUR | 4 | |
| 4500 | Charges d'énergie pour l'exploitation | EUR | 4 | |
| 4900 | Déductions sur les charges | EUR | 4 | |
| 4 | Charges de matériel, de marchandises et de prestations de tiers | E1 | ||
| E1 | Résultat brut d'exploitation | E2 | ||
| 5000 | Salaires | EUR | 5 | |
| 5700 | AVS, AI, APG, assurance-chômage | EUR | 5 | |
| 5710 | Caisse de compensation familiale | EUR | 5 | |
| 5720 | Prévoyance professionnelle | EUR | 5 | |
| 5730 | Assurance-accidents | EUR | 5 | |
| 5740 | Assurance pour indemnités maladie | EUR | 5 | |
| 5790 | Impôts à la source | EUR | 5 | |
| 5800 | Autres charges du personnel | EUR | 5 | |
| 5810 | Formation | EUR | 5 | |
| 5820 | Frais de voyage | EUR | 5 | |
| 5830 | Indemnités forfaitaires | EUR | 5 | |
| 5900 | Charges de personnel temporaire | EUR | 5 | |
| 5 | Charges de personnel | E2 | ||
| E2 | Résultat brut d'exploitation après charges de personnel | E3 | ||
| 6000 | Charges de locaux | EUR | 60 | |
| 6040 | Nettoyage locaux | EUR | 60 | |
| 60 | Charges de locaux | 6 | ||
| 6100 | Entretien, réparations et remplacement des inst. servant à l'exploitation | EUR | 61 | |
| 6105 | Leasing immobilisations corporelles meubles | EUR | 61 | |
| 61 | Entretien, réparations et remplacement des inst. servant à l'exploitation | 6 | ||
| 6200 | Réparations | EUR | 62 | |
| 6210 | Carburant | EUR | 62 | |
| 6220 | Assurances voitures | EUR | 62 | |
| 6260 | Leasing et location de véhicules | EUR | 62 | |
| 6270 | Charges de véhicules comme prélèvements à titre privé | EUR | 62 | |
| 6282 | Charges de transport | EUR | 62 | |
| 62 | Charges de véhicules et de transport | 6 | ||
| 6300 | Assurances-choses, droits, taxes, autorisations | EUR | 63 | |
| 63 | Assurances-choses | 6 | ||
| 6402 | Électricité | EUR | 64 | |
| 6410 | Chauffage | EUR | 64 | |
| 6430 | Eau | EUR | 64 | |
| 6460 | Évacuation des déchets | EUR | 64 | |
| 64 | Charges d'énergie et évacuation des déchets | 6 | ||
| 6500 | Matériel de bureau | EUR | 65 | |
| 6503 | Littérature technique, journaux, revues | EUR | 65 | |
| 6510 | Téléphone, Internet | EUR | 65 | |
| 6511 | Services d'hosting | EUR | 65 | |
| 6513 | Frais postaux | EUR | 65 | |
| 6570 | Charges et leasing d'informatique | EUR | 65 | |
| 6580 | Licences, updates | EUR | 65 | |
| 6583 | Consommables | EUR | 65 | |
| 65 | Charges d'administration et d'informatique | 6 | ||
| 6600 | Publicité | EUR | 66 | |
| 6642 | Cadeaux à la clientèle | EUR | 66 | |
| 66 | Publicité | 6 | ||
| 6700 | Autres charges d'exploitation | EUR | 67 | |
| 67 | Autres charges d'exploitation | 6 | ||
| 6 | Charges divers d'exploitation | E3 | ||
| E3 | Résultat d'exploitation avant intérêts, impôts et amortissements (EBITDA) | E4 | ||
| 6800 | Amortissement et ajustement de valeur des postes sur les actifs immobilisés | EUR | 68 | |
| 68 | Amortissement et ajustement de valeur des immobilitations | E4 | ||
| E4 | Résultat d'exploitation avant intérêts, impôts (EBIT) | E5 | ||
| 6900 | Charges pour intérêts bancaires | EUR | 69 | |
| 6940 | Frais bancaires | EUR | 69 | |
| 6949 | Perte de change | EUR | 69 | |
| 6950 | Intérêts actifs bancaires | EUR | 69 | |
| 6999 | Bénéfice de change | EUR | 69 | |
| 69 | Charges et produits financiers | E5 | ||
| E5 | Résultat d'exploitation avant impôts (EBT) | E6 | ||
| 7000 | Produits accessoires | EUR | 7 | |
| 7010 | Charges accessoires | EUR | 7 | |
| 7500 | Produits des immeubles d'exploitation | EUR | 7 | |
| 7510 | Charges des immeubles d'exploitation | EUR | 7 | |
| 7 | Résultat des activités annexes d'exploitation | E6 | ||
| 8000 | Charges hors exploitation | EUR | 8 | |
| 8100 | Produits hors exploitation | EUR | 8 | |
| 8500 | Charges extraordinaires, exceptionnelles ou hors période | EUR | 8 | |
| 8510 | Produits extraordinaires, exceptionnels ou hors période | EUR | 8 | |
| 8 | Résultats extraordinaires et hors exploitation | E6 | ||
| E6 | Résultat de l'exercice avant impôts | E7 | ||
| 8900 | Impôts directs | EUR | 89 | |
| 89 | Impôts directs | E7 | ||
| E7 | Résultat de l'exercice | 29A | ||
| 00 | Différence doit être = 0 (cellule vide) | |||
| Clients et Fournisseurs | ||||
| Clients | ||||
| 110001 | Société 1 | EUR | CLI | |
| 110002 | Société 2 | EUR | CLI | |
| 110003 | Société 3 | EUR | CLI | |
| CLI | Total client | 100A | ||
| Créanciers | ||||
| 200001 | Société 1 | EUR | CRE | |
| 200002 | Société 2 | EUR | CRE | |
| 200003 | Société 3 | EUR | CRE | |
| CRE | Total Créanciers | 200A | ||
| CENTRES DE COÛT | ||||
| .EMB | Emballages A | EUR | ST | |
| .MPR | Matières premières A | EUR | ST | |
| .MAU | Matières auxiliaires A | EUR | ST | |
| ST | Total Stock | |||
| ,ENT1 | Entretien1 | EUR | ENT | |
| ,ENT2 | Entretien 2 | EUR | ENT | |
| ,ENT3 | Entretien 3 | EUR | ENT | |
| ENT | Total frais d'entretien | |||
| ;PB1 | Publicité type 1 | EUR | PU | |
| ;PB2 | Publicité type 2 | EUR | PU | |
| PU | Totale charges de publicité |
| Dev.Référence | Devise | Libellé |
|---|---|---|
| EUR | CHF | Euro |
| EUR | USD | US Dollar |
Comptabilité pour sociétés de personnes morales avec les registres clients/fournisseurs
在此文中
Comptabilité pour sociétés de personnes morales avec les registres clients/fournisseurs
Comptabilité pour sociétés de personnes morales avec les registres clients/fournisseurs
Modèle idéal pour la gestion de la comptabilité de personnes morales. Le plan comptable est structuré conformément au régime des PME. Il y a des centres de coûts et la gestion des clients et fournisseurs.
模板文件
Modèle idéal pour la gestion de la comptabilité de personnes morales. Le plan comptable est structuré conformément au régime des PME. Il y a des centres de coûts et la gestion des clients et fournisseurs.
模板预览
DeviseBase: EUR
Comptabilité en partie double
| Groupe | Compte | Libellé | Add. dans |
|---|---|---|---|
| BILAN | |||
| ACTIFS | |||
| 1000 | Caisse | 100 | |
| 1020 | Banque | 100 | |
| 100 | Liquidités | 10 | |
| 1060 | Titres | 106 | |
| 106 | Avoirs à court terme cotés en bourse | 10 | |
| 1090 | Compte d'attente en monnaie | 109 | |
| 1091 | Compte d'attente salaires | 109 | |
| 1099 | Compte de passage pour éclaircissements | 109 | |
| 109 | Comptes de transit et d’attente | 10 | |
| 1100 | Créances provenant de livraisons et de prestations (Débiteurs) | 110 | |
| 1109 | Ducroire | 110 | |
| 100A | Clients | 110 | |
| 110 | Créances résultant de livraisons et prestations | 10 | |
| 1140 | Avances et prêts | 114 | |
| 1176 | Impôt anticipé | 114 | |
| 1180 | Créances envers les assurances sociales et institutions de prévoyance | 114 | |
| 1188 | Impôt à la source | 114 | |
| 1190 | Autres créances à court terme | 114 | |
| 1191 | Cautionnements en espèces | 114 | |
| 114 | Autres créances à court terme | 10 | |
| 1200 | Marchandises commerciales | 120 | |
| 1210 | Matières premières | 120 | |
| 1220 | Matières auxiliaires | 120 | |
| 1230 | Matières consommables | 120 | |
| 1260 | Stocks de produits finis | 120 | |
| 1270 | Stocks de produits pas finis | 120 | |
| 1280 | Travaux en cours | 120 | |
| 120 | Stocks et prestations non facturées | 10 | |
| 1300 | Charges payées d‘avance | 130 | |
| 1301 | Produits à recevoir | 130 | |
| 130 | Compte de régularisation de l’actif | 10 | |
| 10 | Actifs circulants | 1 | |
| 1400 | Titres à long terme | 140 | |
| 1440 | Prêts | 140 | |
| 1460 | Prêts à actionnaire | 140 | |
| 140 | Immobilisations financières | 14 | |
| 1480 | Participations | 148 | |
| 148 | Participations | 14 | |
| 1500 | Machines et appareils | 150 | |
| 1510 | Mobilier et installations | 150 | |
| 1520 | Machines de bureau, informatique, systèmes de communication | 150 | |
| 1530 | Véhicules | 150 | |
| 1540 | Outillages et appareils | 150 | |
| 150 | Immobilisations corporelles meubles | 14 | |
| 1600 | Immeubles d’exploitation | 160 | |
| 160 | Immobilisations corporelles immeubles | 14 | |
| 1700 | Brevets, know-how, licences, droits, développement | 170 | |
| 1710 | Marques commerciales | 170 | |
| 1712 | Modèles | 170 | |
| 1770 | Goodwill | 170 | |
| 170 | Immobilisations incorporelles | 14 | |
| 1850 | Capital actions, capital social, droits de participations ou capital de fondation non versés | 180 | |
| 180 | Capital non versé : capital social, capital de fondation | 14 | |
| 14 | Actifs immobilisés | 1 | |
| 1 | Total actifs | 00 | |
| PASSIFS | |||
| 2000 | Dettes résultant d’achats et de prestation de services (créanciers) | 200 | |
| 2030 | Acomptes de clients | 200 | |
| 200A | Créanciers | 200 | |
| 200 | Dettes à court terme résultant d’achats et de prestations de services | 20 | |
| 2100 | Dettes bancaires | 210 | |
| 2120 | Engagements de financement par leasing | 210 | |
| 2140 | Autres dettes à court terme rémunérées | 210 | |
| 210 | Dettes à court terme rémunérés | 20 | |
| 2200 | TVA due | 220 | |
| 2201 | Décompte TVA | 220 | |
| 2206 | Impôt anticipé dû | 220 | |
| 2208 | Impôts directs | 220 | |
| 2210 | Autres dettes à court terme | 220 | |
| 2260 | Dettes envers actionnaire | 220 | |
| 2261 | Dividendes | 220 | |
| 2270 | Assurances sociales et institutions de prévoyance | 220 | |
| 2279 | Impôt à la source | 220 | |
| 220 | Autres dettes à court terme | 20 | |
| 2300 | Charges à payer | 230 | |
| 2301 | Produits encaissés d’avance | 230 | |
| 2330 | Provisions à court terme | 230 | |
| 230 | Passifs de régularisation et provisions à court terme | 20 | |
| 20 | Dettes à court terme | 2A | |
| 2400 | Dettes bancaires | 240 | |
| 2420 | Engagements de financement par leasing | 240 | |
| 2430 | Emprunts obligataires | 240 | |
| 2450 | Emprunts | 240 | |
| 2451 | Hypothèques | 240 | |
| 240 | Dettes à long terme rémunérées | 24 | |
| 2500 | Autres dettes à long terme | 250 | |
| 250 | Autres dettes à long terme | 24 | |
| 2600 | Provisions | 260 | |
| 260 | Provisions à long termes et provisions légales | 24 | |
| 24 | Dettes à long terme | 2A | |
| 2A | Fonds étrangers | 2 | |
| 2800 | Capital-actions, capital social, capital de fondation | 280 | |
| 280 | Capital social ou capital de fondation | 28 | |
| 2900 | Réserves légales issues du capital | 290 | |
| 2940 | Réserves d‘évaluation | 290 | |
| 290 | Réserves légales issues du capital | 28 | |
| 2950 | Réserves légales issues du bénéfice | 295 | |
| 295 | Réserves légales issues du bénéfice | 28 | |
| 2960 | Réserves libres | 296 | |
| 296 | Réserves libres | 28 | |
| 2970 | Bénéfice / perte reporté | 297 | |
| 29A | Bénéfice / perte de l’exercice | 297 | |
| 297 | Bénéfice / perte du bilan | 28 | |
| 2980 | Propres actions, parts sociales, droits de participations (poste négatif) | 298 | |
| 298 | Propres actions, parts sociales, droits de participations (poste négatif) | 28 | |
| 28 | Fonds propres | 2 | |
| 2 | Total passifs | 00 | |
| COMPTE DE RÉSULTAT | |||
| 3000 | Ventes de produits fabriqués | 30 | |
| 3200 | Ventes de marchandises | 30 | |
| 3400 | Ventes de prestations | 30 | |
| 3600 | Autres ventes et prestations de services | 30 | |
| 3710 | Consommations propres | 30 | |
| 3800 | Déductions sur ventes | 30 | |
| 3805 | Pertes sur clients, variation du ducroire | 30 | |
| 30 | Chiffre d'affaires net résultant des ventes et prestations de services | 3 | |
| 3900 | Variation des stocks de produits semi-finis | 39 | |
| 3901 | Variation des stocks de produits finis | 39 | |
| 3940 | Variation de la valeur des prestations non facturées | 39 | |
| 39 | Variation des travaux en cours et des prestations non facturées | 3 | |
| 3 | Produit net des ventes et des prestations de service | E1 | |
| 4000 | Charges de matériel de l'atelier | 4 | |
| 4200 | Achats de marchandises destinées à la revente | 4 | |
| 4400 | Prestations / travaux de tiers | 4 | |
| 4500 | Charges d'énergie pour l'exploitation | 4 | |
| 4900 | Déductions sur les charges | 4 | |
| 4 | Charges de matériel, de marchandises et de prestations de tiers | E1 | |
| E1 | Résultat brut d'exploitation | E2 | |
| 5000 | Salaires | 5 | |
| 5700 | AVS, AI, APG, assurance-chômage | 5 | |
| 5710 | Caisse de compensation familiale | 5 | |
| 5720 | Prévoyance professionnelle | 5 | |
| 5730 | Assurance-accidents | 5 | |
| 5740 | Assurance pour indemnités maladie | 5 | |
| 5790 | Impôts à la source | 5 | |
| 5800 | Autres charges du personnel | 5 | |
| 5810 | Formation | 5 | |
| 5820 | Frais de voyage | 5 | |
| 5830 | Indemnités forfaitaires | 5 | |
| 5900 | Charges de personnel temporaire | 5 | |
| 5 | Charges de personnel | E2 | |
| E2 | Résultat brut d'exploitation après charges de personnel | E3 | |
| 6000 | Charges de locaux | 60 | |
| 6040 | Nettoyage locaux | 60 | |
| 60 | Charges de locaux | 6 | |
| 6100 | Entretien, réparations et remplacement des inst. servant à l'exploitation | 61 | |
| 6105 | Leasing immobilisations corporelles meubles | 61 | |
| 61 | Entretien, réparations et remplacement des inst. servant à l'exploitation | 6 | |
| 6200 | Réparations | 62 | |
| 6210 | Carburant | 62 | |
| 6220 | Assurances voitures | 62 | |
| 6260 | Leasing et location de véhicules | 62 | |
| 6270 | Charges de véhicules comme prélèvements à titre privé | 62 | |
| 6282 | Charges de transport | 62 | |
| 62 | Charges de véhicules et de transport | 6 | |
| 6300 | Assurances-choses, droits, taxes, autorisations | 63 | |
| 63 | Assurances-choses | 6 | |
| 6402 | Électricité | 64 | |
| 6410 | Chauffage | 64 | |
| 6430 | Eau | 64 | |
| 6460 | Évacuation des déchets | 64 | |
| 64 | Charges d'énergie et évacuation des déchets | 6 | |
| 6500 | Matériel de bureau | 65 | |
| 6503 | Littérature technique, journaux, revues | 65 | |
| 6510 | Téléphone, Internet | 65 | |
| 6511 | Services d'hosting | 65 | |
| 6513 | Frais postaux | 65 | |
| 6570 | Charges et leasing d'informatique | 65 | |
| 6580 | Licences, updates | 65 | |
| 6583 | Consommables | 65 | |
| 65 | Charges d'administration et d'informatique | 6 | |
| 6600 | Publicité | 66 | |
| 6642 | Cadeaux à la clientèle | 66 | |
| 66 | Publicité | 6 | |
| 6700 | Autres charges d'exploitation | 67 | |
| 67 | Autres charges d'exploitation | 6 | |
| 6 | Charges divers d'exploitation | E3 | |
| E3 | Résultat d'exploitation avant intérêts, impôts et amortissements (EBITDA) | E4 | |
| 6800 | Amortissement et ajustement de valeur des postes sur les actifs immobilisés | 68 | |
| 68 | Amortissement et ajustement de valeur des immobilitations | E4 | |
| E4 | Résultat d'exploitation avant intérêts, impôts (EBIT) | E5 | |
| 6900 | Charges pour intérêts bancaires | 69 | |
| 6940 | Frais bancaires | 69 | |
| 6950 | Produits financiers | 69 | |
| 69 | Charges et produits financiers | E5 | |
| E5 | Résultat d'exploitation avant impôts (EBT) | E6 | |
| 7000 | Produits accessoires | 7 | |
| 7010 | Charges accessoires | 7 | |
| 7500 | Produits des immeubles d'exploitation | 7 | |
| 7510 | Charges des immeubles d'exploitation | 7 | |
| 7 | Résultat des activités annexes d'exploitation | E6 | |
| 8000 | Charges hors exploitation | 8 | |
| 8100 | Produits hors exploitation | 8 | |
| 8500 | Charges extraordinaires, exceptionnelles ou hors période | 8 | |
| 8510 | Produits extraordinaires, exceptionnels ou hors période | 8 | |
| 8 | Résultats extraordinaires et hors exploitation | E6 | |
| E6 | Résultat de l'exercice avant impôts | E7 | |
| 8900 | Impôts directs | 89 | |
| 89 | Impôts directs | E7 | |
| E7 | Résultat de l'exercice | 29A | |
| 00 | Différence doit être = 0 (cellule vide) | ||
| Clients et Fournisseurs | |||
| Clients | |||
| 110001 | Société 1 | CLI | |
| 110002 | Société 2 | CLI | |
| 110003 | Société 3 | CLI | |
| CLI | Total client | 100A | |
| Créanciers | |||
| 200001 | Société 1 | CRE | |
| 200002 | Société 2 | CRE | |
| 200003 | Société 3 | CRE | |
| CRE | Total Créanciers | 200A | |
| CENTRES DE COÛT | |||
| .EMB | Emballages A | ST | |
| .MPR | Matières premières A | ST | |
| .MAU | Matières auxiliaires A | ST | |
| ST | Total Stock | ||
| ,ENT1 | Entretien1 | ENT | |
| ,ENT2 | Entretien 2 | ENT | |
| ,ENT3 | Entretien 3 | ENT | |
| ENT | Total frais d'entretien | ||
| ;PB1 | Publicité type 1 | PU | |
| ;PB2 | Publicité type 2 | PU | |
| PU | Totale charges de publicité | ||
公司会计 (含中英文报表)
Comptabilité pour Entreprises Individuelles
在此文中
Comptabilité pour Entreprises Individuelles
Comptabilité pour Entreprises Individuelles
Pour gérer les comptes d'une petite entreprise individuelle. Le plan comptable est structuré avec des groupes et sousgroupes et centres de coût.
模板文件
Pour gérer les comptes d'une petite entreprise individuelle. Le plan comptable est structuré avec des groupes et sousgroupes et centres de coût.
模板预览
DeviseBase: EUR
Comptabilité en partie double
| Groupe | Compte | Libellé | Add. dans |
|---|---|---|---|
| BILAN | |||
| ACTIFS | |||
| 1000 | Caisse | 100 | |
| 1020 | Banque | 100 | |
| 100 | Liquidités | 10 | |
| 1060 | Titres | 106 | |
| 106 | Avoirs à court terme cotés en bourse | 10 | |
| 1090 | Compte d'attente en monnaie | 109 | |
| 1091 | Compte d'attente salaires | 109 | |
| 1099 | Compte de passage pour éclaircissements | 109 | |
| 109 | Comptes de transit et d’attente | 10 | |
| 1100 | Créances provenant de livraisons et de prestations (Débiteurs) | 110 | |
| 1109 | Ducroire | 110 | |
| 110 | Créances résultant de livraisons et prestations | 10 | |
| 1140 | Avances et prêts | 114 | |
| 1176 | Impôt anticipé | 114 | |
| 1180 | Créances envers les assurances sociales et institutions de prévoyance | 114 | |
| 1188 | Impôt à la source | 114 | |
| 1190 | Autres créances à court terme | 114 | |
| 1191 | Cautionnements en espèces | 114 | |
| 114 | Autres créances à court terme | 10 | |
| 1200 | Marchandises commerciales | 120 | |
| 1210 | Matières premières | 120 | |
| 1220 | Matières auxiliaires | 120 | |
| 1230 | Matières consommables | 120 | |
| 1250 | Marchandises en consignation | 120 | |
| 1260 | Stocks de produits finis | 120 | |
| 1270 | Stocks de produits pas finis | 120 | |
| 1280 | Travaux en cours | 120 | |
| 120 | Stocks et prestations non facturées | 10 | |
| 1300 | Charges payées d‘avance | 130 | |
| 1301 | Produits à recevoir | 130 | |
| 130 | Compte de régularisation de l’actif | 10 | |
| 10 | Actifs circulants | 1 | |
| 1400 | Titres à long terme | 140 | |
| 1440 | Prêts | 140 | |
| 140 | Immobilisations financières | 14 | |
| 1480 | Participations | 148 | |
| 148 | Participations | 14 | |
| 1500 | Machines et appareils | 150 | |
| 1510 | Mobilier et installations | 150 | |
| 1520 | Machines de bureau, informatique, systèmes de communication | 150 | |
| 1530 | Véhicules | 150 | |
| 1540 | Outillages et appareils | 150 | |
| 150 | Immobilisations corporelles meubles | 14 | |
| 1600 | Immeubles d’exploitation | 160 | |
| 160 | Immobilisations corporelles immeubles | 14 | |
| 14 | Actifs immobilisés | 1 | |
| 1 | Total actifs | 00 | |
| PASSIFS | |||
| 2000 | Dettes résultant d’achats et de prestation de services (créanciers) | 200 | |
| 2030 | Acomptes de clients | 200 | |
| 200 | Dettes à court terme résultant d’achats et de prestations de services | 20 | |
| 2100 | Dettes bancaires | 210 | |
| 2120 | Engagements de financement par leasing | 210 | |
| 2140 | Autres dettes à court terme rémunérées | 210 | |
| 210 | Dettes à court terme rémunérés | 20 | |
| 2206 | Impôt anticipé dû | 220 | |
| 2208 | Impôts directs | 220 | |
| 2210 | Autres dettes à court terme | 220 | |
| 2270 | Assurances sociales et institutions de prévoyance | 220 | |
| 2279 | Impôt à la source | 220 | |
| 220 | Autres dettes à court terme | 20 | |
| 2300 | Charges à payer | 230 | |
| 2301 | Produits encaissés d’avance | 230 | |
| 2330 | Provisions à court terme | 230 | |
| 230 | Passifs de régularisation et provisions à court terme | 20 | |
| 20 | Dettes à court terme | 2A | |
| 2400 | Dettes bancaires | 240 | |
| 2420 | Engagements de financement par leasing | 240 | |
| 2430 | Emprunts obligataires | 240 | |
| 2450 | Emprunts | 240 | |
| 2451 | Hypothèques | 240 | |
| 240 | Dettes à long terme rémunérées | 24 | |
| 2500 | Autres dettes à long terme | 250 | |
| 250 | Autres dettes à long terme | 24 | |
| 2600 | Provisions | 260 | |
| 260 | Provisions à long termes et provisions légales | 24 | |
| 24 | Dettes à long terme | 2A | |
| 2A | Fonds étrangers | 2 | |
| 2800 | Capital propre en début d’exercice | 28 | |
| 2820 | Apports de capital / prélèvements sur capital | 28 | |
| 2850 | Compte privé | 28 | |
| 297 | Bénéfice de l'exercice / Perte de l'exercice | 28 | |
| 28 | Fonds propres | 2 | |
| 2 | Total passifs | 00 | |
| COMPTE DE RÉSULTAT | |||
| 3000 | Ventes de produits fabriqués | 30 | |
| 3200 | Ventes de marchandises | 30 | |
| 3400 | Ventes de prestations | 30 | |
| 3600 | Autres ventes et prestations de services | 30 | |
| 3700 | Prestations propres | 30 | |
| 3710 | Consommations propres | 30 | |
| 3800 | Déductions sur ventes | 30 | |
| 3805 | Pertes sur clients, variation du ducroire | 30 | |
| 30 | Chiffre d'affaires net résultant des ventes et prestations de services | 3 | |
| 3900 | Variation des stocks de produits semi-finis | 39 | |
| 3901 | Variation des stocks de produits finis | 39 | |
| 3940 | Variation de la valeur des prestations non facturées | 39 | |
| 39 | Variation des travaux en cours et des prestations non facturées | 3 | |
| 3 | Produit net des ventes et des prestations de service | E1 | |
| 4000 | Charges de matériel de l'atelier | 4 | |
| 4200 | Achats de marchandises destinées à la revente | 4 | |
| 4400 | Prestations / travaux de tiers | 4 | |
| 4500 | Charges d'énergie pour l'exploitation | 4 | |
| 4900 | Déductions sur les charges | 4 | |
| 4 | Charges de matériel, de marchandises et de prestations de tiers | E1 | |
| E1 | Résultat brut d'exploitation | E2 | |
| 5000 | Salaires | 5 | |
| 5700 | AVS, AI, APG, assurance-chômage | 5 | |
| 5710 | Caisse de compensation familiale | 5 | |
| 5720 | Prévoyance professionnelle | 5 | |
| 5730 | Assurance-accidents | 5 | |
| 5740 | Assurance pour indemnités maladie | 5 | |
| 5790 | Impôts à la source | 5 | |
| 5800 | Autres charges du personnel | 5 | |
| 5810 | Formation | 5 | |
| 5820 | Frais de voyage | 5 | |
| 5830 | Indemnités forfaitaires | 5 | |
| 5900 | Charges de personnel temporaire | 5 | |
| 5 | Charges de personnel | E2 | |
| E2 | Résultat brut d'exploitation après charges de personnel | E3 | |
| 6000 | Charges de locaux | 60 | |
| 6040 | Nettoyage locaux | 60 | |
| 60 | Charges de locaux | 6 | |
| 6100 | Entretien, réparations et remplacement des inst. servant à l'exploitation | 61 | |
| 6105 | Leasing immobilisations corporelles meubles | 61 | |
| 61 | Entretien, réparations et remplacement des inst. servant à l'exploitation | 6 | |
| 6200 | Réparations | 62 | |
| 6210 | Carburant | 62 | |
| 6220 | Assurances voitures | 62 | |
| 6260 | Leasing et location de véhicules | 62 | |
| 6270 | Charges de véhicules comme prélèvements à titre privé | 62 | |
| 6282 | Charges de transport | 62 | |
| 62 | Charges de véhicules et de transport | 6 | |
| 6300 | Assurances-choses, droits, taxes, autorisations | 63 | |
| 63 | Assurances-choses | 6 | |
| 6402 | Électricité | 64 | |
| 6410 | Chauffage | 64 | |
| 6430 | Eau | 64 | |
| 6460 | Évacuation des déchets | 64 | |
| 64 | Charges d'énergie et évacuation des déchets | 6 | |
| 6500 | Matériel de bureau | 65 | |
| 6510 | Téléphone, Internet | 65 | |
| 6511 | Services d'hosting | 65 | |
| 6513 | Frais postaux | 65 | |
| 6570 | Charges et leasing d'informatique | 65 | |
| 6580 | Licences, updates | 65 | |
| 6583 | Consommables | 65 | |
| 65 | Charges d'administration et d'informatique | 6 | |
| 6600 | Publicité | 66 | |
| 6642 | Cadeaux à la clientèle | 66 | |
| 66 | Publicité | 6 | |
| 6700 | Autres charges d'exploitation | 67 | |
| 67 | Autres charges d'exploitation | 6 | |
| 6 | Charges divers d'exploitation | E3 | |
| E3 | Résultat d'exploitation avant intérêts, impôts et amortissements (EBITDA) | E4 | |
| 6800 | Amortissement et ajustement de valeur des postes sur les actifs immobilisés | 68 | |
| 68 | Amortissement et ajustement de valeur des immobilitations | E4 | |
| E4 | Résultat d'exploitation avant intérêts, impôts (EBIT) | E5 | |
| 6900 | Charges pour intérêts bancaires | 69 | |
| 6940 | Frais bancaires | 69 | |
| 6950 | Produits financiers | 69 | |
| 69 | Charges et produits financiers | E5 | |
| E5 | Résultat d'exploitation avant impôts (EBT) | E6 | |
| 7000 | Produits accessoires | 7 | |
| 7010 | Charges accessoires | 7 | |
| 7500 | Produits des immeubles d'exploitation | 7 | |
| 7510 | Charges des immeubles d'exploitation | 7 | |
| 7 | Résultat des activités annexes d'exploitation | E6 | |
| 8000 | Charges hors exploitation | 8 | |
| 8100 | Produits hors exploitation | 8 | |
| 8500 | Charges extraordinaires, exceptionnelles ou hors période | 8 | |
| 8510 | Produits extraordinaires, exceptionnels ou hors période | 8 | |
| 8 | Résultats extraordinaires et hors exploitation | E6 | |
| E6 | Résultat de l'exercice avant impôts | E7 | |
| 8900 | Impôts directs | 89 | |
| 89 | Impôts directs | E7 | |
| E7 | Résultat de l'exercice | 297 | |
| 00 | Différence doit être = 0 (cellule vide) | ||
| CENTRES DE COÛT | |||
| .EMB | Emballages A | ST | |
| .MPR | Matières premières A | ST | |
| .MAU | Matières auxiliaires A | ST | |
| ST | Total Stock | ||
| ,ENT1 | Entretien1 | ENT | |
| ,ENT2 | Entretien 2 | ENT | |
| ,ENT3 | Entretien 3 | ENT | |
| ENT | Total frais d'entretien | ||
| ;PB1 | Publicité type 1 | PU | |
| ;PB2 | Publicité type 2 | PU | |
| PU | Totale charges de publicité | ||
Yacht, Boats, Cruises Income & Expense Accounting Log Book with Budget and Cash Plan
在此文中
Yacht, Boats, Cruises Income & Expense Accounting Log Book with Budget and Cash Plan
Yacht, Boats, Cruises Income & Expense Accounting Log Book with Budget and Cash Plan
Easily start log your boat's income and expenses and know right away how much your boat costs and how much you spent on fuel, maintenance, food and all other categories. Link transactions with a digital receipt and get rid of paper. Prepare the budget and you also have cash forecast and comparisons. Easily present accurate reports to the shipowner.
模板文件
Track yacht or sailboat expenses and revenues. No need of accounting experience.
Easy to use Accounting software for Yacht. Predefined account file with chart of account, with comprehensive list of expenses (Engine, Crew, Administrative, Guests) and Revenues, that can be easily adapted for your specific needs.
This accounting template provides.
- Predefined account chart with Expenses (Engine, Crew, Administrative, Guests) and Revenues that can be easily adapted for your specific needs.
- Cost and revenues subdivision also by cruise.
模板预览
Best Yacht
| Group | Account | Description | Sum In |
|---|---|---|---|
| ESTATE | |||
| ASSETS | |||
| Cash | Cash | 10 | |
| Credit Card | Credit Card | 10 | |
| Bank | Bank | 10 | |
| Money Transit | Money Transit | 10 | |
| 10 | Total liquid assets | 1 | |
| Shipowner | Shipowner: Benefits & Sponsorship | 11 | |
| 11 | Total other assets | 1 | |
| Machine Assets | Machine Room Assets | 12 | |
| Hull Assets | Hull Assets | 12 | |
| Deck Assets | Deck Assets | 12 | |
| Below Assets | Below Deck Assets | 12 | |
| Sail Assets | Rigging & Sail Assets | 12 | |
| 12 | Totale Hull and Restructuring | 1 | |
| 1 | TOTALE ASSETS | 0 | |
| LIABILITIES | |||
| Suppliers | Suppliers | 2 | |
| Bank Loan | Bank Loan | 2 | |
| Partner Financier | Partner Financier | 2 | |
| 2 | TOTAL LIABILITIES | 0 | |
| 0 | NET ESTATE | ||
| Group | Category | Description | Sum In |
|---|---|---|---|
| OPERATING RESULT | |||
| INCOME | |||
| Shipowner Charter | Shipowner Charter | 4 | |
| Third parties Carter | Third parties Carter | 4 | |
| Shipowner Cash | Shipowner Cash | 4 | |
| Guests Cash | Guests Cash | 4 | |
| Extraordinary Income | Extraordinary Income | 4 | |
| 4 | TOTAL INCOME | 00 | |
| EXPENSES | |||
| Crew Wages | Crew Wages | 30 | |
| Crew Insurances | Crew Insurances | 30 | |
| Crew Transports | Crew Transports | 30 | |
| Crew Food | Crew Food | 30 | |
| 30 | Total crew costs | 3 | |
| Hull Improvements | Hull Improvements | 31 | |
| Engine Improvements | Engine Improvements | 31 | |
| Electrical Improvements | Electrical Improvements | 31 | |
| Internal Improvements | Internal Improvements | 31 | |
| Sail Improvements | Sail and Rigging Improvements | 31 | |
| 31 | Total improvement costs | 3 | |
| Hull Maintenance | Hull Maintenance | 32 | |
| Engine Maintenance | Engine Maintenance | 32 | |
| Electrical Maintenance | Electrical Maintenance | 32 | |
| Miscellaneous Maintenance | Miscellaneous Maintenance | 32 | |
| Tender Maintenance | Tender Maintenance | 32 | |
| 32 | Total maintenance costs | 3 | |
| Corporate | Corporate | 33 | |
| Insurance | Yacht Insurance | 33 | |
| Office | Office Material | 33 | |
| Pharmacy | Pharmacy / Hygiene | 33 | |
| Communication | Communication / Wireless | 33 | |
| Bank Charges | Bank Charges | 33 | |
| 33 | Total administrative costs | 3 | |
| Fuel | Fuel | 34 | |
| Moorings | Moorings | 34 | |
| Food Guests | Guests and General Food | 34 | |
| Food Shipowner | Shipowner Good | 34 | |
| Wine | Wine | 34 | |
| Laundry | Laundry | 34 | |
| Guests transport | Guests Transport | 34 | |
| Various | Various | 34 | |
| 34 | Total operating/charter costs | 3 | |
| 3 | TOTAL EXPENSES | 00 | |
| 00 | RESULT | ||
| Profit and Cost centers | |||
| Cruises | |||
| .Cruise1 | Cruise 1 | C | |
| .Cruise2 | Cruise 2 | C | |
| .Cruise3 | Cruise 3 | C | |
| C | Total cruise |
公司的复式记账模板
在此文中
公司的复式记账模板
公司的复式记账模板
轻松地、免费地开始您公司的复式记账,并立即获得损益表和资产负债表。可以根据您的具体需要对这个现成的模板进行编辑,用来管理您的公司、独资企业、合伙企业或中小型企业的会计。Banana财务会+ 是一个专业的软件,由于它类似于Excel,所以使用起来非常直观和快速。如果在做账中出现了错误,也可以随时纠正,直到获得完美的会计报表。
直接在网页中打开Banana财务会计+
无需任何安装,可以直接在您的浏览器上运行 Banana财务会计+。客制化您的模板,输入发生业务并将文件保存在您的电脑上。
在浏览器中打开模板 Open tutorial in WebApp模板预览
XX公司
本位币: USD
复式记账
| 总组 | 账号 | 摘要 | 总和 |
|---|---|---|---|
| 资产负债表 | |||
| 资产 | |||
| 银行账户 | |||
| 商业账户 | 商业账户 | 银行 | |
| 商业存储账户 | 商业存储账户 | 银行 | |
| 工资账户 | 工资账户 | 银行 | |
| 现金 | 小额现金 - 自付費用 | 银行 | |
| 易货贸易 | 易货贸易账户 | 银行 | |
| 银行 | 银行账户总计 | 资产 | |
| 应收账款 | |||
| 客户 | 应收账款 (客户登记) | 应收 | |
| 应收 | 应收账款总计 | 资产 | |
| 流动资产 | |||
| 库存 | 库存 | 流动资产 | |
| 未存入的资金 | 未存入的资金 | 流动资产 | |
| 流动资产 | 流动资产总计 | 资产 | |
| 固定资产 | |||
| 设备 | 设备 | 固定 | |
| 家具 | 家具和固定装置 | 固定 | |
| 车辆 | 车辆 | 固定 | |
| 累计折旧 | 累计折旧 | 固定 | |
| 固定 | 固定资产总计 | 资产 | |
| 其它资产 | |||
| 启动 | 启动成本 (会计人员使用) | 其它 | |
| 摊销 | 累计摊销 | 其它 | |
| 应收票据1 | 应收票据1 (高级职员、所有者、关联方) | 其它 | |
| 应收票据2 | 应收票据2 | 其它 | |
| 其它 | 其它资产总计 | 资产 | |
| 资产 | 总资产 | 00 | |
| 负债 | |||
| 应付账款 | |||
| 供应商 | 供应商登记 | 应付 | |
| 应付 | 应付账款总计 | 负债 | |
| 用于采购的信用卡 | |||
| 美国运通 | 美国运通 - 信用卡贷款 | 信用卡 | |
| Visa | Visa - 信用卡贷款 | 信用卡 | |
| 信用卡 | 信用卡总计 | 负债 | |
| 流动负债 | |||
| 应计 | 应计费用 | 流动负债 | |
| 应付薪资税 | 应付薪资税 | 流动负债 | |
| 应付营业税 | 应付营业税 | 流动负债 | |
| 押金 | 客户押金 | 流动负债 | |
| 长期部分 | 长期负债的流动部分 | 流动负债 | |
| 流动负债 | 流动负债总计 | 负债 | |
| 长期负债 | |||
| 银行贷款 | 银行贷款 | 长期负债 | |
| 应付票据1 | 应付票据1 | 长期负债 | |
| 应付票据2 | 应付票据2 | 长期负债 | |
| 长期负债 | 长期负债总计 | 负债 | |
| 负债 | 总负债 | 00 | |
| 股权 | |||
| 资本 | 股本/资本合伙人 | 股权 | |
| 附加资本 | 额外出资/额外支付资本 | 股权 | |
| 留存收益 | 留存收益 | 股权 | |
| 期初权益 | 期初余额权益 | 股权 | |
| 股东1 | 分配股东 1 / 股息 / 提款 | 股权 | |
| 结转 | 结转盈亏 | 股权 | |
| 盈利或亏损 | 本年度损益 | 股权 | |
| 股权 | 股权总计 | 00 | |
| 损益表 | |||
| 收入 | |||
| 服务 | 服务收入 | 收入 | |
| 售出的产品 | 零件/产品销售收入 | 收入 | |
| 销售冲销 | 销售冲销 | 收入 | |
| 收入 | 总收入 | 毛利润 | |
| 销货成本 | |||
| 材料费 | 材料、直接产品/服务成本 | 销货成本 | |
| 人工费 | 人工成本 | 销货成本 | |
| 外部服务 | 外部服务/分包商 | 销货成本 | |
| 供应品 | 耗材成本 | 销货成本 | |
| 小型工具 | 小型工具 | 销货成本 | |
| 销货成本 | 销货成本总计 | 毛利润 | |
| 毛利润 | 毛利润 | 息税前利润 | |
| 费用 | |||
| 广告 | 广告、促销、营销费用 | 费用 | |
| 汽车 | 汽车费用 | 费用 | |
| 银行收费 | 银行服务费 | 费用 | |
| 清洁费 | 清洁费 | 费用 | |
| 捐款 | 捐款 | 费用 | |
| 折旧 | 折旧费用 | 费用 | |
| 折扣 | 采取的折扣 | 费用 | |
| 订阅费 | 捐款和订阅费 | 费用 | |
| 保险费 | 汽车保险、人寿、医疗 | 费用 | |
| 利息支出 | 利息支出 | 费用 | |
| 许可证 | 商业执照和许可证 | 费用 | |
| 维修费 | 维护和修理 | 费用 | |
| 餐费 | 膳食和娱乐 | 费用 | |
| 商户费用 | 商家信用卡费用 | 费用 | |
| 办公室 | 办公费用(电脑、邮资、快递、用品)。 | 费用 | |
| 薪资税 | 薪资税 | 费用 | |
| 专业费用 | 专业费用 | 费用 | |
| 租金 | 租金支付 | 费用 | |
| 工资 | 工资 | 费用 | |
| 电话费 | 电话、传真 | 费用 | |
| 旅行 | 旅行 | 费用 | |
| 公用事业 | 公用事业 | 费用 | |
| 费用 | 总费用 | 息税前利润 | |
| 息税前利润 | 息税前利润 | 结果 | |
| 其它收入 | |||
| 利息收入 | 利息收入 | 其它收入 | |
| 其它收入 | 其它收入总计 | 结果 | |
| 其它费用 | |||
| 会计师咨询 | 会计师咨询 | 其它费用 | |
| 其它费用 | 其它费用总计 | 结果 | |
| 结果 | 净利 (盈利(-) 亏损(+) ) | 盈利或亏损 | |
| 00 | 差额应该是=0(空白单元格) | ||
| 客户/供应商登记 | |||
| 客户 | |||
| 客户-Redford | Redford 公司 | 客户总计 | |
| 客户-Smith | John Smith | 客户总计 | |
| 客户-Black | Simon Black | 客户总计 | |
| 客户总计 | 客户总计 | 客户 | |
| 供应商 | |||
| 供应商-Johnson | Johnson 公司 | 供应商总计 | |
| 供应商-Marble | Marble | 供应商总计 | |
| 供应商-Taylor | Mary Taylor | 供应商总计 | |
| 供应商总计 | 供应商总计 | 供应商 | |
| 成本中心 | |||
| 产品 | |||
| .产品 A | 产品 A | 产品 | |
| .产品 B | 产品 B | 产品 | |
| .产品 C | 产品 C | 产品 | |
| 产品 | 产品总计 | ||
| 项目 | |||
| ;项目 A | 项目 A | 项目 | |
| ;项目 B | 项目 B | 项目 | |
| 项目 | 项目总计 | ||
| 部门 | |||
| 分公司 | |||
| :分公司 A | 分公司 A | 分公司 | |
| :分公司 B | 分公司 B | 分公司 | |
| 分公司 | 分公司总计 | ||
Buchhaltung mit Budget für ein Restaurant | Beschreibende Konten
在此文中
Buchhaltung mit Budget für ein Restaurant | Beschreibende Konten
Buchhaltung mit Budget für ein Restaurant | Beschreibende Konten
Mit dieser Vorlage erfassen Sie ganz einfach Ihre Einnahmen und Ausgaben – ideal für Gastronomiebetriebe jeder Art. Ob Restaurant, Café, Pizzeria oder Take-Away: Sie behalten jederzeit den Überblick über Ihre Finanzen, ohne sich mit komplexen Buchhaltungsstrukturen auseinandersetzen zu müssen. Einfach, klar und effizient – damit Sie mehr Zeit fürs Kerngeschäft haben.
直接在网页中打开Banana财务会计+
无需任何安装,可以直接在您的浏览器上运行 Banana财务会计+。客制化您的模板,输入发生业务并将文件保存在您的电脑上。
在浏览器中打开模板 Open tutorial in WebApp模板文件
Budget für ein Restaurant erstellen
In jedem Betrieb ist es entscheidend, im Laufe des Jahres fundierte Entscheidungen über die wirtschaftliche und finanzielle Lage treffen zu können – idealerweise mit der Möglichkeit, frühzeitig einzugreifen, bevor es zu spät ist. Aus diesem Grund bietet Banana Buchhaltung in seinen Vorlagen die Funktion "Budget", mit der Sie ganz einfach den Finanzplan für Ihr Restaurant erstellen können.
Wir begleiten Sie Schritt für Schritt bei der Budgetplanung. Folgen Sie einfach den nachstehenden Anleitungen – es ist schnell und unkompliziert, sodass Sie sich direkt wieder auf Ihr Geschäft und Ihre Gäste konzentrieren können!
1. Einnahmen eingeben
Beginnen Sie mit der Erfassung der fixen Einnahmen. Als Orientierung können die Einnahmen des Vorjahres dienen.
In der Regel setzen sich die Einnahmen aus folgenden Bereichen zusammen:
- Lebensmittelverkäufen
- Getränkeverkäufen
Gerade bei Restaurants empfiehlt es sich, die Umsätze für Speisen und Getränke monatsweise zu planen, da diese je nach Feiertagen und Jahreszeit stark schwanken können. Selbstverständlich können Sie die Verkaufspositionen individuell anpassen – z.B. durch eine weitere Untergliederung nach Art der Speisen oder Getränke.
Darüber hinaus gibt es möglicherweise Einnahmen, die nicht direkt aus dem Tagesgeschäft Ihres Betriebs stammen, zum Beispiel:
- Mieteinnahmen aus Immobilien
- Zinserträge von Bank- oder Postkonten
Eine Anleitung zur technischen Eingabe der Budgetdaten im Banana-Programm finden Sie auf unserer Webseite unter Tabelle Budget.

2. Fixe und variable Ausgaben eingeben
Listen Sie alle Ausgaben auf, die im Laufe des Jahres zu erwarten sind. Auch hier können Ihnen die Werte des Vorjahres als Orientierung dienen. Überlegen Sie dabei, ob sich Änderungen abzeichnen, und passen Sie die Beträge entsprechend an.
Zu den wichtigsten Ausgabeposten zählen:
- Waren- und Rohstoffeinkauf (z.B. Lebensmittel und Getränke)
- Löhne und Gehälter
- Ausrüstung und Ausstattung
- Sozialversicherungsbeiträge
- Versicherungen (z.B. für Personal, Maschinen, Sachwerte)
- Miete, Hypotheken, Zinsen
- Steuern und Abgaben
- Energie- und Betriebskosten (Strom, Wasser, Gas)
- Telefon- und Internetkosten
- Reinigungsdienste
- Werbung und Marketing
Gerade bei Lebensmitteln und Getränken ist es sinnvoll, die Ausgaben monatsweise zu planen, da sich die Kosten je nach Saison oder Feiertagen deutlich verändern können.

3. Einnahmen und Ausgaben vergleichen
Nachdem Sie alle geplanten Einnahmen und Ausgaben aufgelistet haben, sollten Sie diese miteinander vergleichen, um zu erkennen, ob Sie Ihr angestrebtes Gewinnziel realistisch erreichen können.
Für diesen Vergleich benötigen Sie einen Budgetbericht. Wenn Sie eine Vorlage von Banana Buchhaltung verwenden, wählen Sie im Menü Berichte > Formatierte Bilanz nach Gruppen den gewünschten Budgetbericht aus – in der Regel ist der Jahresbudget-Bericht hier besonders hilfreich.
Beim Prüfen des Budgets sehen Sie, wie hoch Ihre Liquidität, Ihre Verbindlichkeiten und Ihr Gesamtvermögen auf Basis der eingeplanten Einnahmen und Ausgaben ausfallen werden.
Mit diesem Gesamtüberblick können Sie besser einschätzen, ob bestimmte Posten über- oder unterschätzt wurden.
Sollte sich eine Verlustsituation abzeichnen, empfiehlt es sich, frühzeitig mögliche Sparpotenziale zu prüfen: Überarbeiten Sie Ihre geplanten Ausgaben und passen Sie die Beträge entsprechend an, um Ihre finanziellen Ziele abzusichern.

4. Überprüfung mit der Bilanz zum Jahresende
Am Ende des Jahres, wenn alle Buchungen erfasst sind, können Sie einen Bericht erstellen, der die Endbestände aller Konten anzeigt und diese mit den budgetierten Werten vergleicht. So prüfen Sie zuverlässig, ob Ihre zu Jahresbeginn erstellte Planung realistisch war – und ob Sie den angestrebten Gewinn tatsächlich erreicht haben.
Für den Vergleich der geplanten Werte mit den tatsächlichen Endsalden wählen Sie im Menü Berichte > Formatierte Bilanz nach Gruppen den Befehl Jährlicher Ausdruck mit Budgetvergleich.
Bei grösseren Abweichungen können Sie analysieren, bei welchen Einnahmen oder Ausgaben Ihre ursprünglichen Schätzungen ungenau waren – und die entsprechenden Beträge im Budget für das neue Jahr gezielt anpassen.

模板预览
Restaurant
Buchhaltung 2022
| Gruppe | Konto | Beschreibung | Summ. in |
|---|---|---|---|
| BESTAND | |||
| Aktiven | |||
| Kasse | Kasse | Total Aktiven | |
| Bankkonto | Bankkonto | Total Aktiven | |
| Post | Postscheckkonto | Total Aktiven | |
| Transferkonto | Transferkonto | Total Aktiven | |
| Kunden | Kundenkonto | Total Aktiven | |
| Mobiliar | Mobiliar und Einrichtungen | Total Aktiven | |
| Küchenausstattung | Küchenausstattung | Total Aktiven | |
| Lagerverwaltung | Lagerverwaltung | Total Aktiven | |
| Total Aktiven | Total Aktiven | TOTAL BESTAND | |
| Passiven | |||
| Kredit | Kredit | Total Passiven | |
| Lieferanten | Lieferantenkonto | Total Passiven | |
| Total Passiven | Total Passiven | TOTAL BESTAND | |
| TOTAL BESTAND | TOTAL BESTAND | ||
| Gruppe | Kategorie | Beschreibung | Summ. in |
|---|---|---|---|
| BETRIEBSERGEBNIS | |||
| EINNAHMEN | |||
| Verkäufe | Verkauf von Lebensmitteln und Getränken | Total Einnahmen | |
| Handelswarenerlöse | Handelswarenerlöse | Total Einnahmen | |
| Zinserträge | Zinserträge | Total Einnahmen | |
| Total Einnahmen | Total Einnahmen | TOTAL Betriebsergebnis | |
| AUSGABEN | |||
| Einkauf von Lebensmitteln und Getränken | Einkauf von Lebensmitteln und Getränken | Total eingekaufter Produkte | |
| Einkauf von Waren | Einkauf von Waren | Total eingekaufter Produkte | |
| Total eingekaufter Produkte | Total eingekaufter Produkte | Total variable Kosten | |
| Personalkosten | Personalkosten | Totalkosten Gehälter | |
| Steuern und Sozialleistungen | Steuern und Sozialleistungen | Totalkosten Gehälter | |
| Personalversicherung | Personalversicherung | Totalkosten Gehälter | |
| Totalkosten Gehälter | Totalkosten Gehälter | Total variable Kosten | |
| Total variable Kosten | Total variable Kosten | Total Ausgaben | |
| Reinigung | Reinigung | Total direkte Betriebskosten | |
| Handys | Handys | Total direkte Betriebskosten | |
| Kreditkarte | Kreditkartengebühren | Total direkte Betriebskosten | |
| Total direkte Betriebskosten | Total direkte Betriebskosten | Total Ausgaben | |
| Verkäufe und Marketing | Verkäufe und Marketing | Total Betriebskosten | |
| Rabatte und Coupons | Rabatte und Coupons | Total Betriebskosten | |
| Elektrizität | Elektrizität | Total Betriebskosten | |
| Wasser | Wasser | Total Betriebskosten | |
| Erdgas | Erdgas | Total Betriebskosten | |
| Holz | Holz | Total Betriebskosten | |
| Reparaturen | Reparaturen und Unterhalt | Total Betriebskosten | |
| Total Betriebskosten | Total Betriebskosten | Total Ausgaben | |
| Mietzins und Nebenkosten | Mietzins und Nebenkosten | Total Immobilienkosten | |
| Immobilien | Immobilien-Grundsteuer | Total Immobilienkosten | |
| Unterhalt Immobilien | Unterhalt Immobilien | Total Immobilienkosten | |
| Gebäudeversicherung | Gebäudeversicherung | Total Immobilienkosten | |
| Total Immobilienkosten | Total Immobilienkosten | Total Ausgaben | |
| Passive Rückversicherung | Passive Rückversicherung (Haftpflichtversicherung) | Total fixe Kosten | |
| Arbeitsunfallversicherung | Arbeitsunfallversicherung für Arbeitnehmer | Total fixe Kosten | |
| Telefon und Internet | Telefon und Internet | Total fixe Kosten | |
| TV | Kabel-/Satelliten-TV | Total fixe Kosten | |
| Bewilligungen | Bewilligungen | Total fixe Kosten | |
| Fehlmenge | Fehlmenge | Total fixe Kosten | |
| Servicearbeiten | Servicearbeiten | Total fixe Kosten | |
| Schädlingsbekämpfung | Schädlingsbekämpfung | Total fixe Kosten | |
| Müllabfuhr | Müllabfuhr | Total fixe Kosten | |
| Gesundheitsdienst | Gesundheitsdienst | Total fixe Kosten | |
| Büromaterial | Büromaterial | Total fixe Kosten | |
| Bankspesen | Bankspesen | Total fixe Kosten | |
| Administrative Kosten | Administrative Kosten | Total fixe Kosten | |
| Steuern | Steuern | Total fixe Kosten | |
| Gesundheitsministerium | Gesundheitsministerium (Beratung) | Total fixe Kosten | |
| Sonstige Kosten | Sonstige Kosten | Total fixe Kosten | |
| Total fixe Kosten | Total fixe Kosten | Total Ausgaben | |
| Total Ausgaben | Total Ausgaben | TOTAL Betriebsergebnis | |
| TOTAL Betriebsergebnis | TOTAL Betriebsergebnis | ||
| KOSTENSTELLEN | |||
| .Lebensmittel | Lebensmittel | Total Lebensmittel und Getränke | |
| .Getränke | Getränke | Total Lebensmittel und Getränke | |
| Total Lebensmittel und Getränke | Total Lebensmittel und Getränke |
含外汇的公司复式记账模板
在此文中
含外汇的公司复式记账模板
含外汇的公司复式记账模板
轻松地、免费地开始您含外汇的公司复式记账,并立即获得损益表和资产负债表。可以根据您的具体需要对这个现成的模板进行编辑,用来管理您的公司、独资企业、合伙企业或中小型企业的会计。Banana财务会+ 是一个专业的软件,由于它类似于Excel,所以使用起来非常直观和快速。如果在做账中出现了错误,也可以随时纠正,直到获得完美的会计报表。
直接在网页中打开Banana财务会计+
无需任何安装,可以直接在您的浏览器上运行 Banana财务会计+。客制化您的模板,输入发生业务并将文件保存在您的电脑上。
在浏览器中打开模板 Open tutorial in WebApp模板预览
XX 公司
本位币: USD
复式记账含外汇
| 总组 | 账号 | 摘要 | 货币 | 总和 |
|---|---|---|---|---|
| 资产负债表 | ||||
| 资产 | ||||
| 银行账户 | ||||
| 商业账户 USD | 美元商业账户 (USD) | USD | 银行 | |
| 商业账户 EUR | 欧元商业账户 (EUR) | EUR | 银行 | |
| 商业账户 GBP | 英镑商业账户 (GBP) | GBP | 银行 | |
| 商业存储账户 | 商业存储账户 | USD | 银行 | |
| 工资账户 | 工资账户 | USD | 银行 | |
| 现金 | 小额现金 - 自付費用 | USD | 银行 | |
| 易货贸易 | 易货贸易账户 | USD | 银行 | |
| 银行 | 银行账户总计 | 资产 | ||
| 应收账款 | ||||
| 客户 | 应收账款 (客户登记) | 应收 | ||
| 应收 | 应收账款总计 | 资产 | ||
| 流动资产 | ||||
| 库存 | 库存 | USD | 流动资产 | |
| 未存入的资金 | 未存入的资金 | USD | 流动资产 | |
| 流动资产 | 流动资产总计 | 资产 | ||
| 固定资产 | ||||
| 设备 | 设备 | USD | 固定 | |
| 家具 | 家具和固定装置 | USD | 固定 | |
| 车辆 | 车辆 | USD | 固定 | |
| 累计折旧 | 累计折旧 | USD | 固定 | |
| 固定 | 固定资产总计 | 资产 | ||
| 其它资产 | ||||
| 启动 | 启动成本 (会计人员使用) | USD | 其它 | |
| 摊销 | 累计摊销 | USD | 其它 | |
| 应收票据1 | 应收票据1 (高级职员、所有者、关联方) | USD | 其它 | |
| 应收票据2 | 应收票据2 | USD | 其它 | |
| 其它 | 其它资产总计 | 资产 | ||
| 资产 | 总资产 | 00 | ||
| 负债 | ||||
| 应付账款 | ||||
| 供应商 | 供应商登记 | 应付 | ||
| 应付 | 应付账款总计 | 负债 | ||
| 用于采购的信用卡 | ||||
| 美国运通 | 美国运通 - 信用卡贷款 | USD | 信用卡 | |
| Visa | Visa - 信用卡贷款 | USD | 信用卡 | |
| 信用卡 | 信用卡总计 | 负债 | ||
| 流动负债 | ||||
| 应计 | 应计费用 | USD | 流动负债 | |
| 应付薪资税 | 应付薪资税 | USD | 流动负债 | |
| 应付营业税 | 应付营业税 | USD | 流动负债 | |
| 押金 | 客户押金 | USD | 流动负债 | |
| 长期部分 | 长期负债的流动部分 | USD | 流动负债 | |
| 流动负债 | 流动负债总计 | 负债 | ||
| 长期负债 | ||||
| 银行贷款 | 银行贷款 | USD | 长期负债 | |
| 应付票据1 | 应付票据1 | USD | 长期负债 | |
| 应付票据2 | 应付票据2 | USD | 长期负债 | |
| 长期负债 | 长期负债总计 | 负债 | ||
| 负债 | 总负债 | 00 | ||
| 股权 | ||||
| 资本 | 股本/资本合伙人 | USD | 股权 | |
| 附加资本 | 额外出资/额外支付资本 | USD | 股权 | |
| 留存收益 | 留存收益 | USD | 股权 | |
| 期初权益 | 期初余额权益 | USD | 股权 | |
| 股东1 | 分配股东 1 / 股息 / 提款 | USD | 股权 | |
| 结转 | 结转盈亏 | USD | 股权 | |
| 盈利或亏损 | 本年度损益 | USD | 股权 | |
| 股权 | 股权总计 | 00 | ||
| 损益表 | ||||
| 收入 | ||||
| 服务 | 服务收入 | USD | 收入 | |
| 售出的产品 | 零件/产品销售收入 | USD | 收入 | |
| 销售冲销 | 销售冲销 | USD | 收入 | |
| 收入 | 总收入 | 毛利润 | ||
| 销货成本 | ||||
| 材料费 | 材料、直接产品/服务成本 | USD | 销货成本 | |
| 人工费 | 人工成本 | USD | 销货成本 | |
| 外部服务 | 外部服务/分包商 | USD | 销货成本 | |
| 供应品 | 耗材成本 | USD | 销货成本 | |
| 小型工具 | 小型工具 | USD | 销货成本 | |
| 销货成本 | 销货成本总计 | 毛利润 | ||
| 毛利润 | 毛利润 | 息税前利润 | ||
| 费用 | ||||
| 广告 | 广告、促销、营销费用 | USD | 费用 | |
| 汽车 | 汽车费用 | USD | 费用 | |
| 银行收费 | 银行服务费 | USD | 费用 | |
| 清洁费 | 清洁费 | USD | 费用 | |
| 捐款 | 捐款 | USD | 费用 | |
| 折旧 | 折旧费用 | USD | 费用 | |
| 折扣 | 采取的折扣 | USD | 费用 | |
| 订阅费 | 捐款和订阅费 | USD | 费用 | |
| 保险费 | 汽车保险、人寿、医疗 | USD | 费用 | |
| 利息支出 | 利息支出 | USD | 费用 | |
| 许可证 | 商业执照和许可证 | USD | 费用 | |
| 维修费 | 维护和修理 | USD | 费用 | |
| 餐费 | 膳食和娱乐 | USD | 费用 | |
| 商户费用 | 商家信用卡费用 | USD | 费用 | |
| 办公室 | 办公费用(电脑、邮资、快递、用品)。 | USD | 费用 | |
| 薪资税 | 薪资税 | USD | 费用 | |
| 专业费用 | 专业费用 | USD | 费用 | |
| 租金 | 租金支付 | USD | 费用 | |
| 工资 | 工资 | USD | 费用 | |
| 电话费 | 电话、传真 | USD | 费用 | |
| 旅行 | 旅行 | USD | 费用 | |
| 公用事业 | 公用事业 | USD | 费用 | |
| 费用 | 总费用 | 息税前利润 | ||
| 息税前利润 | 息税前利润 | 结果 | ||
| 其它收入 | ||||
| 利息收入 | 利息收入 | USD | 其它收入 | |
| 外汇利润 | 外汇利润 | USD | 其它收入 | |
| 其它收入 | 其它收入总计 | 结果 | ||
| 其它费用 | ||||
| 会计师咨询 | 会计师咨询 | USD | 其它费用 | |
| 外汇损失 | 外汇损失 | USD | 其它费用 | |
| 其它费用 | 其它费用总计 | 结果 | ||
| 结果 | 净利 (盈利(-) 亏损(+) ) | 盈利或亏损 | ||
| 00 | 差额应该是=0(空白单元格) | |||
| 客户/供应商登记 | ||||
| 客户 | ||||
| 客户-Redford | Redford 公司 | USD | 客户总计 | |
| 客户-Smith | John Smith | USD | 客户总计 | |
| 客户-Black | Simon Black | GBP | 客户总计 | |
| 客户总计 | 客户总计 | 客户 | ||
| 供应商 | ||||
| 供应商-Johnson | Johnson 公司 | EUR | 供应商总计 | |
| 供应商-Marble | Marble | USD | 供应商总计 | |
| 供应商-Taylor | Mary Taylor | USD | 供应商总计 | |
| 供应商总计 | 供应商总计 | 供应商 | ||
| 成本中心 | ||||
| 产品 | ||||
| .产品 A | 产品 A | USD | 产品 | |
| .产品 B | 产品 B | USD | 产品 | |
| .产品 C | 产品 C | USD | 产品 | |
| 产品 | 产品总计 | |||
| 项目 | ||||
| ;项目 A | 项目 A | USD | 项目 | |
| ;项目 B | 项目 B | USD | 项目 | |
| 项目 | 项目总计 | |||
| 部门 | ||||
| 分公司 | ||||
| :分公司 A | 分公司 A | USD | 分公司 | |
| :分公司 B | 分公司 B | USD | 分公司 | |
| 分公司 | 分公司总计 | |||
| 记账本位币 | 货币 | 文字 |
|---|---|---|
| USD | EUR | 欧元 |
| USD | GBP | 英镑 |
PayPal Templates | Double-entry
在此文中
PayPal Templates | Double-entry
PayPal Templates | Double-entry
Double-entry template files predefined for importing PayPal transactions.
直接在网页中打开Banana财务会计+
无需任何安装,可以直接在您的浏览器上运行 Banana财务会计+。客制化您的模板,输入发生业务并将文件保存在您的电脑上。
在浏览器中打开模板 Open tutorial in WebApp模板文件
PayPal import transaction
Banana has an import filter that allows you to directly import the PayPal transactions data in your accounting file.
The attached files are predefined with the accounts so that you can start immediately using it.
There are two template example files you can download and open in Banana:
Files suitable for
These template files are especially suitable in case you have only one PayPal preferred currency.
The imported transactions will automatically be imported to the currency account, so that you can separately see all transactions.
If in PayPal you keep balances in different currencies, it will be more suitable to use a PayPal accounting in Multicurrency.
Even if you use another accounting software, you will find that is very efficient to keep a separate accounting in Banana and keep your PayPal accounting in it. Instead of recording all transactions in your accounting solution, you can keep a separated accounting in Banana and once a month or when needed, only record the summary movement for the period in your accounting solution .
Further adapting the file
The file can easily be adapted to suit your needs.
Adding new accounts and new currencies
-
In the Accounts table, add new accounts for other currencies or for different Income or Expense types.
Changing to another Basic currency
This file can easily be converted into one with another Basic currency.
- Change the Basic currency in the File properties.
Add VAT/Sales Tax, change language or convert into another type
Use Convert to new file to add more options or change the accounting file settings.
模板预览
Company XX
Accounting 2016
Basic Currency: EUR
Double-entry
| Group | Account | Description | Sum In | Gr1 |
|---|---|---|---|---|
| BALANCE SHEET | ||||
| ASSETS | ||||
| 1000 | Paypal Account EUR | 1 | ||
| 1001 | Paypal Account USD | 1 | ||
| 1002 | Paypal Account CHF | 1 | ||
| 1003 | Paypal Account GBP | 1 | ||
| 1004 | Paypal Account YPY | 1 | ||
| 1005 | Paypal Account CAD | 1 | ||
| 1006 | Paypal Account ... | 1 | ||
| 1500 | Bank Account (internal transfer) | 1 | ||
| 1 | TOTAL ASSETS | 00 | 1 | |
| LIABILITIES | ||||
| 2300 | Profit or loss brought forward | 2 | ||
| 230 | Profit or loss of the current year | 2 | 1 | |
| 2 | TOTAL LIABILITIES | 00 | 1 | |
| 1 | ||||
| PROFIT/LOSS STATEMENT | ||||
| EXPENSES | ||||
| 3000 | Paypal Out | 3 | ||
| 3001 | Paypal Fee | 3 | ||
| 3002 | Other ... | 3 | ||
| 3100 | Exchange rate loss | 3 | ||
| 3 | TOTAL EXPENSES | 02 | 1 | |
| REVENUE | ||||
| 4000 | Paypal In | 4 | ||
| 4100 | Exchange rate profit | 4 | ||
| 4 | TOTAL REVENUE | 02 | 1 | |
| 02 | Profit(-) Loss(+) from Profit & Loss Statement | 230 | 1 | |
| 00 | Difference should be = 0 (blank cell) | |||
| COST AND PROFIT CENTERS | ||||
| Division | ||||
| .D1 | Division 1 | CD | ||
| .D2 | Division 2 | CD | ||
| .D3 | Division 3 | CD | ||
| CD | Total Division | 1 | ||
| Projects | ||||
| ,P1 | Project 1 | CP | ||
| ,P2 | Project 2 | CP | ||
| ,P3 | Project 4 | CP | ||
| CP | Total Division car expenses |
Contabilità Ristorante (Multi-Moneta)
在此文中
Contabilità Ristorante (Multi-Moneta)
Contabilità Ristorante (Multi-Moneta)
Modello ideale per gestire la contabilità di un ristorante, un bar, una pizzeria o un take-away, anche con conti in moneta estera.
直接在网页中打开Banana财务会计+
无需任何安装,可以直接在您的浏览器上运行 Banana财务会计+。客制化您的模板,输入发生业务并将文件保存在您的电脑上。
在浏览器中打开模板 Open tutorial in WebApp模板文件
Come fare il preventivo per un ristorante
Segui passo per passo la nostra guida alla pagina Come fare il preventivo per un ristorante che ti insegna come creare e gestire un budget familiare.
模板预览
Ristorante
Contabilità 2022
Divisa Base: EUR
Contabilità in partita doppia multi-moneta
| Gruppo | Conto | Descrizione | Moneta | Somma in | Gr1 |
|---|---|---|---|---|---|
| BILANCIO | |||||
| Attivi | |||||
| Cassa | Cassa | EUR | A | ||
| Banca Euro | Conto corrente bancario Euro | EUR | A | ||
| Banca Dollari | Conto corrente bancario Dollari | USD | A | ||
| Trasferimenti interni | Trasferimenti interni | EUR | A | ||
| Clienti | Conto clienti | EUR | A | ||
| Immobili | Immobili | EUR | A | ||
| Attrezzatura cucina | Attrezzature cucina | EUR | A | ||
| Magazzino | Magazzino | EUR | A | ||
| A | Totale Attivi | 00 | 1 | ||
| Passivi | |||||
| Prestiti | Prestito | EUR | P | ||
| Fornitori | Fornitori | EUR | P | ||
| Capitale | Capitale proprio | EUR | P | ||
| Utile Perdita riportati | Utile / Perdita riportato/a | EUR | P | ||
| UP | Utile / Perdita dell'anno | EUR | P | 1 | |
| P | Totale Passivi | 00 | |||
| CONTO ECONOMICO | |||||
| Ricavi | |||||
| Vendite | Ricavi da vendite | EUR | R | ||
| Ricavi merce | Ricavi da vendita di merce | EUR | R | ||
| Ricavi interessi | Ricavi da interessi | EUR | R | ||
| R | Totale Ricavi | 0 | |||
| Costi | |||||
| Acquisti cibo | Spese per cibo e bevande | EUR | CM | ||
| Acquisti merce | Acquisti Merce | EUR | CM | ||
| CM | Totale costo della merce acquistata | Variabili | |||
| Salari | Spese personale | EUR | CP | ||
| Tasse e prestazioni | Tasse e prestazioni | EUR | CP | ||
| Assicurazione personale | Assicurazione personale | EUR | CP | ||
| CP | Totale Costi Stipendi | Variabili | |||
| Variabili | Totale Costi Variabili | Costi | |||
| Pulizia | Pulizia | EUR | COD | ||
| Cellulari | Cellulari | EUR | COD | ||
| Tasse carte di credito | Tasse carte di credito | EUR | COD | ||
| COD | Totale Costi Operativi Diretti | Costi | |||
| Pubblicità | Vendite e marketing | EUR | CO | ||
| Sconti | Sconti | EUR | CO | ||
| Acqua e elettricità | Acqua e elettricità | EUR | CO | ||
| Gas naturale | Gas naturale | EUR | CO | ||
| Legna | Legna | EUR | CO | ||
| Manutenzione | Riparazione e manutenzione | EUR | CO | ||
| CO | Totale Costi Operativi | Costi | |||
| Affitto | Affitto | EUR | COC | ||
| Tasse immobile | Tasse immobile | EUR | COC | ||
| Manutenzione immobile | Manutenzione immobile | EUR | COC | ||
| Assicurazione immobile | Assicurazione immobile | EUR | COC | ||
| COC | Totale Costi Occupazione | EUR | Costi | ||
| Assicurazione passiva | Assicurazione passiva | EUR | CF | ||
| Indennizzo lavoratori | Indennizzo lavoratori | EUR | CF | ||
| Telefono e Internet | Telefono e Internet | EUR | CF | ||
| TV | TV satellitare | EUR | CF | ||
| Licenze e permessi | Licenze e permessi | EUR | CF | ||
| Ammanco | Ammanco | EUR | CF | ||
| IT | Servizio IT | EUR | CF | ||
| Tasse avviso | Tasse avviso | EUR | CF | ||
| Disinfestazione | Disinfestazione | EUR | CF | ||
| Servizio rifiuti | Servizio rifiuti | EUR | CF | ||
| Servizio sanitario | Servizio sanitario | EUR | CF | ||
| Materiale ufficio | Materiale ufficio | EUR | CF | ||
| Tasse bancarie | Tasse bancarie | EUR | CF | ||
| Tasse amministrative | Tasse amministrative | EUR | CF | ||
| Tasse legali | Tasse legali | EUR | CF | ||
| Dipartimento Sanità | Cosultazione Dipartimento Sanità | EUR | CF | ||
| Diversi | Costi diversi | EUR | CF | ||
| Perdite cambio | Perdite sul cambio | EUR | CF | ||
| Utili cambio | Utili sul cambio | EUR | CF | ||
| CF | Totale Costi Fissi | Costi | |||
| Costi | Totale Costi | 0 | |||
| 0 | Utile (-) Perdita (+) da Conto Economico | UP | |||
| 00 | Differenza deve essere zero | ||||
| CENTRI DI COSTO | |||||
| .Cibo | Cibo | EUR | CB | ||
| .Bevande | Bevande | EUR | CB | ||
| CB | Totale Cibo e Bevande | ||||
| Moneta Rif. | Moneta | Testo |
|---|---|---|
| EUR | USD | Dollari USA |
| EUR | CHF | Franchi svizzeri |
PayPal Templates | Multi-currency accounting
在此文中
PayPal Templates | Multi-currency accounting
PayPal Templates | Multi-currency accounting
Multi-currency accounting files predefined for importing PayPal transactions.
模板文件
PayPal import transactions
Banana has an import filter that allows you to directly import the PayPal transaction data into your accounting files.
The attached files are predefined with the accounts so that you can immediately start using it.
There are two template example files that you can download and open in Banana:
- Multi currency accounting with EUR as a Basic Currency
- Multi currency accounting with USD as a Basic Currency
Files suitable for
These example files are especially suitable in case you have PayPal transactions in different currencies and especially if you have set up your PayPal account to use and keep different currencies (see also PayPal template for Double-entry accounting) .
The imported transactions will automatically be imported to the currency account, so that you can see all transactions separately and have a balance in the currency.
Even if you use another accounting software, you will find that is very efficient to keep a separate accounting in Banana and keep your PayPal accounting in it. Instead of recording all transctions in your accounting solution, you can keep a separated accounting in Banana and once a month or when needed, only record the summary movement for the period in your accounting solution .
Further adapting the file
The file can easily be adapted to suit your needs.
Adding new accounts and new currencies
-
In the Accounts table, add new accounts for other currencies or for different Income or Expense types.
-
Add new currencies in the Exchange rates Table
Changing to another basic currency
This file can easily be converted into one with another Basic Currency
- Change the Basic currency in the Accounting properties.
- Adapt the Exchange Rates table with the appropriate currencies and exchange rates.
- In the Accounts table, change the currency for the accounts that need to be in Basic currency.
Add VAT/Sales Tax, change language or convert into another type
Use the Convert to new file command to add more options or change the accounting file settings.
模板预览
Company XX
Accounting 2022
Basic Currency: EUR
Double-entry
| Group | Account | Description | Sum In | Gr1 |
|---|---|---|---|---|
| BALANCE SHEET | ||||
| ASSETS | ||||
| Paypal EUR | Paypal Account EUR | Total Assets | ||
| Paypal USD | Paypal Account USD | Total Assets | ||
| Paypal CHF | Paypal Account CHF | Total Assets | ||
| Paypal GBP | Paypal Account GBP | Total Assets | ||
| Paypal YEN | Paypal Account YEN | Total Assets | ||
| Paypal CAD | Paypal Account CAD | Total Assets | ||
| Paypal Account | Paypal Account ... | Total Assets | ||
| Bank Account | Bank Account (internal transfer) | Total Assets | ||
| Total Assets | TOTAL ASSETS | 00 | 1 | |
| LIABILITIES | ||||
| Profit or loss brought forward | Profit or loss brought forward | Total Liabilities | ||
| 230 | Profit or loss of the current year | Total Liabilities | 1 | |
| Total Liabilities | TOTAL LIABILITIES | 00 | 1 | |
| 1 | ||||
| PROFIT/LOSS STATEMENT | ||||
| EXPENSES | ||||
| Paypal Out | Paypal Out | Total Expenses | ||
| Paypal Fee | Paypal Fee | Total Expenses | ||
| Other | Other | Total Expenses | ||
| Exchange rate loss | Exchange rate loss | Total Expenses | ||
| Total Expenses | TOTAL EXPENSES | Profit(-) Loss(+) from Profit & Loss Statement | 1 | |
| REVENUE | ||||
| Paypal In | Paypal In | Total Revenue | ||
| Exchange rate profit | Exchange rate profit | Total Revenue | ||
| Total Revenue | TOTAL REVENUE | Profit(-) Loss(+) from Profit & Loss Statement | 1 | |
| Profit(-) Loss(+) from Profit & Loss Statement | Profit(-) Loss(+) from Profit & Loss Statement | 230 | 1 | |
| 00 | Difference should be = 0 (blank cell) | |||
| COST AND PROFIT CENTERS | ||||
| Division | ||||
| .D1 | Division 1 | CD | ||
| .D2 | Division 2 | CD | ||
| .D3 | Division 3 | CD | ||
| CD | Total Division | 1 | ||
| Projects | ||||
| ,P1 | Project 1 | CP | ||
| ,P2 | Project 2 | CP | ||
| ,P3 | Project 4 | CP | ||
| CP | Total Division car expenses |
含增值税的商业会计模板
商店会计
在此文中
商店会计
商店会计
使用现金账簿记账方法来完美管理商店或店铺的通用会计模板,并包括增值税管理。
直接在网页中打开Banana财务会计+
无需任何安装,可以直接在您的浏览器上运行 Banana财务会计+。客制化您的模板,输入发生业务并将文件保存在您的电脑上。
在浏览器中打开模板 Open tutorial in WebApp模板预览
XX商店
本位币: USD
现金日记账含增值税
| 总组 | 账号 | 摘要 | 总和 |
|---|---|---|---|
| 现金 | 现金 | ||
| 总组 | 科目 | 摘要 | 总和 |
|---|---|---|---|
| 经营业绩 | |||
| 收入 | |||
| 销售收入 | 销售收入 | 收入 | |
| 从往来账户提款 | 从往来账户提款 | 收入 | |
| 服务收入 | 服务收入 | 收入 | |
| 其他收入 | 其他收入 | 收入 | |
| 收入 | 总收入 | 业绩 | |
| 费用 | |||
| 转账到邮政储蓄账户 | 转账到邮政储蓄账户 | 费用 | |
| 购买邮票 | 购买邮票 | 费用 | |
| 信件和包裹 | 信件和包裹 | 费用 | |
| 邮递物品 | 邮递物品 | 费用 | |
| 文具,电器,清洁 | 文具,电器,清洁 | 费用 | |
| 租金,电费,水费 | 租金,电费,水费 | 费用 | |
| 电话和传真费 | 电话和传真费 | 费用 | |
| 房地产维护 | 房地产维护 | 费用 | |
| 橱窗装饰 | 橱窗装饰 | 费用 | |
| 宣传,传单 | 宣传,传单 | 费用 | |
| 中介费 | 中介费 | 费用 | |
| 货款 | 货款 | 费用 | |
| 薪资及个人贷款 | 薪资及个人贷款 | 费用 | |
| 其他许可证费用 | 其他许可证费用 | 费用 | |
| 自动核算增值税 | 自动核算增值税 | 费用 | |
| 应交增值税 | 应交增值税 | 费用 | |
| 费用 | 总费用 | 业绩 | |
| 业绩 | 总业绩 | ||
| 成本和利润中心 | |||
| .人事管理 | 店铺及人事管理 | 部门 | |
| .货物管理 | 货物管理 | 部门 | |
| .投资管理 | 投资管理 | 部门 | |
| 部门 | 总部门 | ||
| 增值税码 | 摘要 | %税率 |
|---|---|---|
| 应交增值税 | ||
| S0 | 免征增值税销售 | |
| SE | 国外销售免税 | |
| S10 | 销售 10% | 10.00 |
| SD10 | 销售折扣 10% | 10.00 |
| 应交增值税 | ||
| 增值税进项税 | ||
| 购买商品和服务 | ||
| P10 | 购买商品和服务 10% | 10.00 |
| PD10 | 购买商品和服务折扣 10% | 10.00 |
| P5 | 购买商品和服务折扣 5% | 5.00 |
| PD5 | 商品和服务折扣 5% | 5.00 |
| 营运和投资成本 | ||
| I10 | 投资和营运成本 10% | 10.00 |
| ID10 | 投资和营运成本折扣 10% | 10.00 |
| I5 | 投资和营运成本 5% | 5.00 |
| ID5 | 投资和营运成本折扣 5% | 5.00 |
| 增值税进项税 | ||
| 总计 | ||
Comptabilité multidevise pour PME
在此文中
Comptabilité multidevise pour PME
Comptabilité multidevise pour PME
Modèle idéal pour la gestion de la comptabilité des sociétés anonymes. Le plan comptable est structuré selon le schéma PME et présente les registres clients/fournisseurs. Il y a des comptes en devises étrangères et des centres de coûts.
模板文件
Modèle idéal pour la gestion de la comptabilité des sociétés anonymes. Le plan comptable est structuré selon le schéma PME et présente les registres clients/fournisseurs. Il y a des comptes en devises étrangères et des centres de coûts.
模板预览
DeviseBase: EUR
Comptabilité en partie double avec multidevise et TVA
| Groupe | Compte | Libellé | Devise | Add. dans |
|---|---|---|---|---|
| BILAN | ||||
| ACTIFS | ||||
| 1000 | Caisse | EUR | 100 | |
| 1020 | Banque | EUR | 100 | |
| 1024 | Banque CHF | CHF | 100 | |
| 1025 | Banque USD | USD | 100 | |
| 100 | Liquidités | 10 | ||
| 1060 | Titres | EUR | 106 | |
| 106 | Avoirs à court terme cotés en bourse | 10 | ||
| 1090 | Compte d'attente en monnaie | EUR | 109 | |
| 1091 | Compte d'attente salaires | EUR | 109 | |
| 1099 | Compte de passage pour éclaircissements | EUR | 109 | |
| 109 | Comptes de transit et d’attente | 10 | ||
| 1100 | Créances provenant de livraisons et de prestations (Débiteurs) | EUR | 110 | |
| 1109 | Ducroire | EUR | 110 | |
| 100A | Clients | 110 | ||
| 110 | Créances résultant de livraisons et prestations | 10 | ||
| 1140 | Avances et prêts | EUR | 114 | |
| 1176 | Impôt anticipé | EUR | 114 | |
| 1180 | Créances envers les assurances sociales et institutions de prévoyance | EUR | 114 | |
| 1188 | Impôt à la source | EUR | 114 | |
| 1190 | Autres créances à court terme | EUR | 114 | |
| 1191 | Cautionnements en espèces | EUR | 114 | |
| 114 | Autres créances à court terme | 10 | ||
| 1200 | Marchandises commerciales | EUR | 120 | |
| 1210 | Matières premières | EUR | 120 | |
| 1220 | Matières auxiliaires | EUR | 120 | |
| 1230 | Matières consommables | EUR | 120 | |
| 1260 | Stocks de produits finis | EUR | 120 | |
| 1270 | Stocks de produits pas finis | EUR | 120 | |
| 1280 | Travaux en cours | EUR | 120 | |
| 120 | Stocks et prestations non facturées | 10 | ||
| 1300 | Charges payées d‘avance | EUR | 130 | |
| 1301 | Produits à recevoir | EUR | 130 | |
| 130 | Compte de régularisation de l’actif | 10 | ||
| 10 | Actifs circulants | 1 | ||
| 1400 | Titres à long terme | EUR | 140 | |
| 1440 | Prêts | EUR | 140 | |
| 1441 | Hypothèques | EUR | 140 | |
| 1460 | Prêt à actionnaire | EUR | 140 | |
| 140 | Immobilisations financières | 14 | ||
| 1480 | Participations | EUR | 148 | |
| 148 | Participations | 14 | ||
| 1500 | Machines et appareils | EUR | 150 | |
| 1510 | Mobilier et installations | EUR | 150 | |
| 1520 | Machines de bureau, informatique, systèmes de communication | EUR | 150 | |
| 1530 | Véhicules | EUR | 150 | |
| 1540 | Outillages et appareils | EUR | 150 | |
| 150 | Immobilisations corporelles meubles | 14 | ||
| 1600 | Immeubles d’exploitation | EUR | 160 | |
| 160 | Immobilisations corporelles immeubles | 14 | ||
| 1700 | Brevets, know-how, licences, droits, développement | EUR | 170 | |
| 1710 | Marques commerciales | EUR | 170 | |
| 1712 | Modèles | EUR | 170 | |
| 1770 | Goodwill | EUR | 170 | |
| 170 | Immobilisations incorporelles | 14 | ||
| 1850 | Capital actions, capital social, droits de participations ou capital de fondation non versés | EUR | 180 | |
| 180 | Capital non versé : capital social, capital de fondation | 14 | ||
| 14 | Actifs immobilisés | 1 | ||
| 1 | Total actifs | 00 | ||
| PASSIFS | ||||
| 2000 | Dettes résultant d’achats et de prestation de services (créanciers) | EUR | 200 | |
| 2030 | Acomptes de clients | EUR | 200 | |
| 200A | Créanciers | 200 | ||
| 200 | Dettes à court terme résultant d’achats et de prestations de services | 20 | ||
| 2100 | Dettes bancaires | EUR | 210 | |
| 2120 | Engagements de financement par leasing | EUR | 210 | |
| 2140 | Autres dettes à court terme rémunérées | EUR | 210 | |
| 210 | Dettes à court terme rémunérés | 20 | ||
| 2200 | TVA due | EUR | 220 | |
| 2201 | Décompte TVA | EUR | 220 | |
| 2206 | Impôt anticipé dû | EUR | 220 | |
| 2208 | Impôts directs | EUR | 220 | |
| 2210 | Autres dettes à court terme | EUR | 220 | |
| 2260 | Dettes envers actionnaire | EUR | 220 | |
| 2261 | Dividendes | EUR | 220 | |
| 2270 | Assurances sociales et institutions de prévoyance | EUR | 220 | |
| 2279 | Impôt à la source | EUR | 220 | |
| 220 | Autres dettes à court terme | 20 | ||
| 2300 | Charges à payer | EUR | 230 | |
| 2301 | Produits encaissés d’avance | EUR | 230 | |
| 2330 | Provisions à court terme | EUR | 230 | |
| 230 | Passifs de régularisation et provisions à court terme | 20 | ||
| 20 | Dettes à court terme | 2A | ||
| 2400 | Dettes bancaires | EUR | 240 | |
| 2420 | Engagements de financement par leasing | EUR | 240 | |
| 2430 | Emprunts obligataires | EUR | 240 | |
| 2450 | Emprunts | EUR | 240 | |
| 2451 | Hypothèques | EUR | 240 | |
| 240 | Dettes à long terme rémunérées | 24 | ||
| 2500 | Autres dettes à long terme | EUR | 250 | |
| 250 | Autres dettes à long terme | 24 | ||
| 2600 | Provisions | EUR | 260 | |
| 260 | Provisions à long termes et provisions légales | 24 | ||
| 24 | Dettes à long terme | 2A | ||
| 2A | Fonds étrangers | 2 | ||
| 2800 | Capital-actions, capital social, capital de fondation | EUR | 280 | |
| 280 | Capital social ou capital de fondation | 28 | ||
| 2900 | Réserves légales issues du capital | EUR | 290 | |
| 2940 | Réserves d‘évaluation | EUR | 290 | |
| 290 | Réserves légales issues du capital | 28 | ||
| 2950 | Réserves légales issues du bénéfice | EUR | 295 | |
| 295 | Réserves légales issues du bénéfice | 28 | ||
| 2960 | Réserves libres | EUR | 296 | |
| 296 | Réserves libres | 28 | ||
| 2970 | Bénéfice / perte reporté | EUR | 297 | |
| 29A | Bénéfice / perte de l’exercice | 297 | ||
| 297 | Bénéfice / perte du bilan | 28 | ||
| 2980 | Propres actions, parts sociales, droits de participations (poste négatif) | EUR | 298 | |
| 298 | Propres actions, parts sociales, droits de participations (poste négatif) | 28 | ||
| 28 | Fonds propres | 2 | ||
| 2 | Total passifs | 00 | ||
| COMPTE DE PERTES ET PROFITS | ||||
| 3000 | Ventes de produits fabriqués | EUR | 30 | |
| 3200 | Ventes de marchandises | EUR | 30 | |
| 3400 | Ventes de prestations | EUR | 30 | |
| 3600 | Autres ventes et prestations de services | EUR | 30 | |
| 3700 | Prestations propres | EUR | 30 | |
| 3710 | Consommations propres | EUR | 30 | |
| 3800 | Déductions sur ventes | EUR | 30 | |
| 3805 | Pertes sur clients, variation du ducroire | EUR | 30 | |
| 3809 | TVA taux de la dette fiscale nette | EUR | 30 | |
| 30 | Chiffre d'affaires net résultant des ventes et prestations de services | 3 | ||
| 3900 | Variation des stocks de produits semi-finis | EUR | 39 | |
| 3901 | Variation des stocks de produits finis | EUR | 39 | |
| 3940 | Variation de la valeur des prestations non facturées | EUR | 39 | |
| 39 | Variation des travaux en cours et des prestations non facturées | 3 | ||
| 3 | Produit net des ventes et des prestations de service | E1 | ||
| 4000 | Charges de matériel de l'atelier | EUR | 4 | |
| 4200 | Achats de marchandises destinées à la revente | EUR | 4 | |
| 4400 | Prestations / travaux de tiers | EUR | 4 | |
| 4500 | Charges d'énergie pour l'exploitation | EUR | 4 | |
| 4900 | Déductions sur les charges | EUR | 4 | |
| 4 | Charges de matériel, de marchandises et de prestations de tiers | E1 | ||
| E1 | Résultat brut d'exploitation | E2 | ||
| 5000 | Salaires | EUR | 5 | |
| 5700 | AVS, AI, APG, assurance-chômage | EUR | 5 | |
| 5710 | Caisse de compensation familiale | EUR | 5 | |
| 5720 | Prévoyance professionnelle | EUR | 5 | |
| 5730 | Assurance-accidents | EUR | 5 | |
| 5740 | Assurance pour indemnités maladie | EUR | 5 | |
| 5790 | Impôts à la source | EUR | 5 | |
| 5800 | Autres charges du personnel | EUR | 5 | |
| 5810 | Formation | EUR | 5 | |
| 5820 | Frais de voyage | EUR | 5 | |
| 5830 | Indemnités forfaitaires | EUR | 5 | |
| 5900 | Charges de personnel temporaire | EUR | 5 | |
| 5 | Charges de personnel | E2 | ||
| E2 | Résultat brut d'exploitation après charges de personnel | E3 | ||
| 6000 | Charges de locaux | EUR | 60 | |
| 6040 | Nettoyage locaux | EUR | 60 | |
| 60 | Charges de locaux | 6 | ||
| 6100 | Entretien, réparations et remplacement des inst. servant à l'exploitation | EUR | 61 | |
| 6105 | Leasing immobilisations corporelles meubles | EUR | 61 | |
| 61 | Entretien, réparations et remplacement des inst. servant à l'exploitation | 6 | ||
| 6200 | Réparations | EUR | 62 | |
| 6210 | Carburant | EUR | 62 | |
| 6220 | Assurances voitures | EUR | 62 | |
| 6260 | Leasing et location de véhicules | EUR | 62 | |
| 6270 | Charges de véhicules comme prélèvements à titre privé | EUR | 62 | |
| 6282 | Charges de transport | EUR | 62 | |
| 62 | Charges de véhicules et de transport | 6 | ||
| 6300 | Assurances-choses, droits, taxes, autorisations | EUR | 63 | |
| 63 | Assurances-choses | 6 | ||
| 6402 | Électricité | EUR | 64 | |
| 6410 | Chauffage | EUR | 64 | |
| 6430 | Eau | EUR | 64 | |
| 6460 | Évacuation des déchets | EUR | 64 | |
| 64 | Charges d'énergie et évacuation des déchets | 6 | ||
| 6500 | Matériel de bureau | EUR | 65 | |
| 6503 | Littérature technique, journaux, revues | EUR | 65 | |
| 6510 | Téléphone, Internet | EUR | 65 | |
| 6511 | Services d'hosting | EUR | 65 | |
| 6513 | Frais postaux | EUR | 65 | |
| 6570 | Charges et leasing d'informatique | EUR | 65 | |
| 6580 | Licences, updates | EUR | 65 | |
| 6583 | Consommables | EUR | 65 | |
| 65 | Charges d'administration et d'informatique | 6 | ||
| 6600 | Publicité | EUR | 66 | |
| 6642 | Cadeaux à la clientèle | EUR | 66 | |
| 66 | Publicité | 6 | ||
| 6700 | Autres charges d'exploitation | EUR | 67 | |
| 67 | Autres charges d'exploitation | 6 | ||
| 6 | Charges divers d'exploitation | E3 | ||
| E3 | Résultat d'exploitation avant intérêts, impôts et amortissements (EBITDA) | E4 | ||
| 6800 | Amortissement et ajustement de valeur des postes sur les actifs immobilisés | EUR | 68 | |
| 68 | Amortissement et ajustement de valeur des immobilitations | E4 | ||
| E4 | Résultat d'exploitation avant intérêts, impôts (EBIT) | E5 | ||
| 6900 | Charges pour intérêts bancaires | EUR | 69 | |
| 6940 | Frais bancaires | EUR | 69 | |
| 6949 | Perte de change | EUR | 69 | |
| 6950 | Intérêts actifs bancaires | EUR | 69 | |
| 6999 | Bénéfice de change | EUR | 69 | |
| 69 | Charges et produits financiers | E5 | ||
| E5 | Résultat d'exploitation avant impôts (EBT) | E6 | ||
| 7000 | Produits accessoires | EUR | 7 | |
| 7010 | Charges accessoires | EUR | 7 | |
| 7500 | Produits des immeubles d'exploitation | EUR | 7 | |
| 7510 | Charges des immeubles d'exploitation | EUR | 7 | |
| 7 | Résultat des activités annexes d'exploitation | E6 | ||
| 8000 | Charges hors exploitation | EUR | 8 | |
| 8100 | Produits hors exploitation | EUR | 8 | |
| 8500 | Charges extraordinaires, exceptionnelles ou hors période | EUR | 8 | |
| 8510 | Produits extraordinaires, exceptionnels ou hors période | EUR | 8 | |
| 8 | Résultats extraordinaires et hors exploitation | E6 | ||
| E6 | Résultat de l'exercice avant impôts | E7 | ||
| 8900 | Impôts directs | EUR | 89 | |
| 89 | Impôts directs | E7 | ||
| E7 | Résultat de l'exercice | 29A | ||
| 00 | Différence doit être = 0 (cellule vide) | |||
| Clients et Fournisseurs | ||||
| Clients | ||||
| 110001 | Société 1 | EUR | CLI | |
| 110002 | Société 2 | EUR | CLI | |
| 110003 | Société 3 | EUR | CLI | |
| CLI | Total client | 100A | ||
| Créanciers | ||||
| 200001 | Société 1 | EUR | CRE | |
| 200002 | Société 2 | EUR | CRE | |
| 200003 | Société 3 | EUR | CRE | |
| CRE | Total Créanciers | 200A | ||
| CENTRES DE COÛT | ||||
| .EMB | Emballages A | EUR | ST | |
| .MPR | Matières premières A | EUR | ST | |
| .MAU | Matières auxiliaires A | EUR | ST | |
| ST | Total Stock | |||
| ,ENT1 | Entretien1 | EUR | ENT | |
| ,ENT2 | Entretien 2 | EUR | ENT | |
| ,ENT3 | Entretien 3 | EUR | ENT | |
| ENT | Total frais d'entretien | |||
| ;PB1 | Publicité type 1 | EUR | PU | |
| ;PB2 | Publicité type 2 | EUR | PU | |
| PU | Totale charges de publicité | |||
| Cod. TVA | Libellé | %TVA |
|---|---|---|
| Dernière mise à jour: 26.11.2019 | ||
| Ventes | ||
| V0 | Ventes sans TVA | |
| VE | Ventes à l'étranger | |
| V20 | Ventes au 20.00% | 20.00 |
| V10 | Ventes au 10.00% | 10.00 |
| V5 | Ventes au 5.00% | 5.00 |
| V2 | Ventes au 2.00% | 2.00 |
| TOTAL TVA DUE | ||
| Achats | ||
| A20 | Achats au 20.00% | 20.00 |
| A10 | Achats au 10.00% | 10.00 |
| A5 | Achats au 5.00% | 5.00 |
| A2 | Achats au 2.00% | 2.00 |
| TOTAL TVA DEDUCTIBLE | ||
| TOTAL | ||
| Dev.Référence | Devise | Libellé |
|---|---|---|
| EUR | CHF | CHF |
| EUR | USD | US Dollar |
Comptabilité pour sociétés de personnes morales avec les registres clients/fournisseurs
在此文中
Comptabilité pour sociétés de personnes morales avec les registres clients/fournisseurs
Comptabilité pour sociétés de personnes morales avec les registres clients/fournisseurs
Modèle idéal pour la gestion de la comptabilité des sociétés de personnes morales. Le plan comptable est structuré avec des groupes et sousgroupes. Il y a des des centres de coûts pour avoir des détails.
模板文件
Modèle idéal pour la gestion de la comptabilité des sociétés anonymes. Le plan comptable est structuré conformément au régime des PME. Il y a des centres de coûts.
模板预览
DeviseBase: EUR
Comptabilité en partie double avec TVA
| Groupe | Compte | Libellé | Add. dans |
|---|---|---|---|
| BILAN | |||
| ACTIFS | |||
| 1000 | Caisse | 100 | |
| 1020 | Banque | 100 | |
| 100 | Liquidités | 10 | |
| 1060 | Titres | 106 | |
| 106 | Avoirs à court terme cotés en bourse | 10 | |
| 1090 | Compte d'attente en monnaie | 109 | |
| 1091 | Compte d'attente salaires | 109 | |
| 1099 | Compte de passage pour éclaircissements | 109 | |
| 109 | Comptes de transit et d’attente | 10 | |
| 1100 | Créances provenant de livraisons et de prestations (Débiteurs) | 110 | |
| 1109 | Ducroire | 110 | |
| 100A | Clients | 110 | |
| 110 | Créances résultant de livraisons et prestations | 10 | |
| 1140 | Avances et prêts | 114 | |
| 1176 | Impôt anticipé | 114 | |
| 1180 | Créances envers les assurances sociales et institutions de prévoyance | 114 | |
| 1188 | Impôt à la source | 114 | |
| 1190 | Autres créances à court terme | 114 | |
| 1191 | Cautionnements en espèces | 114 | |
| 114 | Autres créances à court terme | 10 | |
| 1200 | Marchandises commerciales | 120 | |
| 1210 | Matières premières | 120 | |
| 1220 | Matières auxiliaires | 120 | |
| 1230 | Matières consommables | 120 | |
| 1260 | Stocks de produits finis | 120 | |
| 1270 | Stocks de produits pas finis | 120 | |
| 1280 | Travaux en cours | 120 | |
| 120 | Stocks et prestations non facturées | 10 | |
| 1300 | Charges payées d‘avance | 130 | |
| 1301 | Produits à recevoir | 130 | |
| 130 | Compte de régularisation de l’actif | 10 | |
| 10 | Actifs circulants | 1 | |
| 1400 | Titres à long terme | 140 | |
| 1440 | Prêts | 140 | |
| 1460 | Prêts à actionnaire | 140 | |
| 140 | Immobilisations financières | 14 | |
| 1480 | Participations | 148 | |
| 148 | Participations | 14 | |
| 1500 | Machines et appareils | 150 | |
| 1510 | Mobilier et installations | 150 | |
| 1520 | Machines de bureau, informatique, systèmes de communication | 150 | |
| 1530 | Véhicules | 150 | |
| 1540 | Outillages et appareils | 150 | |
| 150 | Immobilisations corporelles meubles | 14 | |
| 1600 | Immeubles d’exploitation | 160 | |
| 160 | Immobilisations corporelles immeubles | 14 | |
| 1700 | Brevets, know-how, licences, droits, développement | 170 | |
| 1710 | Marques commerciales | 170 | |
| 1712 | Modèles | 170 | |
| 1770 | Goodwill | 170 | |
| 170 | Immobilisations incorporelles | 14 | |
| 1850 | Capital actions, capital social, droits de participations ou capital de fondation non versés | 180 | |
| 180 | Capital non versé : capital social, capital de fondation | 14 | |
| 14 | Actifs immobilisés | 1 | |
| 1 | Total actifs | 00 | |
| PASSIFS | |||
| 2000 | Dettes résultant d’achats et de prestation de services (créanciers) | 200 | |
| 2030 | Acomptes de clients | 200 | |
| 200A | Créanciers | 200 | |
| 200 | Dettes à court terme résultant d’achats et de prestations de services | 20 | |
| 2100 | Dettes bancaires | 210 | |
| 2120 | Engagements de financement par leasing | 210 | |
| 2140 | Autres dettes à court terme rémunérées | 210 | |
| 210 | Dettes à court terme rémunérés | 20 | |
| 2200 | TVA due | 220 | |
| 2201 | Décompte TVA | 220 | |
| 2206 | Impôt anticipé dû | 220 | |
| 2208 | Impôts directs | 220 | |
| 2210 | Autres dettes à court terme | 220 | |
| 2260 | Dettes envers actionnaire | 220 | |
| 2261 | Dividendes | 220 | |
| 2270 | Assurances sociales et institutions de prévoyance | 220 | |
| 2279 | Impôt à la source | 220 | |
| 220 | Autres dettes à court terme | 20 | |
| 2300 | Charges à payer | 230 | |
| 2301 | Produits encaissés d’avance | 230 | |
| 2330 | Provisions à court terme | 230 | |
| 230 | Passifs de régularisation et provisions à court terme | 20 | |
| 20 | Dettes à court terme | 2A | |
| 2400 | Dettes bancaires | 240 | |
| 2420 | Engagements de financement par leasing | 240 | |
| 2430 | Emprunts obligataires | 240 | |
| 2450 | Emprunts | 240 | |
| 2451 | Hypothèques | 240 | |
| 240 | Dettes à long terme rémunérées | 24 | |
| 2500 | Autres dettes à long terme | 250 | |
| 250 | Autres dettes à long terme | 24 | |
| 2600 | Provisions | 260 | |
| 260 | Provisions à long termes et provisions légales | 24 | |
| 24 | Dettes à long terme | 2A | |
| 2A | Fonds étrangers | 2 | |
| 2800 | Capital-actions, capital social, capital de fondation | 280 | |
| 280 | Capital social ou capital de fondation | 28 | |
| 2900 | Réserves légales issues du capital | 290 | |
| 2940 | Réserves d‘évaluation | 290 | |
| 290 | Réserves légales issues du capital | 28 | |
| 2950 | Réserves légales issues du bénéfice | 295 | |
| 295 | Réserves légales issues du bénéfice | 28 | |
| 2960 | Réserves libres | 296 | |
| 296 | Réserves libres | 28 | |
| 2970 | Bénéfice / perte reporté | 297 | |
| 29A | Bénéfice / perte de l’exercice | 297 | |
| 297 | Bénéfice / perte du bilan | 28 | |
| 2980 | Propres actions, parts sociales, droits de participations (poste négatif) | 298 | |
| 298 | Propres actions, parts sociales, droits de participations (poste négatif) | 28 | |
| 28 | Fonds propres | 2 | |
| 2 | Total passifs | 00 | |
| COMPTE DE RÉSULTAT | |||
| 3000 | Ventes de produits fabriqués | 30 | |
| 3200 | Ventes de marchandises | 30 | |
| 3400 | Ventes de prestations | 30 | |
| 3600 | Autres ventes et prestations de services | 30 | |
| 3710 | Consommations propres | 30 | |
| 3800 | Déductions sur ventes | 30 | |
| 3805 | Pertes sur clients, variation du ducroire | 30 | |
| 30 | Chiffre d'affaires net résultant des ventes et prestations de services | 3 | |
| 3900 | Variation des stocks de produits semi-finis | 39 | |
| 3901 | Variation des stocks de produits finis | 39 | |
| 3940 | Variation de la valeur des prestations non facturées | 39 | |
| 39 | Variation des travaux en cours et des prestations non facturées | 3 | |
| 3 | Produit net des ventes et des prestations de service | E1 | |
| 4000 | Charges de matériel de l'atelier | 4 | |
| 4200 | Achats de marchandises destinées à la revente | 4 | |
| 4400 | Prestations / travaux de tiers | 4 | |
| 4500 | Charges d'énergie pour l'exploitation | 4 | |
| 4900 | Déductions sur les charges | 4 | |
| 4 | Charges de matériel, de marchandises et de prestations de tiers | E1 | |
| E1 | Résultat brut d'exploitation | E2 | |
| 5000 | Salaires | 5 | |
| 5700 | AVS, AI, APG, assurance-chômage | 5 | |
| 5710 | Caisse de compensation familiale | 5 | |
| 5720 | Prévoyance professionnelle | 5 | |
| 5730 | Assurance-accidents | 5 | |
| 5740 | Assurance pour indemnités maladie | 5 | |
| 5790 | Impôts à la source | 5 | |
| 5800 | Autres charges du personnel | 5 | |
| 5810 | Formation | 5 | |
| 5820 | Frais de voyage | 5 | |
| 5830 | Indemnités forfaitaires | 5 | |
| 5900 | Charges de personnel temporaire | 5 | |
| 5 | Charges de personnel | E2 | |
| E2 | Résultat brut d'exploitation après charges de personnel | E3 | |
| 6000 | Charges de locaux | 60 | |
| 6040 | Nettoyage locaux | 60 | |
| 60 | Charges de locaux | 6 | |
| 6100 | Entretien, réparations et remplacement des inst. servant à l'exploitation | 61 | |
| 6105 | Leasing immobilisations corporelles meubles | 61 | |
| 61 | Entretien, réparations et remplacement des inst. servant à l'exploitation | 6 | |
| 6200 | Réparations | 62 | |
| 6210 | Carburant | 62 | |
| 6220 | Assurances voitures | 62 | |
| 6260 | Leasing et location de véhicules | 62 | |
| 6270 | Charges de véhicules comme prélèvements à titre privé | 62 | |
| 6282 | Charges de transport | 62 | |
| 62 | Charges de véhicules et de transport | 6 | |
| 6300 | Assurances-choses, droits, taxes, autorisations | 63 | |
| 63 | Assurances-choses | 6 | |
| 6402 | Électricité | 64 | |
| 6410 | Chauffage | 64 | |
| 6430 | Eau | 64 | |
| 6460 | Évacuation des déchets | 64 | |
| 64 | Charges d'énergie et évacuation des déchets | 6 | |
| 6500 | Matériel de bureau | 65 | |
| 6503 | Littérature technique, journaux, revues | 65 | |
| 6510 | Téléphone, Internet | 65 | |
| 6511 | Services d'hosting | 65 | |
| 6513 | Frais postaux | 65 | |
| 6570 | Charges et leasing d'informatique | 65 | |
| 6580 | Licences, updates | 65 | |
| 6583 | Consommables | 65 | |
| 65 | Charges d'administration et d'informatique | 6 | |
| 6600 | Publicité | 66 | |
| 6642 | Cadeaux à la clientèle | 66 | |
| 66 | Publicité | 6 | |
| 6700 | Autres charges d'exploitation | 67 | |
| 67 | Autres charges d'exploitation | 6 | |
| 6 | Charges divers d'exploitation | E3 | |
| E3 | Résultat d'exploitation avant intérêts, impôts et amortissements (EBITDA) | E4 | |
| 6800 | Amortissement et ajustement de valeur des postes sur les actifs immobilisés | 68 | |
| 68 | Amortissement et ajustement de valeur des immobilitations | E4 | |
| E4 | Résultat d'exploitation avant intérêts, impôts (EBIT) | E5 | |
| 6900 | Charges pour intérêts bancaires | 69 | |
| 6940 | Frais bancaires | 69 | |
| 6950 | Produits financiers | 69 | |
| 69 | Charges et produits financiers | E5 | |
| E5 | Résultat d'exploitation avant impôts (EBT) | E6 | |
| 7000 | Produits accessoires | 7 | |
| 7010 | Charges accessoires | 7 | |
| 7500 | Produits des immeubles d'exploitation | 7 | |
| 7510 | Charges des immeubles d'exploitation | 7 | |
| 7 | Résultat des activités annexes d'exploitation | E6 | |
| 8000 | Charges hors exploitation | 8 | |
| 8100 | Produits hors exploitation | 8 | |
| 8500 | Charges extraordinaires, exceptionnelles ou hors période | 8 | |
| 8510 | Produits extraordinaires, exceptionnels ou hors période | 8 | |
| 8 | Résultats extraordinaires et hors exploitation | E6 | |
| E6 | Résultat de l'exercice avant impôts | E7 | |
| 8900 | Impôts directs | 89 | |
| 89 | Impôts directs | E7 | |
| E7 | Résultat de l'exercice | 29A | |
| 00 | Différence doit être = 0 (cellule vide) | ||
| Clients et Fournisseurs | |||
| Clients | |||
| 110001 | Société 1 | CLI | |
| 110002 | Société 2 | CLI | |
| 110003 | Société 3 | CLI | |
| CLI | Total client | 100A | |
| Créanciers | |||
| 200001 | Société 1 | CRE | |
| 200002 | Société 2 | CRE | |
| 200003 | Société 3 | CRE | |
| CRE | Total Créanciers | 200A | |
| CENTRES DE COÛT | |||
| .EMB | Emballages A | ST | |
| .MPR | Matières premières A | ST | |
| .MAU | Matières auxiliaires A | ST | |
| ST | Total Stock | ||
| ,ENT1 | Entretien1 | ENT | |
| ,ENT2 | Entretien 2 | ENT | |
| ,ENT3 | Entretien 3 | ENT | |
| ENT | Total frais d'entretien | ||
| ;PB1 | Publicité type 1 | PU | |
| ;PB2 | Publicité type 2 | PU | |
| PU | Totale charges de publicité | ||
| Cod. TVA | Libellé | %TVA |
|---|---|---|
| Dernière mise à jour: 26.11.2019 | ||
| Ventes | ||
| V0 | Ventes sans TVA | |
| VE | Ventes à l'étranger | |
| V20 | Ventes au 20.00% | 20.00 |
| V10 | Ventes au 10.00% | 10.00 |
| V5 | Ventes au 5.00% | 5.00 |
| V2 | Ventes au 2.00% | 2.00 |
| TOTAL TVA DUE | ||
| Achats | ||
| A20 | Achats au 20.00% | 20.00 |
| A10 | Achats au 10.00% | 10.00 |
| A5 | Achats au 5.00% | 5.00 |
| A2 | Achats au 2.00% | 2.00 |
| TOTAL TVA DEDUCTIBLE | ||
| TOTAL | ||
Comptabilité pour Entreprise jusqu'à 500'000 CHF chiffre d'affaires
在此文中
Comptabilité pour Entreprise jusqu'à 500'000 CHF chiffre d'affaires
Comptabilité pour Entreprise jusqu'à 500'000 CHF chiffre d'affaires
Plan comptable structuré pour gérer une entreprise dont le chiffre d'affaires annuel n'excède pas 500'000 CHF. Avec TVA et des centres de coûts.
模板文件
Plan comptable structuré pour gérer une entreprise dont le chiffre d'affaires annuel n'excède pas 500'000 CHF. Avec TVA et des centres de coûts.
模板预览
Etude Professionnelle XX
Comptabilité 2020
DeviseBase: EUR
Comptabilité en partie double avec TVA
| Groupe | Compte | Libellé | Add. dans | Gr1 |
|---|---|---|---|---|
| BILAN | ||||
| ACTIFS | ||||
| 1000 | Caisse | 10 | ||
| 1010 | Compte courant postal | 10 | ||
| 1020 | Compte courant bancaire CHF | 10 | ||
| 1090 | Compte d'attente en monnaie | 10 | ||
| 1091 | Compte d'attente salaires | 10 | ||
| 1099 | Compte de passage pour éclaircissements | 10 | ||
| 1100 | Créances envers des tiers | 10 | ||
| 1176 | Impôt anticipé à récupérer | 10 | ||
| 1191 | Cautionnements en espèces | 10 | ||
| 1300 | Charges constatées d'avance | 10 | ||
| 10 | Actifs circulants | 1 | 1 | |
| 1500 | Machines et appareils | 14 | ||
| 1510 | Mobilier d'exploitation | 14 | ||
| 1512 | Installations de magazin | 14 | ||
| 1520 | Machines de bureau | 14 | ||
| 1521 | Infrastructures informatiques | 14 | ||
| 1526 | Logiciels | 14 | ||
| 1530 | Automobiles | 14 | ||
| 14 | Actifs immobilisés | 1 | 1 | |
| 1 | TOTAL ACTIFS | 00 | 1 | |
| PASSIFS | ||||
| 2000 | Dettes résultant d'achats de matières et de marchandises | 20 | ||
| 2100 | Dettes bancaires à court terme | 20 | ||
| 2200 | TVA due | 20 | ||
| 2201 | Décompte TVA | 20 | ||
| 2300 | Charges à payer | 20 | ||
| 20 | Dettes à court terme | 2 | 1 | |
| 2400 | Dettes bancaires | 24 | ||
| 2500 | Autres dettes à long terme | 24 | ||
| 2600 | Provisions | 24 | ||
| 24 | Dettes à long terme | 2 | ||
| 2800 | Capital propre / Capital social | 28 | ||
| 2870 | Compte privé | 28 | ||
| 2970 | Bénéfice reporté / Perte reportée | 28 | ||
| 297 | Bénéfice de l'exercice / Perte de l'exercice | 28 | 1 | |
| 28 | Capitaux propres | 2 | 1 | |
| 2 | TOTAL PASSIFS | 00 | 1 | |
| COMPTE DE RESULTAT | ||||
| PRODUITS | ||||
| 3000 | Ventes de marchandises | 3 | ||
| 3400 | Encaissement honoraires | 3 | ||
| 3490 | Escomptes | 3 | ||
| 3600 | Autres produits | 3 | ||
| 3710 | Consommations propres | 3 | ||
| 3809 | TVA taux de la dette fiscale nette | 3 | ||
| 3 | TOTAL PRODUITS | 02 | 1 | |
| CHARGES | ||||
| 4000 | Achats | 4 | ||
| 4 | Total Achats | 4-6 | ||
| 5600 | Salaires pour l'administration | 5 | ||
| 5700 | AVS, AI, APG, assurance-chômage | 5 | ||
| 5710 | Caisse de compensation familiale | 5 | ||
| 5720 | Prévoyance professionnelle | 5 | ||
| 5730 | Assurance-accidents | 5 | ||
| 5740 | Assurance pour indemnités maladie | 5 | ||
| 5790 | Impôts à la source | 5 | ||
| 5820 | Frais de voyages | 5 | ||
| 5830 | Indemnités forfaitaires pour les cadres | 5 | ||
| 5880 | Autres frais du personnel | 5 | ||
| 5900 | Employés temporaires | 5 | ||
| 5 | Charges de personnel | 4-6 | 1 | |
| 6000 | Loyer | 6 | ||
| 6030 | Charges accessoires | 6 | ||
| 6100 | Entretien, réparations et remplacement des inst. servant à l'exploitation | 6 | ||
| 6200 | Réparation, service et nettoyage | 6 | ||
| 6210 | Carburants | 6 | ||
| 6220 | Assurances | 6 | ||
| 6282 | Frais de transport | 6 | ||
| 6300 | Assurances-choses, droits, taxes, autorisations | 6 | ||
| 6400 | Charges d'énergie et évacuation des déchets | 6 | ||
| 6500 | Matériel de bureau | 6 | ||
| 6503 | Littérature technique, journaux, revues | 6 | ||
| 6510 | Téléphone | 6 | ||
| 6511 | Services d'hosting | 6 | ||
| 6513 | Frais de port | 6 | ||
| 6520 | Contributions | 6 | ||
| 6521 | Dons et cadeaux | 6 | ||
| 6530 | Honoraires pour fiduciaire | 6 | ||
| 6574 | Investissements de faible montant | 6 | ||
| 6583 | Consommables | 6 | ||
| 6600 | Publicité | 6 | ||
| 6641 | Services aux clinets | 6 | ||
| 6642 | Cadeaux ä la clientèle | 6 | ||
| 6800 | Amortissement et ajustement de valeur des postes sur les actifs immobilisés | 6 | ||
| 6900 | Charges financières | 6 | ||
| 6950 | Produits financiers | 6 | ||
| 8900 | Impôts | 6 | ||
| 6 | Total autre charges de l'exercice | 4-6 | 1 | |
| 4-6 | TOTAL CHARGES | 02 | ||
| 02 | Bénéfice (-) / Perte (+) Compte de résultat | 297 | 1 | |
| 00 | Différence doit être = 0 (cellule vide) | |||
| CENTRES DE COÛT | ||||
| ,ENT1 | Entretien1 | ENT | ||
| ,ENT2 | Entretien 2 | ENT | ||
| ,ENT3 | Entretien 3 | ENT | ||
| ENT | Total frais d'entretien | |||
| ;PB1 | Publicité type 1 | PU | ||
| ;PB2 | Publicité type 2 | PU | ||
| PU | Totale charges de publicité |
| Cod. TVA | Libellé | %TVA |
|---|---|---|
| Dernière mise à jour: 26.11.2019 | ||
| Ventes | ||
| V0 | Ventes sans TVA | |
| VE | Ventes à l'étranger | |
| V20 | Ventes au 20.00% | 20.00 |
| V10 | Ventes au 10.00% | 10.00 |
| V5 | Ventes au 5.00% | 5.00 |
| V2 | Ventes au 2.00% | 2.00 |
| TOTAL TVA DUE | ||
| Achats | ||
| A20 | Achats au 20.00% | 20.00 |
| A10 | Achats au 10.00% | 10.00 |
| A5 | Achats au 5.00% | 5.00 |
| A2 | Achats au 2.00% | 2.00 |
| TOTAL TVA DEDUCTIBLE | ||
| TOTAL | ||
Comptabilité pour Entreprises individuelles
在此文中
Comptabilité pour Entreprises individuelles
Comptabilité pour Entreprises individuelles
Pour gérer les comptes d'une petite entreprise individuelle avec TVA et centres de coût.
模板文件
Pour gérer les comptes d'une petite entreprise individuelle avec TVA et centres de coût.
模板预览
DeviseBase: EUR
Comptabilité en partie double avec TVA
| Groupe | Compte | Libellé | Add. dans |
|---|---|---|---|
| BILAN | |||
| ACTIFS | |||
| 1000 | Caisse | 100 | |
| 1020 | Banque | 100 | |
| 100 | Liquidités | 10 | |
| 1060 | Titres | 106 | |
| 106 | Avoirs à court terme cotés en bourse | 10 | |
| 1090 | Compte d'attente en monnaie | 109 | |
| 1091 | Compte d'attente salaires | 109 | |
| 1099 | Compte de passage pour éclaircissements | 109 | |
| 109 | Comptes de transit et d’attente | 10 | |
| 1100 | Créances provenant de livraisons et de prestations (Débiteurs) | 110 | |
| 1109 | Ducroire | 110 | |
| 110 | Créances résultant de livraisons et prestations | 10 | |
| 1140 | Avances et prêts | 114 | |
| 1176 | Impôt anticipé | 114 | |
| 1180 | Créances envers les assurances sociales et institutions de prévoyance | 114 | |
| 1188 | Impôt à la source | 114 | |
| 1190 | Autres créances à court terme | 114 | |
| 1191 | Cautionnements en espèces | 114 | |
| 114 | Autres créances à court terme | 10 | |
| 1200 | Marchandises commerciales | 120 | |
| 1210 | Matières premières | 120 | |
| 1220 | Matières auxiliaires | 120 | |
| 1230 | Matières consommables | 120 | |
| 1250 | Marchandises en consignation | 120 | |
| 1260 | Stocks de produits finis | 120 | |
| 1270 | Stocks de produits pas finis | 120 | |
| 1280 | Travaux en cours | 120 | |
| 120 | Stocks et prestations non facturées | 10 | |
| 1300 | Charges payées d‘avance | 130 | |
| 1301 | Produits à recevoir | 130 | |
| 130 | Compte de régularisation de l’actif | 10 | |
| 10 | Actifs circulants | 1 | |
| 1400 | Titres à long terme | 140 | |
| 1440 | Prêts | 140 | |
| 140 | Immobilisations financières | 14 | |
| 1480 | Participations | 148 | |
| 148 | Participations | 14 | |
| 1500 | Machines et appareils | 150 | |
| 1510 | Mobilier et installations | 150 | |
| 1520 | Machines de bureau, informatique, systèmes de communication | 150 | |
| 1530 | Véhicules | 150 | |
| 1540 | Outillages et appareils | 150 | |
| 150 | Immobilisations corporelles meubles | 14 | |
| 1600 | Immeubles d’exploitation | 160 | |
| 160 | Immobilisations corporelles immeubles | 14 | |
| 14 | Actifs immobilisés | 1 | |
| 1 | Total actifs | 00 | |
| PASSIFS | |||
| 2000 | Dettes résultant d’achats et de prestation de services (créanciers) | 200 | |
| 2030 | Acomptes de clients | 200 | |
| 200 | Dettes à court terme résultant d’achats et de prestations de services | 20 | |
| 2100 | Dettes bancaires | 210 | |
| 2120 | Engagements de financement par leasing | 210 | |
| 2140 | Autres dettes à court terme rémunérées | 210 | |
| 210 | Dettes à court terme rémunérés | 20 | |
| 2200 | TVA due | 220 | |
| 2201 | Décompte TVA | 220 | |
| 2206 | Impôt anticipé dû | 220 | |
| 2208 | Impôts directs | 220 | |
| 2210 | Autres dettes à court terme | 220 | |
| 2270 | Assurances sociales et institutions de prévoyance | 220 | |
| 2279 | Impôt à la source | 220 | |
| 220 | Autres dettes à court terme | 20 | |
| 2300 | Charges à payer | 230 | |
| 2301 | Produits encaissés d’avance | 230 | |
| 2330 | Provisions à court terme | 230 | |
| 230 | Passifs de régularisation et provisions à court terme | 20 | |
| 20 | Dettes à court terme | 2A | |
| 2400 | Dettes bancaires | 240 | |
| 2420 | Engagements de financement par leasing | 240 | |
| 2430 | Emprunts obligataires | 240 | |
| 2450 | Emprunts | 240 | |
| 2451 | Hypothèques | 240 | |
| 240 | Dettes à long terme rémunérées | 24 | |
| 2500 | Autres dettes à long terme | 250 | |
| 250 | Autres dettes à long terme | 24 | |
| 2600 | Provisions | 260 | |
| 260 | Provisions à long termes et provisions légales | 24 | |
| 24 | Dettes à long terme | 2A | |
| 2A | Fonds étrangers | 2 | |
| 2800 | Capital propre en début d’exercice | 28 | |
| 2820 | Apports de capital / prélèvements sur capital | 28 | |
| 2850 | Compte privé | 28 | |
| 297 | Bénéfice de l'exercice / Perte de l'exercice | 28 | |
| 28 | Fonds propres | 2 | |
| 2 | Total passifs | 00 | |
| COMPTE DE RÉSULTAT | |||
| 3000 | Ventes de produits fabriqués | 30 | |
| 3200 | Ventes de marchandises | 30 | |
| 3400 | Ventes de prestations | 30 | |
| 3600 | Autres ventes et prestations de services | 30 | |
| 3710 | Consommations propres | 30 | |
| 3800 | Déductions sur ventes | 30 | |
| 3805 | Pertes sur clients, variation du ducroire | 30 | |
| 3809 | TVA taux de la dette fiscale nette | 30 | |
| 30 | Chiffre d'affaires net résultant des ventes et prestations de services | 3 | |
| 3900 | Variation des stocks de produits semi-finis | 39 | |
| 3901 | Variation des stocks de produits finis | 39 | |
| 3940 | Variation de la valeur des prestations non facturées | 39 | |
| 39 | Variation des travaux en cours et des prestations non facturées | 3 | |
| 3 | Produit net des ventes et des prestations de service | E1 | |
| 4000 | Charges de matériel de l'atelier | 4 | |
| 4200 | Achats de marchandises destinées à la revente | 4 | |
| 4400 | Prestations / travaux de tiers | 4 | |
| 4500 | Charges d'énergie pour l'exploitation | 4 | |
| 4900 | Déductions sur les charges | 4 | |
| 4 | Charges de matériel, de marchandises et de prestations de tiers | E1 | |
| E1 | Résultat brut d'exploitation | E2 | |
| 5000 | Salaires | 5 | |
| 5700 | AVS, AI, APG, assurance-chômage | 5 | |
| 5710 | Caisse de compensation familiale | 5 | |
| 5720 | Prévoyance professionnelle | 5 | |
| 5730 | Assurance-accidents | 5 | |
| 5740 | Assurance pour indemnités maladie | 5 | |
| 5790 | Impôts à la source | 5 | |
| 5800 | Autres charges du personnel | 5 | |
| 5810 | Formation | 5 | |
| 5820 | Frais de voyage | 5 | |
| 5830 | Indemnités forfaitaires | 5 | |
| 5900 | Charges de personnel temporaire | 5 | |
| 5 | Charges de personnel | E2 | |
| E2 | Résultat brut d'exploitation après charges de personnel | E3 | |
| 6000 | Charges de locaux | 60 | |
| 6040 | Nettoyage locaux | 60 | |
| 60 | Charges de locaux | 6 | |
| 6100 | Entretien, réparations et remplacement des inst. servant à l'exploitation | 61 | |
| 6105 | Leasing immobilisations corporelles meubles | 61 | |
| 61 | Entretien, réparations et remplacement des inst. servant à l'exploitation | 6 | |
| 6200 | Réparations | 62 | |
| 6210 | Carburant | 62 | |
| 6220 | Assurances voitures | 62 | |
| 6260 | Leasing et location de véhicules | 62 | |
| 6270 | Charges de véhicules comme prélèvements à titre privé | 62 | |
| 6282 | Charges de transport | 62 | |
| 62 | Charges de véhicules et de transport | 6 | |
| 6300 | Assurances-choses, droits, taxes, autorisations | 63 | |
| 63 | Assurances-choses | 6 | |
| 6402 | Électricité | 64 | |
| 6410 | Chauffage | 64 | |
| 6430 | Eau | 64 | |
| 6460 | Évacuation des déchets | 64 | |
| 64 | Charges d'énergie et évacuation des déchets | 6 | |
| 6500 | Matériel de bureau | 65 | |
| 6503 | Littérature technique, journaux, revues | 65 | |
| 6510 | Téléphone, Internet | 65 | |
| 6511 | Services d'hosting | 65 | |
| 6513 | Frais postaux | 65 | |
| 6570 | Charges et leasing d'informatique | 65 | |
| 6580 | Licences, updates | 65 | |
| 6583 | Consommables | 65 | |
| 65 | Charges d'administration et d'informatique | 6 | |
| 6600 | Publicité | 66 | |
| 6642 | Cadeaux à la clientèle | 66 | |
| 66 | Publicité | 6 | |
| 6700 | Autres charges d'exploitation | 67 | |
| 67 | Autres charges d'exploitation | 6 | |
| 6 | Charges divers d'exploitation | E3 | |
| E3 | Résultat d'exploitation avant intérêts, impôts et amortissements (EBITDA) | E4 | |
| 6800 | Amortissement et ajustement de valeur des postes sur les actifs immobilisés | 68 | |
| 68 | Amortissement et ajustement de valeur des immobilitations | E4 | |
| E4 | Résultat d'exploitation avant intérêts, impôts (EBIT) | E5 | |
| 6900 | Charges pour intérêts bancaires | 69 | |
| 6940 | Frais bancaires | 69 | |
| 6950 | Produits financiers | 69 | |
| 69 | Charges et produits financiers | E5 | |
| E5 | Résultat d'exploitation avant impôts (EBT) | E6 | |
| 7000 | Produits accessoires | 7 | |
| 7010 | Charges accessoires | 7 | |
| 7500 | Produits des immeubles d'exploitation | 7 | |
| 7510 | Charges des immeubles d'exploitation | 7 | |
| 7 | Résultat des activités annexes d'exploitation | E6 | |
| 8000 | Charges hors exploitation | 8 | |
| 8100 | Produits hors exploitation | 8 | |
| 8500 | Charges extraordinaires, exceptionnelles ou hors période | 8 | |
| 8510 | Produits extraordinaires, exceptionnels ou hors période | 8 | |
| 8 | Résultats extraordinaires et hors exploitation | E6 | |
| E6 | Résultat de l'exercice avant impôts | E7 | |
| 8900 | Impôts directs | 89 | |
| 89 | Impôts directs | E7 | |
| E7 | Résultat de l'exercice | 297 | |
| 00 | Différence doit être = 0 (cellule vide) | ||
| CENTRES DE COÛT | |||
| .EMB | Emballages A | ST | |
| .MPR | Matières premières A | ST | |
| .MAU | Matières auxiliaires A | ST | |
| ST | Total Stock | ||
| ,ENT1 | Entretien1 | ENT | |
| ,ENT2 | Entretien 2 | ENT | |
| ,ENT3 | Entretien 3 | ENT | |
| ENT | Total frais d'entretien | ||
| ;PB1 | Publicité type 1 | PU | |
| ;PB2 | Publicité type 2 | PU | |
| PU | Totale charges de publicité |
| Cod. TVA | Libellé | %TVA |
|---|---|---|
| Dernière mise à jour: 26.11.2019 | ||
| Ventes | ||
| V0 | Ventes sans TVA | |
| VE | Ventes à l'étranger | |
| V20 | Ventes au 20.00% | 20.00 |
| V10 | Ventes au 10.00% | 10.00 |
| V5 | Ventes au 5.00% | 5.00 |
| V2 | Ventes au 2.00% | 2.00 |
| TOTAL TVA DUE | ||
| Achats | ||
| A20 | Achats au 20.00% | 20.00 |
| A10 | Achats au 10.00% | 10.00 |
| A5 | Achats au 5.00% | 5.00 |
| A2 | Achats au 2.00% | 2.00 |
| TOTAL TVA DEDUCTIBLE | ||
| TOTAL | ||
Libro de caja para un Comercio con IVA (con transacciones)
在此文中
Libro de caja para un Comercio con IVA (con transacciones)
Libro de caja para un Comercio con IVA (con transacciones)
Plantilla general perfecta para gestionar el libro de caja de un comercio o tienda. Incluye la gestión del IVA.
直接在网页中打开Banana财务会计+
无需任何安装,可以直接在您的浏览器上运行 Banana财务会计+。客制化您的模板,输入发生业务并将文件保存在您的电脑上。
Open tutorial in WebApp模板预览
Comercio XX
Moneda base: EUR
Cash Manager con IVA
| Grupo | Cuenta | Descripción | Sumar en |
|---|---|---|---|
| 1000 | Efectivo | ||
| Grupo | Categoría | Descripción | Sumar en |
|---|---|---|---|
| 000 | Saldo inicial | 01 | |
| 01 | SALDO INICIAL | 00 | |
| INGRESO | |||
| 100 | Recibos para el producto "A" | 10 | |
| 101 | Recibos para el producto "B" | 10 | |
| 102 | Recibos para el producto "C" | 10 | |
| 10 | Total de ventas | 1 | |
| 110 | Retirada de la cuenta corriente | 11 | |
| 111 | Servicios | 11 | |
| 112 | Otros | 11 | |
| 11 | Otros ingresos | 1 | |
| 1 | INGRESO TOTAL | 00 | |
| GASTOS | |||
| 200 | Pago en cheques postales | 2 | |
| 210 | Compra de sellos | 2 | |
| 211 | Cartas postales y paquetes | 2 | |
| 212 | Suministros de correo | 2 | |
| 213 | Objetos de escritorio, aparatos, limpieza | 2 | |
| 114 | Alquiler, electricidad, agua | 2 | |
| 215 | Teléfono y fax | 2 | |
| 220 | Conservación de la propiedad inmobiliaria | 2 | |
| 221 | Escaparatismo | 2 | |
| 222 | Publicidad, folletos | 2 | |
| 223 | Cuotas de agencia | 2 | |
| 230 | Pago de bienes | 2 | |
| 240 | Sueldos y préstamos particulares | 2 | |
| 241 | Cuotas y otros permisos | 2 | |
| 250 | IVA (pagado y recibido) | 2 | |
| 2 | GASTOS TOTALES | 00 | |
| 00 | SALDO DE CAJA | ||
| DIVISIÓN EN LOS CENTROS DE COSTOS Y BENEFICIOS | |||
| .T | Dirección personal y de tienda | T1 | |
| .B | Administración de bienes | T1 | |
| .I | Inversiones | T1 | |
| T1 | DIVISIÓN TOTAL | ||
| Cód.IVA | Descripción | % IVA |
|---|---|---|
| Cuotas de IVA | ||
| V0 | Exento de ventas | |
| VE | Exento de ventas exteriores | |
| V10 | Ventas al 10% | 10.00 |
| VD10 | Descuento del 10% en ventas | 10.00 |
| IVA perceptible | ||
| Bienes de compra y servicios | ||
| C10 | Bienes de compra y servicios al 10% | 10.00 |
| CD10 | Descuento en bienes de compra + servicios 10% | 10.00 |
| C5 | Bienes de compra y servicios al 5% | 5.00 |
| CD5 | Descuento en bienes y servicios 5% | 5.00 |
| Gastos de mantenimiento e inversión | ||
| I10 | Gastos de mantenimiento e inversión al 10% | 10.00 |
| ID10 | Descuento en gastos de mantenimiento e inversión 10% | 10.00 |
| I5 | Gastos de mantenimiento e inversión al 5% | 5.00 |
| ID5 | Descuento en gastos de mantenimiento e inversión 5% | 5.00 |
含增值税公司的复式记账模板
在此文中
含增值税公司的复式记账模板
含增值税公司的复式记账模板
轻松地、免费地开始您公司的复式记账,包括增值税管理,并立即获得损益表和资产负债表。可以根据您的具体需要对这个现成的模板进行编辑,用来管理您的公司、独资企业、合伙企业或中小型企业的会计。Banana财务会+ 是一个专业的软件,由于它类似于Excel,所以使用起来非常直观和快速。如果在做账中出现了错误,也可以随时纠正,直到获得完美的会计报表。
直接在网页中打开Banana财务会计+
无需任何安装,可以直接在您的浏览器上运行 Banana财务会计+。客制化您的模板,输入发生业务并将文件保存在您的电脑上。
在浏览器中打开模板 Open tutorial in WebApp模板预览
XX 公司
本位币: USD
复式记账含增值税
| 总组 | 账号 | 摘要 | 总和 |
|---|---|---|---|
| 资产负债表 | |||
| 资产 | |||
| 银行账户 | |||
| 商业账户 | 商业账户 | 银行 | |
| 商业存储账户 | 商业存储账户 | 银行 | |
| 工资账户 | 工资账户 | 银行 | |
| 现金 | 小额现金 - 自付費用 | 银行 | |
| 易货贸易 | 易货贸易账户 | 银行 | |
| 银行 | 银行账户总计 | 资产 | |
| 应收账款 | |||
| 客户 | 应收账款 (客户登记) | 应收 | |
| 应收 | 应收账款总计 | 资产 | |
| 流动资产 | |||
| 库存 | 库存 | 流动资产 | |
| 未存入的资金 | 未存入的资金 | 流动资产 | |
| 流动资产 | 流动资产总计 | 资产 | |
| 固定资产 | |||
| 设备 | 设备 | 固定 | |
| 家具 | 家具和固定装置 | 固定 | |
| 车辆 | 车辆 | 固定 | |
| 累计折旧 | 累计折旧 | 固定 | |
| 固定 | 固定资产总计 | 资产 | |
| 其它资产 | |||
| 启动 | 启动成本 (会计人员使用) | 其它 | |
| 摊销 | 累计摊销 | 其它 | |
| 应收票据1 | 应收票据1 (高级职员、所有者、关联方) | 其它 | |
| 应收票据2 | 应收票据2 | 其它 | |
| 其它 | 其它资产总计 | 资产 | |
| 资产 | 总资产 | 00 | |
| 负债 | |||
| 应付账款 | |||
| 供应商 | 供应商登记 | 应付 | |
| 应付 | 应付账款总计 | 负债 | |
| 用于采购的信用卡 | |||
| 美国运通 | 美国运通 - 信用卡贷款 | 信用卡 | |
| Visa | Visa - 信用卡贷款 | 信用卡 | |
| 信用卡 | 信用卡总计 | 负债 | |
| 流动负债 | |||
| 应计 | 应计费用 | 流动负债 | |
| 应付薪资税 | 应付薪资税 | 流动负债 | |
| 应付营业税 | 应付营业税 | 流动负债 | |
| 押金 | 客户押金 | 流动负债 | |
| 长期部分 | 长期负债的流动部分 | 流动负债 | |
| 应缴增值税 | 应缴增值税 | 流动负债 | |
| 增值税 | 自动计算增值税 | 流动负债 | |
| 流动负债 | 流动负债总计 | 负债 | |
| 长期负债 | |||
| 银行贷款 | 银行贷款 | 长期负债 | |
| 应付票据1 | 应付票据1 | 长期负债 | |
| 应付票据2 | 应付票据2 | 长期负债 | |
| 长期负债 | 长期负债总计 | 负债 | |
| 负债 | 总负债 | 00 | |
| 股权 | |||
| 资本 | 股本/资本合伙人 | 股权 | |
| 附加资本 | 额外出资/额外支付资本 | 股权 | |
| 留存收益 | 留存收益 | 股权 | |
| 期初权益 | 期初余额权益 | 股权 | |
| 股东1 | 分配股东 1 / 股息 / 提款 | 股权 | |
| 结转 | 结转盈亏 | 股权 | |
| 盈利或亏损 | 本年度损益 | 股权 | |
| 股权 | 股权总计 | 00 | |
| 损益表 | |||
| 收入 | |||
| 服务 | 服务收入 | 收入 | |
| 售出的产品 | 零件/产品销售收入 | 收入 | |
| 销售冲销 | 销售冲销 | 收入 | |
| 收入 | 总收入 | 毛利润 | |
| 销货成本 | |||
| 材料费 | 材料、直接产品/服务成本 | 销货成本 | |
| 人工费 | 人工成本 | 销货成本 | |
| 外部服务 | 外部服务/分包商 | 销货成本 | |
| 供应品 | 耗材成本 | 销货成本 | |
| 小型工具 | 小型工具 | 销货成本 | |
| 销货成本 | 销货成本总计 | 毛利润 | |
| 毛利润 | 毛利润 | 息税前利润 | |
| 费用 | |||
| 广告 | 广告、促销、营销费用 | 费用 | |
| 汽车 | 汽车费用 | 费用 | |
| 银行收费 | 银行服务费 | 费用 | |
| 清洁费 | 清洁费 | 费用 | |
| 捐款 | 捐款 | 费用 | |
| 折旧 | 折旧费用 | 费用 | |
| 折扣 | 采取的折扣 | 费用 | |
| 订阅费 | 捐款和订阅费 | 费用 | |
| 保险费 | 汽车保险、人寿、医疗 | 费用 | |
| 利息支出 | 利息支出 | 费用 | |
| 许可证 | 商业执照和许可证 | 费用 | |
| 维修费 | 维护和修理 | 费用 | |
| 餐费 | 膳食和娱乐 | 费用 | |
| 商户费用 | 商家信用卡费用 | 费用 | |
| 办公室 | 办公费用(电脑、邮资、快递、用品)。 | 费用 | |
| 薪资税 | 薪资税 | 费用 | |
| 专业费用 | 专业费用 | 费用 | |
| 租金 | 租金支付 | 费用 | |
| 工资 | 工资 | 费用 | |
| 电话费 | 电话、传真 | 费用 | |
| 旅行 | 旅行 | 费用 | |
| 公用事业 | 公用事业 | 费用 | |
| 费用 | 总费用 | 息税前利润 | |
| 息税前利润 | 息税前利润 | 结果 | |
| 其它收入 | |||
| 利息收入 | 利息收入 | 其它收入 | |
| 其它收入 | 其它收入总计 | 结果 | |
| 其它费用 | |||
| 会计师咨询 | 会计师咨询 | 其它费用 | |
| 其它费用 | 其它费用总计 | 结果 | |
| 结果 | 净利 (盈利(-) 亏损(+) ) | 盈利或亏损 | |
| 00 | 差额应该是=0(空白单元格) | ||
| 客户/供应商登记 | |||
| 客户 | |||
| 客户-Redford | Redford 公司 | 客户总计 | |
| 客户-Smith | John Smith | 客户总计 | |
| 客户-Black | Simon Black | 客户总计 | |
| 客户总计 | 客户总计 | 客户 | |
| 供应商 | |||
| 供应商-Johnson | Johnson 公司 | 供应商总计 | |
| 供应商-Marble | Marble | 供应商总计 | |
| 供应商-Taylor | Mary Taylor | 供应商总计 | |
| 供应商总计 | 供应商总计 | 供应商 | |
| 成本中心 | |||
| 产品 | |||
| .产品 A | 产品 A | 产品 | |
| .产品 B | 产品 B | 产品 | |
| .产品 C | 产品 C | 产品 | |
| 产品 | 产品总计 | ||
| 项目 | |||
| ;项目 A | 项目 A | 项目 | |
| ;项目 B | 项目 B | 项目 | |
| 项目 | 项目总计 | ||
| 部门 | |||
| 分公司 | |||
| :分公司 A | 分公司 A | 分公司 | |
| :分公司 B | 分公司 B | 分公司 | |
| 分公司 | 分公司总计 | ||
| 增值税码 | 摘要 | %税率 |
|---|---|---|
| 应交增值税 | ||
| S0 | 免征增值税销售 | |
| SE | 国外销售免税 | |
| S5 | 销售 5% | 5.00 |
| S10 | 销售 10% | 10.00 |
| SD5 | 销售折扣 5% | 5.00 |
| SD10 | 销售折扣 10% | 10.00 |
| 应退增值税 | ||
| P5 | 购买货物 5% | 5.00 |
| P10 | 购买货物 10% | 10.00 |
| PD5 | 购买折扣 5% | 5.00 |
| PD10 | 购买折扣 10% | 10.00 |
| I5 | 为投资或使用购买的物品 5% | 5.00 |
| I10 | 为投资或使用购买的物品 10% | 10.00 |
| ID5 | 用于投资或使用的购货折扣 5% | 5.00 |
| ID10 | 用于投资或使用的购货折扣 10% | 10.00 |
| 总计 |
含外汇和增值税的公司复式记账模板
在此文中
含外汇和增值税的公司复式记账模板
含外汇和增值税的公司复式记账模板
轻松地、免费地开始您含外汇及增值税的公司复式记账,并立即获得损益表和资产负债表。可以根据您的具体需要对这个现成的模板进行编辑,用来管理您的公司、独资企业、合伙企业或中小型企业的会计。Banana财务会+ 是一个专业的软件,由于它类似于Excel,所以使用起来非常直观和快速。如果在做账中出现了错误,也可以随时纠正,直到获得完美的会计报表。
直接在网页中打开Banana财务会计+
无需任何安装,可以直接在您的浏览器上运行 Banana财务会计+。客制化您的模板,输入发生业务并将文件保存在您的电脑上。
在浏览器中打开模板 Open tutorial in WebApp模板预览
XX 公司
本位币: USD
复式记账含外汇及增值税
| 总组 | 账号 | 摘要 | 货币 | 总和 |
|---|---|---|---|---|
| 资产负债表 | ||||
| 资产 | ||||
| 银行账户 | ||||
| 商业账户 USD | 美元商业账户 (USD) | USD | 银行 | |
| 商业账户 EUR | 欧元商业账户 (EUR) | EUR | 银行 | |
| 商业账户 GBP | 英镑商业账户 (GBP) | GBP | 银行 | |
| 商业存储账户 | 商业存储账户 | USD | 银行 | |
| 工资账户 | 工资账户 | USD | 银行 | |
| 现金 | 小额现金 - 自付費用 | USD | 银行 | |
| 易货贸易 | 易货贸易账户 | USD | 银行 | |
| 银行 | 银行账户总计 | 资产 | ||
| 应收账款 | ||||
| 客户 | 应收账款 (客户登记) | 应收 | ||
| 应收 | 应收账款总计 | 资产 | ||
| 流动资产 | ||||
| 库存 | 库存 | USD | 流动资产 | |
| 未存入的资金 | 未存入的资金 | USD | 流动资产 | |
| 流动资产 | 流动资产总计 | 资产 | ||
| 固定资产 | ||||
| 设备 | 设备 | USD | 固定 | |
| 家具 | 家具和固定装置 | USD | 固定 | |
| 车辆 | 车辆 | USD | 固定 | |
| 累计折旧 | 累计折旧 | USD | 固定 | |
| 固定 | 固定资产总计 | 资产 | ||
| 其它资产 | ||||
| 启动 | 启动成本 (会计人员使用) | USD | 其它 | |
| 摊销 | 累计摊销 | USD | 其它 | |
| 应收票据1 | 应收票据1 (高级职员、所有者、关联方) | USD | 其它 | |
| 应收票据2 | 应收票据2 | USD | 其它 | |
| 其它 | 其它资产总计 | 资产 | ||
| 资产 | 总资产 | 00 | ||
| 负债 | ||||
| 应付账款 | ||||
| 供应商 | 供应商登记 | 应付 | ||
| 应付 | 应付账款总计 | 负债 | ||
| 用于采购的信用卡 | ||||
| 美国运通 | 美国运通 - 信用卡贷款 | USD | 信用卡 | |
| Visa | Visa - 信用卡贷款 | USD | 信用卡 | |
| 信用卡 | 信用卡总计 | 负债 | ||
| 流动负债 | ||||
| 应计 | 应计费用 | USD | 流动负债 | |
| 应付薪资税 | 应付薪资税 | USD | 流动负债 | |
| 应付营业税 | 应付营业税 | USD | 流动负债 | |
| 押金 | 客户押金 | USD | 流动负债 | |
| 长期部分 | 长期负债的流动部分 | USD | 流动负债 | |
| 应缴增值税 | 应缴增值税 | USD | 流动负债 | |
| 增值税 | 自动计算增值税 | USD | 流动负债 | |
| 流动负债 | 流动负债总计 | 负债 | ||
| 长期负债 | ||||
| 银行贷款 | 银行贷款 | USD | 长期负债 | |
| 应付票据1 | 应付票据1 | USD | 长期负债 | |
| 应付票据2 | 应付票据2 | USD | 长期负债 | |
| 长期负债 | 长期负债总计 | 负债 | ||
| 负债 | 总负债 | 00 | ||
| 股权 | ||||
| 资本 | 股本/资本合伙人 | USD | 股权 | |
| 附加资本 | 额外出资/额外支付资本 | USD | 股权 | |
| 留存收益 | 留存收益 | USD | 股权 | |
| 期初权益 | 期初余额权益 | USD | 股权 | |
| 股东1 | 分配股东 1 / 股息 / 提款 | USD | 股权 | |
| 结转 | 结转盈亏 | USD | 股权 | |
| 盈利或亏损 | 本年度损益 | USD | 股权 | |
| 股权 | 股权总计 | 00 | ||
| 损益表 | ||||
| 收入 | ||||
| 服务 | 服务收入 | USD | 收入 | |
| 售出的产品 | 零件/产品销售收入 | USD | 收入 | |
| 销售冲销 | 销售冲销 | USD | 收入 | |
| 收入 | 总收入 | 毛利润 | ||
| 销货成本 | ||||
| 材料费 | 材料、直接产品/服务成本 | USD | 销货成本 | |
| 人工费 | 人工成本 | USD | 销货成本 | |
| 外部服务 | 外部服务/分包商 | USD | 销货成本 | |
| 供应品 | 耗材成本 | USD | 销货成本 | |
| 小型工具 | 小型工具 | USD | 销货成本 | |
| 销货成本 | 销货成本总计 | 毛利润 | ||
| 毛利润 | 毛利润 | 息税前利润 | ||
| 费用 | ||||
| 广告 | 广告、促销、营销费用 | USD | 费用 | |
| 汽车 | 汽车费用 | USD | 费用 | |
| 银行收费 | 银行服务费 | USD | 费用 | |
| 清洁费 | 清洁费 | USD | 费用 | |
| 捐款 | 捐款 | USD | 费用 | |
| 折旧 | 折旧费用 | USD | 费用 | |
| 折扣 | 采取的折扣 | USD | 费用 | |
| 订阅费 | 捐款和订阅费 | USD | 费用 | |
| 保险费 | 汽车保险、人寿、医疗 | USD | 费用 | |
| 利息支出 | 利息支出 | USD | 费用 | |
| 许可证 | 商业执照和许可证 | USD | 费用 | |
| 维修费 | 维护和修理 | USD | 费用 | |
| 餐费 | 膳食和娱乐 | USD | 费用 | |
| 商户费用 | 商家信用卡费用 | USD | 费用 | |
| 办公室 | 办公费用(电脑、邮资、快递、用品)。 | USD | 费用 | |
| 薪资税 | 薪资税 | USD | 费用 | |
| 专业费用 | 专业费用 | USD | 费用 | |
| 租金 | 租金支付 | USD | 费用 | |
| 工资 | 工资 | USD | 费用 | |
| 电话费 | 电话、传真 | USD | 费用 | |
| 旅行 | 旅行 | USD | 费用 | |
| 公用事业 | 公用事业 | USD | 费用 | |
| 费用 | 总费用 | 息税前利润 | ||
| 息税前利润 | 息税前利润 | 结果 | ||
| 其它收入 | ||||
| 利息收入 | 利息收入 | USD | 其它收入 | |
| 外汇利润 | 外汇利润 | USD | 其它收入 | |
| 其它收入 | 其它收入总计 | 结果 | ||
| 其它费用 | ||||
| 会计师咨询 | 会计师咨询 | USD | 其它费用 | |
| 外汇损失 | 外汇损失 | USD | 其它费用 | |
| 其它费用 | 其它费用总计 | 结果 | ||
| 结果 | 净利 (盈利(-) 亏损(+) ) | 盈利或亏损 | ||
| 00 | 差额应该是=0(空白单元格) | |||
| 客户/供应商登记 | ||||
| 客户 | ||||
| 客户-Redford | Redford 公司 | USD | 客户总计 | |
| 客户-Smith | John Smith | USD | 客户总计 | |
| 客户-Black | Simon Black | GBP | 客户总计 | |
| 客户总计 | 客户总计 | 客户 | ||
| 供应商 | ||||
| 供应商-Johnson | Johnson 公司 | EUR | 供应商总计 | |
| 供应商-Marble | Marble | USD | 供应商总计 | |
| 供应商-Taylor | Mary Taylor | USD | 供应商总计 | |
| 供应商总计 | 供应商总计 | 供应商 | ||
| 成本中心 | ||||
| 产品 | ||||
| .产品 A | 产品 A | USD | 产品 | |
| .产品 B | 产品 B | USD | 产品 | |
| .产品 C | 产品 C | USD | 产品 | |
| 产品 | 产品总计 | |||
| 项目 | ||||
| ;项目 A | 项目 A | USD | 项目 | |
| ;项目 B | 项目 B | USD | 项目 | |
| 项目 | 项目总计 | |||
| 部门 | ||||
| 分公司 | ||||
| :分公司 A | 分公司 A | USD | 分公司 | |
| :分公司 B | 分公司 B | USD | 分公司 | |
| 分公司 | 分公司总计 | |||
| 增值税码 | 摘要 | %税率 |
|---|---|---|
| 应交增值税 | ||
| S0 | 免征增值税销售 | |
| SE | 国外销售免税 | |
| S5 | 销售 5% | 5.00 |
| S10 | 销售 10% | 10.00 |
| SD5 | 销售折扣 5% | 5.00 |
| SD10 | 销售折扣 10% | 10.00 |
| 应退增值税 | ||
| P5 | 购买货物 5% | 5.00 |
| P10 | 购买货物 10% | 10.00 |
| PD5 | 购买折扣 5% | 5.00 |
| PD10 | 购买折扣 10% | 10.00 |
| I5 | 为投资或使用购买的物品 5% | 5.00 |
| I10 | 为投资或使用购买的物品 10% | 10.00 |
| ID5 | 用于投资或使用的购货折扣 5% | 5.00 |
| ID10 | 用于投资或使用的购货折扣 10% | 10.00 |
| 总计 |
| 记账本位币 | 货币 | 文字 |
|---|---|---|
| USD | EUR | 欧元 |
| USD | GBP | 英镑 |
公司 (含中英文报表)
在此文中
公司 (含中英文报表)
公司 (含中英文报表)
中小型企业进行会计管理的通用模板,多语言,多币种,自动核算当地增值税,中文做账自动生英文财务报表。
直接在网页中打开Banana财务会计+
无需任何安装,可以直接在您的浏览器上运行 Banana财务会计+。客制化您的模板,输入发生业务并将文件保存在您的电脑上。
在浏览器中打开模板 Open tutorial in WebApp模板文件
使用Banana财务会计软件,做专业的复式记账会计,一键生成资产负债表,损益表。多语言多汇率,使用中文做账一键点击生成外文报表。
创建您的文件
- 从该模板开始,创建一个新文件(模板编号+10680),使用在文中所解释的任何一种方式。
- 文件菜单→文件和账户属性命令,设置公司名称,会计期间及本位币。
- 文件菜单→另存为命令保存文件。以公司名称和年份作为文件名很有用。
例如“公司-2020.ac2”
文件和账户属性
- 账套
此标签可以编辑账套的信息,账套名称,开账日期和结账日期,以及记账本位币。 - 选项
此标签可以激活会计发生业务所需的功能。 - 地址
此标签中可以填入该会计账套的公司或个人信息,这些信息会做为本公司信息显示在给客户开具的发票中。 - 外汇
此标签中选择汇兑损益的会计科目代码。 - 增值税
此标签中选择应交增值税的会计科目代码。 - 其它
此标签中选择做账的语言和出报表的语言。 - 密码
此标签中设置账套密码。 - 文字
此标签中可以输入额外的信息,比如会计的名字。
编辑账户表
账户表格内显示有资产负债表及损益表的账户。
- 资产负债表显示所有资产账户的余额,即资产和负债。资产与负债之间的差额决定了个人资本。
- 损益表显示所有收入和费用的账户,它们的差额决定会计年度的损益状况。
所有的账户都可以根据您的需求进行客制化的编辑。例如,可以更改账号或摘要,可以在期初列内输入初始的余额,可以添加账户并且删除那些不需要的账户。
创建您的预算
在预算表格内,您可以输入指定年份的预估收入和费用。
- 列出每月费用和收入
例如,在办公室的租金中输入日期,重复,摘要,费用,借方账户,贷方账户和金额。
也可以会月收入执行相同的操作,并输入预估的收入。
输入会计发生业务
在会计发生业务表格中,输入实际的会计发生业务。
- 日期
- 摘要
- 借方账户
输入相对应的账户科目 - 贷方账户
输入相对应的账户科目 - 金额
对所有的会计发生业务执行同样的操作。
导入银行对账单
为了加快这些操作的进程,您可以导入银行对账单的数据并将其链接到数字收据。可以使用报表菜单→导入到账套命令。
报告和预算的比较
在输入会计发生业务后,程序将自动更新账户余额,您可以立即将其与预算余额进行比较。可随时查看并比较过去,现在和未来的会计数据。
模板预览
XX公司
本位币: USD
复式记账含外汇及增值税
| 总组 | 账号 | 摘要 | 货币 | 总和 | 所属组1 |
|---|---|---|---|---|---|
| BALANCE SHEET | |||||
| ASSETS | |||||
| 1000 | Cash | USD | 100 | ||
| 1010 | Post office current account | USD | 100 | ||
| 1020 | Bank 1 | USD | 100 | ||
| 1025 | Bank EUR | EUR | 100 | ||
| 1026 | Bank CNY | CNY | 100 | ||
| 100 | Current Assets | 1 | |||
| 1100 | Clients | USD | 1 | ||
| 110 | Total Clients | 1 | 1 | ||
| 1150 | Prepaid taxes | USD | 1 | ||
| 1200 | Inventory | USD | 1 | ||
| 1300 | Transitory assets | USD | 1 | ||
| 1310 | Machinery and applicances | USD | 1 | ||
| 1320 | Office furniture | USD | 1 | ||
| 1330 | Computer | USD | 1 | ||
| 1340 | Software | USD | 1 | ||
| 1350 | Car | USD | 1 | ||
| 1360 | Real Estate | USD | 1 | ||
| 1 | TOTAL ASSETS | 00 | 1 | ||
| LIABILITIES | |||||
| 2000 | Suppliers | USD | 2 | ||
| 200 | Total Suppliers | 2 | 1 | ||
| 2070 | Automatic VAT | USD | 2 | ||
| 2080 | VAT Revenue Authority | USD | 2 | ||
| 2100 | Bank loan c/c | USD | 2 | ||
| 2110 | Transitory liabilities | USD | 2 | ||
| 2120 | Start-up capital | USD | 2 | ||
| 2130 | Private account | USD | 2 | ||
| 2200 | Reserves | USD | 2 | ||
| 2300 | Profit or loss brought forward | USD | 2 | ||
| 230 | Profit or loss of the current year | 2 | 1 | ||
| 2 | TOTAL LIABILITIES | 00 | 1 | ||
| 1 | |||||
| PROFIT & LOSS STATEMENT | |||||
| REVENUE | |||||
| 4000 | Income from services | USD | 4 | ||
| 4100 | Income from sales | USD | 4 | ||
| 4200 | Other income | USD | 4 | ||
| 4600 | Exchange rate differences | USD | 4 | ||
| 4 | TOTAL REVENUE | 02 | |||
| EXPENSES | |||||
| 3000 | Purchase goods for resale | USD | 3 | ||
| 3100 | Salaries | USD | 3 | ||
| 3110 | Social contributions | USD | 3 | ||
| 3120 | Pension fund | USD | 3 | ||
| 3130 | Accident insurance | USD | 3 | ||
| 3140 | Health insurance | USD | 3 | ||
| 3200 | Rent | USD | 3 | ||
| 3210 | Upkeep machinery and appliances | USD | 3 | ||
| 3220 | Car expenses | USD | 3 | ||
| 3230 | Other insurances | USD | 3 | ||
| 3240 | Fees | USD | 3 | ||
| 3250 | Electricity | USD | 3 | ||
| 3260 | Office supplies | USD | 3 | ||
| 3270 | Telephone, Fax | USD | 3 | ||
| 3280 | Mailing fees | USD | 3 | ||
| 3290 | Publicity | USD | 3 | ||
| 3300 | Interest on bank loan | USD | 3 | ||
| 3310 | Bank and current account fees | USD | 3 | ||
| 3320 | Ammortize machinery and appliances | USD | 3 | ||
| 3330 | Ammortize real estate | USD | 3 | ||
| 3340 | Taxes | USD | 3 | ||
| 3 | TOTAL EXPENSES | 02 | 1 | ||
| 02 | Profit(-) Loss(+) from Profit & Loss Statement | 230 | 1 | ||
| 00 | Difference should be = 0 (blank cell) | ||||
| CLIENTS/SUPPLIERS REGISTER | |||||
| Clients | |||||
| 110001 | Company 1 | USD | 110A | ||
| 110002 | Company 2 | USD | 110A | ||
| 111003 | Company 3 | USD | 110A | ||
| 110A | Total Clients | 110 | 1 | ||
| Suppliers | |||||
| 20001 | Company 1 | EUR | 200A | ||
| 20002 | Company 2 | USD | 200A | ||
| 20003 | Company 3 | USD | 200A | ||
| 200A | Total Suppliers | 200 | 1 | ||
| COST AND PROFIT CENTERS | |||||
| Division car expenses | |||||
| .PET | Petrol | USD | CE | ||
| .INS | Insurance, other fees | USD | CE | ||
| .REP | Repairs | USD | CE | ||
| CE | Total Division car expenses | 1 | |||
| 增值税码 | 摘要 | %税率 |
|---|---|---|
| 说明 | ||
| 1 = 销项税 | ||
| 2 = 进项税 | ||
| 版本 : 2020/4/1 | ||
| 应交增值税 | ||
| S0 | 免征增值税销售 | |
| SE | 国外销售免税 | |
| S5 | 销售 5% | 5.00 |
| S10 | 销售 10% | 10.00 |
| SD5 | 销售折扣 5% | 5.00 |
| SD10 | 销售折扣 10% | 10.00 |
| 应退增值税 | ||
| P5 | 购买货物 5% | 5.00 |
| P10 | 购买货物 10% | 10.00 |
| PD5 | 购买折扣 5% | 5.00 |
| PD10 | 购买折扣 10% | 10.00 |
| I5 | 为投资或使用购买的物品 5% | 5.00 |
| I10 | 为投资或使用购买的物品 10% | 10.00 |
| ID5 | 用于投资或使用的购货折扣 5% | 5.00 |
| ID10 | 用于投资或使用的购货折扣 10% | 10.00 |
| 总计 | ||
| 基准货币 | 货币 | 文字 |
|---|---|---|
| USD | EUR | 欧元 |
| USD | CHF | 瑞士法郎 |
| USD | CNY | 人民币 |
外贸公司 (含中英文报表)
IFRS for SMEs – International accounting for SMEs
The IFRS for SMEs Accounting Standard is an international financial reporting standard developed by the International Accounting Standards Board (IASB) specifically for companies without public accountability.
It is based on full IFRS Accounting Standards but simplifies many recognition, measurement and disclosure requirements, making it more suitable for small and medium-sized entities.
In this section, you can learn about the structure and principles of IFRS for SMEs and find practical templates for preparing and reclassifying financial statements with Banana Accounting and Excel.
Key Features of IFRS for SMEs
- Easy to understand thank to the fact that accounts number follow the presentation.
- Groups numbering have the same sequence of the account numbers.
- Complete but not complex. It covers all the necessities SME, but don't have the complexity typical of accounting charts for large companies.
- Balance sheet and Income and Expenses.
- IFRS (International Financial Reporting Standard) SME compliant.
The Accounting chart structure and presentation is conform to the rule of the International Financial Reporting Standard for SME. - Easily adaptable.
- Fully tested.
This chart of account has been developed by the largest accounting association in Switzerland especially for SME. It has demonstrated to be easy to use and give all important results to companies owners and managers.
Global accounting templates for SME
The global accounting chart is the base for building the Banana Global accounting templates for Small and Medium Enterprise.
- Double entry accounting.
- Multi-currency accounting.
- The templates are available in many languages.
- It can be easily translated if necessary.
- There is a template with many languages together. So you can have the financial statements in different languages.
Suitable for many countries
Use it in case your country authorities do not mandate a specific accounting chart. Many countries require accounting reporting to be conform to the IFRS rules, but they do not mandate a specific accounting plan or numbering.
A company that desire to keep their accounting in a modern way can adopt this accounting chart and adapt to their own needs.
More information
- Introduction IFRS for SMEs
- Structure of IFRS for SMEs
- Reclassification IFRS with Banana
- Excel file structure
- Free Excel template for the IFRS-SMEs
Balance Sheet - Statement of Financial Position
In SME the cash position is very important, so the presentation start with the account 1000 for Cash.
The group 100 is for Cash and cash equivalents and 10 for Current assets.
- 1. Assets
- 10. Current assets
- 100. Cash and cash equivalents
- 106. Short-term Assets listed in Stock Exchange
- 109. Transfer accounts
- 110. Accounts receivable
- 114. Other short-term receivables
- 120. Inventories
- 130. Prepaid Expenses
- 14. Fixed Assets
- 140. Financial assets
- 148. Investments
- 150 . Tangible assets
- 160. Tangible fixed asset management
- 170. Intangible fixed assets
- 180. Capital or non-paid Foundation capital
- 10. Current assets
- 2. Liabilities and Equities
- 20. Short-term third party capital
- 200. Suppliers or creditors
- 210. Short-term onorous debts
- 220. Other short-term debts
- 230. Accruals and deferred income
- 24. Long-term third party capital
- 240. Long-term onorous debts
- 250. Other long-term debts
- 260. Provisions and similar statutory posts
- 28. Equity
- 280. Capital or capital of the foundation
- 290. Legal reserves
- 295. Legal reserve from profit
- 296. Optional reserves from profit
- 297. Profit / Loss from Balance Sheet
- 298. Treasury stock, shares, rights of investment (negative)
- 20. Short-term third party capital
Statement of Comprehensive Income
The Income and Expense account start with 3000 for revenues and 3 for the Revenue Groups.
The structure is sufficient detailed to satisfy the need of a statement presentation. Depending on the situation other accounts and groups can be added, to provide a better look of the situation.
- 3. Revenues from supplies and services
- 30. Net revenues from supplies and services
- 39. Change in inventories and Non-invoiced services
- 4. Costs for material, goods, services and energy
- E1. Gross operating result after deducting costs for materials and goods
- 5. Personnel expenses
- E2. Gross operating result after deducting personnel expenses
- 6. Other operating expenses, depreciation, value adjustments and financial results
- 60. Rental
- 61. Maintenance, repairs and replacement of tangible assets
- 62. Vehicle and transportation expenses
- 63. Insurance for damage of items
- 64. Energy and disposal costs
- 65. Administrative and IT costs
- 66. Advertising
- 67. Various costs for the financial year
- 6. Other operating expenses, depreciation, value adjustments and financial results
- E3. Operating result before depreciation and value adjustments, financial results and taxes (EBITDA)
- 68.Depreciation and value adjustments of fixed assets
- E4. Operating result before financial results and taxes (EBIT)
- 69. Financial costs and revenue
- E5. Operating result before taxes (EBT)
- 7. Non-operating items
- 8. Results of extraneous, extraordinary or unique character, or for other accounting periods
- E6. Profit or loss before taxes
- 89. Direct taxes
- E7. Annual profit or loss
Full accounting Chart
| Section | Group | Account | Description |
| * | BALANCE SHEET | ||
| 1 | ASSETS | ||
| 1000 | Cash on hand | ||
| 1020 | Bank account | ||
| 100 | Cash and cash equivalents | ||
| 1060 | Bonds and stocks | ||
| 106 | Short-term Assets listed in Stock Exchange | ||
| 1090 | Internal transfers | ||
| 1091 | Transfer account for salaries | ||
| 1099 | Amounts to be clarified | ||
| 109 | Transfer accounts | ||
| 1100 | Due from Clients or Debtors | ||
| 1109 | Provision for Doubtful Debts | ||
| 110 | Accounts receivable | ||
| 1140 | Advances and loans | ||
| 1176 | Withholding tax | ||
| 1180 | Receivables from social insurances and social security institutions | ||
| 1188 | Source tax | ||
| 1190 | Various short-term receivables | ||
| 1199 | Securities | ||
| 114 | Other short-term receivables | ||
| 1200 | Goods for resale | ||
| 1210 | Raw materials | ||
| 1220 | Auxiliary material | ||
| 1230 | Consumables | ||
| 1260 | Finished products | ||
| 1270 | In-process products | ||
| 1280 | Non-invoiced services | ||
| 120 | Inventories | ||
| 1300 | Prepaid expenses | ||
| 1301 | Accrued income | ||
| 130 | Prepaid Expenses | ||
| 10 | Current assets | ||
| 1400 | Bonds and stocks | ||
| 1440 | Loans | ||
| 1460 | Loan to share-holder | ||
| 140 | Financial assets | ||
| 1480 | Investments | ||
| 148 | Investments | ||
| 1500 | Machinery | ||
| 1510 | Office furniture and equipment | ||
| 1520 | Office machinery, information and communication technology | ||
| 1530 | Motor vehicles | ||
| 1540 | Tools and equipment | ||
| 150 | Tangible assets | ||
| 1600 | Commercial buildings | ||
| 160 | Tangible fixed asset management | ||
| 1700 | Patents, know-how, licences, rights and development | ||
| 1710 | Brands | ||
| 1712 | Models | ||
| 1770 | Goodwill | ||
| 170 | Intangible fixed assets | ||
| 1850 | Share capital, rights not paid or non-paid Foundation capital | ||
| 180 | Capital or non-paid Foundation capital | ||
| 14 | Fixed Assets | ||
| 1 | Total Assets | ||
| 2 | LIABILITIES | ||
| 2000 | Suppliers or creditors | ||
| 2030 | Deposits received | ||
| 200 | Suppliers or creditors | ||
| 2100 | Due to banks short/term | ||
| 2120 | Financial leasing commitments | ||
| 2140 | Other onerous debts | ||
| 210 | Short-term onorous debts | ||
| 2206 | Withholding tax | ||
| 2208 | Direct taxes | ||
| 2210 | Other short-term debts | ||
| 2260 | Due to share-holders | ||
| 2261 | Dividends | ||
| 2270 | Social insurances and social security institutions | ||
| 2279 | Source tax | ||
| 220 | Other short-term debts | ||
| 2300 | Accrued expenses | ||
| 2301 | Next year's revenues collected | ||
| 2330 | Short-term provisions | ||
| 230 | Accruals and deferred income | ||
| 20 | Short-term third party capital | ||
| 2400 | Due to banks | ||
| 2420 | Financial leasing commitments | ||
| 2430 | Debenture loans | ||
| 2450 | Loans | ||
| 2451 | Mortgage | ||
| 240 | Long-term onorous debts | ||
| 2500 | Other long-term debts (non-onorous) | ||
| 250 | Other long-term debts | ||
| 2600 | Provisions | ||
| 260 | Provisions and similar statutory posts | ||
| 24 | Long-term third party capital | ||
| 2A | Third party capital | ||
| 2800 | Share capital, rights, foundation capital | ||
| 280 | Capital or capital of the foundation | ||
| 2900 | Legal reserves | ||
| 2940 | Revaluation reserves | ||
| 290 | Legal reserves | ||
| 2950 | Legal reserve from profit | ||
| 295 | Legal reserve from profit | ||
| 2960 | Optional reserves from profit | ||
| 296 | Optional reserves from profit | ||
| 2970 | Profit / Loss carried forward | ||
| 29A | Profit / Loss for the year | ||
| 297 | Profit / Loss from Balance Sheet | ||
| 2980 | Treasury stock, shares, rights of investment (negative) | ||
| 298 | Treasury stock, shares, rights of investment (negative) | ||
| 28 | Equity | ||
| 2 | Total liabilities | ||
| * | PROFIT & LOSS STATEMENT | ||
| 4 | |||
| 3000 | Earnings from own products | ||
| 3200 | Earnings from resale | ||
| 3400 | Earnings from services rendered | ||
| 3600 | Other revenues and services | ||
| 3710 | Own consumption | ||
| 3800 | Decrease in revenues | ||
| 3805 | Losses on accounts receivable, credit variation | ||
| 30 | Net revenues from supplies and services | ||
| 3900 | Change in inventories of in-process products | ||
| 3901 | Change in inventories of finished products | ||
| 3940 | Non-invoiced services variations | ||
| 39 | Change in inventories and Non-invoiced services | ||
| 3 | Revenues from supplies and services | ||
| 4000 | Raw materials | ||
| 4200 | Expenses for goods for resale | ||
| 4400 | Third party expenses | ||
| 4500 | Energy consumption for production | ||
| 4900 | Reduction of costs | ||
| 4 | Costs for material, goods, services and energy | ||
| E1 | Gross operating result after deducting costs for materials and goods | ||
| 5000 | Salaries | ||
| 5700 | Contribution to old age insurance and unemployment | ||
| 5710 | Family equalization fund | ||
| 5720 | Contribution to pension funds | ||
| 5730 | Contribution to accident insurance | ||
| 5740 | Contribution to voluntary daily benefits insurance | ||
| 5790 | Source tax | ||
| 5800 | Other personnel expenses | ||
| 5810 | Training of personnel | ||
| 5820 | Travel and entertainment expenses effective | ||
| 5830 | Travel and entertainment expense allowance | ||
| 5900 | Temporary staff | ||
| 5 | Personnel expenses | ||
| E2 | Gross operating result after deducting personnel expenses | ||
| 6000 | Rental | ||
| 6040 | Cleaning of facilities | ||
| 60 | Rental | ||
| 6100 | Maintenance, repairs and replacement of tangible assets | ||
| 6105 | Leasing costs tangible assets | ||
| 61 | Maintenance, repairs and replacement of tangible assets | ||
| 6200 | Repairs | ||
| 6210 | Fuel | ||
| 6220 | Car insurance | ||
| 6260 | Car leasing and rental | ||
| 6270 | Car costs - private part | ||
| 6282 | Transportation expenses | ||
| 62 | Vehicle and transportation expenses | ||
| 6300 | Insurance for damage of items | ||
| 63 | Insurance for damage of items | ||
| 6402 | Electricity | ||
| 6410 | Heating expenses | ||
| 6430 | Water | ||
| 6460 | Garbage | ||
| 64 | Energy and disposal costs | ||
| 6500 | Office supplies | ||
| 6503 | Technical magazines, newspapers, periodicals | ||
| 6510 | Telephone / internet | ||
| 6511 | Hosting at third-party | ||
| 6513 | Postal charges | ||
| 6570 | IT charges including leasing | ||
| 6580 | Licenses and updates | ||
| 6583 | Consumables | ||
| 65 | Administrative and IT costs | ||
| 6600 | Advertising | ||
| 6642 | Gifts to customers | ||
| 66 | Advertising | ||
| 6700 | Various costs for the financial year | ||
| 67 | Various costs for the financial year | ||
| 6 | Other operating expenses, depreciation, value adjustments and financial results | ||
| E3 | Operating result before depreciation and value adjustments, financial results and taxes (EBITDA) | ||
| 6800 | Depreciation and value adjustments of fixed assets | ||
| 68 | Depreciation and value adjustments of fixed assets | ||
| E4 | Operating result before financial results and taxes (EBIT) | ||
| 6900 | Costs for bank interest | ||
| 6940 | Bank costs | ||
| 6950 | Financial revenue | ||
| 69 | Financial costs and revenue | ||
| E5 | Operating result before taxes (EBT) | ||
| 7000 | Non-operating revenue | ||
| 7010 | Non-operating costs | ||
| 7500 | Corporate real estate revenues | ||
| 7510 | Corporate real estate costs | ||
| 7 | Non-operating items | ||
| 8000 | Extraneous costs | ||
| 8100 | Extraneous revenue | ||
| 8500 | Extraordinary, unique costs or costs relating to other accounting periods | ||
| 8510 | Extraordinary, unique revenue or revenue relating to other accounting periods | ||
| 8 | Results of extraneous, extraordinary or unique character, or for other accounting periods | ||
| E6 | Profit or loss before taxes | ||
| 8900 | Direct taxes | ||
| 89 | Direct taxes | ||
| E7 | Annual profit or loss |
Definition and principles of IFRS for SMEs
The IFRS for SMEs Accounting Standard is an international financial reporting standard developed by the International Accounting Standards Board (IASB) for entities without public accountability.
It provides a simplified framework based on full IFRS Accounting Standards, designed to make financial statements transparent, reliable and comparable while reducing the reporting complexity for small and medium-sized entities.
IFRS Purposes
The main purpose is to create a common accounting framework for most companies operating within the European Community, offering the advantage of greater simplicity and transparency in relation to the balance sheets and financial information.
The objectives are characterized in various aspects as follows:
Transparency:
to provide stakeholders with clear and detailed information on the company's financial status and performance.
Reliability:
to create financial reports that correspond to the business reality and are trustworthy.
Uniformity:
to report financial information that is comparable on a global scale.
Relevance:
to ensure that important information is provided to potential investors and other stakeholders.
Fundamental Principles of IFRS for SMEs
The characteristics of IFRS standards are based on principles as explained below:
Full Disclosure
All relevant information must be fully disclosed.
Substance over Form Principle
Transactions must be accounted for and presented based on their economic substance and reality, not just their legal form.
Principle of Prudence
Uncertainties and risks must be duly considered.
Fair Value Measurement
Numerous balance sheet items must be measured at their fair value, rather than at their historical cost.
Qualitative characteristics of financial information
Understandability
The presentation of financial statement information should be understandable in terms of the company’s commercial and economic activities. This principle does not allow for the omission of important information as it would become difficult to understand for some users.
Comparability
Information about an entity is useful if it can be compared with similar information from other entities. This characteristic allows stakeholders to identify and understand similarities and differences in business accounting realities.
Verifiability
Verifiability helps ensure a faithful representation of the company’s accounting and financial information. Quantified accounting information does not necessarily have to be an exact estimate to be verifiable.
Timeliness
Timeliness means having information available in time to make decisions. In this sense, the older the information, the less useful it is. There are exceptions, it is emphasized that for some information it can also be less timely since there is an evaluation over a longer period of time to study and identify trends.
References:
Structure of IFRS for SMEs Financial Statements
According to Section 3.17 of the IFRS for SMEs Accounting Standard, a complete set of financial statements includes:
- a Statement of Financial Position;
- a Statement of Comprehensive Income, or an Income Statement and a separate Statement of Comprehensive Income;
- a Statement of Changes in Equity;
- a Statement of Cash Flows;
- Notes to the Financial Statements.
References
Statement of Financial Position
The Statement of Financial Position presents an entity’s assets, liabilities and equity at the reporting date.
Assets and liabilities are generally classified as current or non-current. An asset is normally classified as current when it is expected to be realised, sold or consumed during the normal operating cycle, is held for trading, or is expected to be realised within twelve months after the reporting date.
A liability is normally classified as current when it is expected to be settled during the normal operating cycle, is held for trading, or is due to be settled within twelve months after the reporting date.
When a presentation based on liquidity provides more reliable and relevant information, assets and liabilities may instead be presented in order of liquidity.
Income statement
The income statement is the representation of the profit and loss account and is classified according to the by nature of expense method.
The classification by nature is one of the options available from the IFRS for SMEs, and since it is the simplest and most flexible for different business realities, it was decided to implement this approach.
The concept is that costs are aggregated according to their nature, such as depreciation, purchases of materials, transportation costs, etc.
There is also the classification by cost destination, where costs are distinguished between cost of goods sold and other costs, which provides more meaningful information but requires a considerable degree of discretion on the part of the financial statement preparer.
Statement of changes in equity
The statement of changes in the equity of a company between two financial years reflects the variations in the net equity due to the increase or decrease of its net assets for the period or the wealth generated, based on the specific valuation criteria implemented and indicated in the financial statements.
Statement of Cash Flows
The IFRS for SMEs stipulates that entities must categorize their transactions into three distinct activities:
- Operating
- Investing
- Financing.
It further permits entities to present their operating cash flows using either the direct or indirect method. Ultimately, the framework’s goal is to furnish decision-useful information to users, aiding them in making informed economic choices.
Notes
The notes to the financial statements represent a fundamental part of financial reporting under IFRS for SMEs. They provide additional and detailed information that integrates and explains the data presented in the main financial statements.
Furthermore, they play a crucial role in ensuring the transparency and completeness of financial reporting, allowing users of the financial statements to fully understand the company's financial position, performance, and cash flows.
In conclusion, the notes to the financial statements are therefore an essential tool for improving the transparency and comparability of financial reporting at an international level.
Reclassification IFRS with Banana
在此文中
Reclassification IFRS with Banana
Reclassification IFRS with Banana
模板文件
Introduction
On this page, there is a brief explanation of the templates created with the Banana accounting software and how to use them to print the income statement and balance sheet report according to IFRS standards for SMEs.
At the bottom of the page are links to download the templates.
Template IFRS SME
The template file is set up with the IFRS SME chart of accounts in which the Statement of financial position, Income statement and Statement of changes in equity are present.
This file refers to the document "Reclassification IFRS SME" to print the report according to the IFRS SME setting, with the use of the financial statements embellished by groups.
For more information on financial statement enhanced balance sheet with groups:
- Video of how-to do enhanced balance sheet with groups.
- Documentation about enhanced balance sheet with groups.
- Documentation about reclassification of financial statement and Income statement.
Reclassification IFRS SME
The document contains the basic settings to print the page layout (document title, company master data), amounts, totals, subtotals of the Statement of Financial Position and Income Statement accounts.
The accounts will be printed even if the amount is zero. If you want to change the setting of this printout or the style you can do so within this file.
Report creation with Statement of financial position and Income statement
To create a report with the Statement of Financial Position and Income Statement documents, follow the next steps:
- Open the template file and record all case-specific accounting transactions.
- Click on Reports -> Enhaced balance sheet with groups
- Enter the important data relating to the reference company (e.g. document name, company master data) in the Page-Header and Footer section.
- You can make other settings by reading the details on Banana's site on the enhanced balance sheet.
- Click OK.
At the end of the process a new file will be opened with the Statement of Financial Position and Income Statement inside.
Download IFRS SME per Banana
We make the models available without any liability, as stipulated in our Terms and Conditions of Use.
Excel file structure
This page explains the structure and logic of the IFRS for SMEs Excel template and how to use its different worksheets.
The examples and figures are provided for illustrative purposes only. The amounts shown do not represent actual financial data.
Reference documentation
For the creation of the accounting structure within the Excel file, the indications of the documentation related to the IFRS standards for SMEs were followed.
Specifically, the documentation is:
- Accounting principles, notes and other: "Exposure Draft IFRS for SMEs Accounting Standard" of September 2022".
- The presentation of the accounts and the explanatory notes: "IFRS Taxonomy Illustrated IFRS Accounting Taxonomy 2023".
Description structure file
The Excel template is divided into ten main parts:
- General information
- Financial Statement
- Income Statement
- Financial Statement detailed
- Income Statement detailed
- Statement of changes in equity
- Cash flow indirect
- Notes of financial statements
- Notes of income statement
- Notes of cash flow statement.
In order to have a complete set of IFRS financial statements for SMEs, it is necessary to complete the sheets on General information, Financial statement and Notes of financial statements, Income statement and Notes of income statement, Statement of changes in equity and Cash flow indirect and Notes of cash flow statement.
The Financial Statement detailed and Income Statement detailed sheets, are an alternative to the compilation procedure specified above, as they integrate the entire aspect of the Financial Statement and Income Statement, with all accounts detailed by the notes, having a direct view of the composition and structure of an account with the notes.
Organization of the file
File content
The file contains seven fields:
- Main field.
- Main account.
- Sub-category of the main account.
- Code.
- Formula.
- Note.
- Account amount.
In the main field, you specify the name of the main account, the document reference and generic company information.
The main account is the name of the main account.
The sub-category of the main account can only be displayed if the Statement Financial detailed and Statement Income detailed sheet is used. It is an account taken from the notes and serves to detail the structure of an account, as required in the IFRS notes for SME.
The code is used for Banana's accounting model and serves to identify the account.
The formula is applied for account totals and subtotals.
The note is account-specific and is entered for some accounts as per the IFRS documentation for EMS.
The account amount is a number to two decimal places without currency indication.
Some fields are not editable as they are an essential part of the file structure. The only part to be changed are the amounts to be entered for the various accounts and the descriptions in the note sheet.
The legend below summarises what the fields correspond to and which are and are not editable.
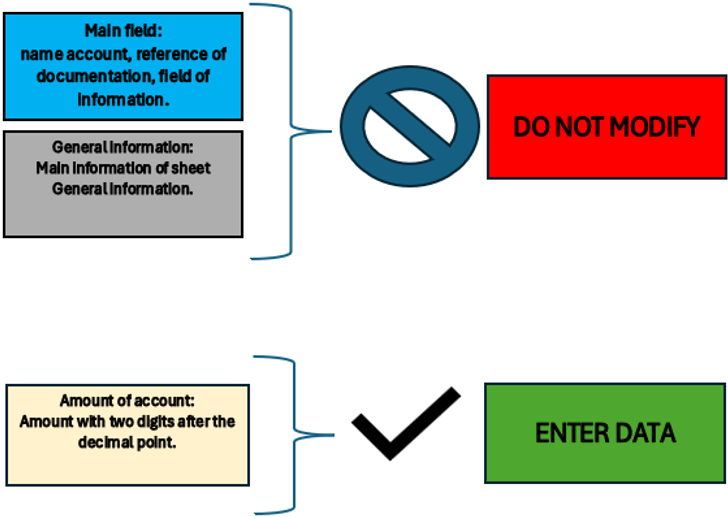
Figure of Excel in the sheet Legend
In the General information sheet, the essential information required by IFRS for SME is entered.
The essential information is useful to understand the biographical data of the company, the relevant accounting period, the currency used, the main activities and the content of this file, which is the complete structure of the financial statement.
Certain information such as company name, company name, domicile and accounting period is reported on all sheets specifically for the Identifying information of company.
General information
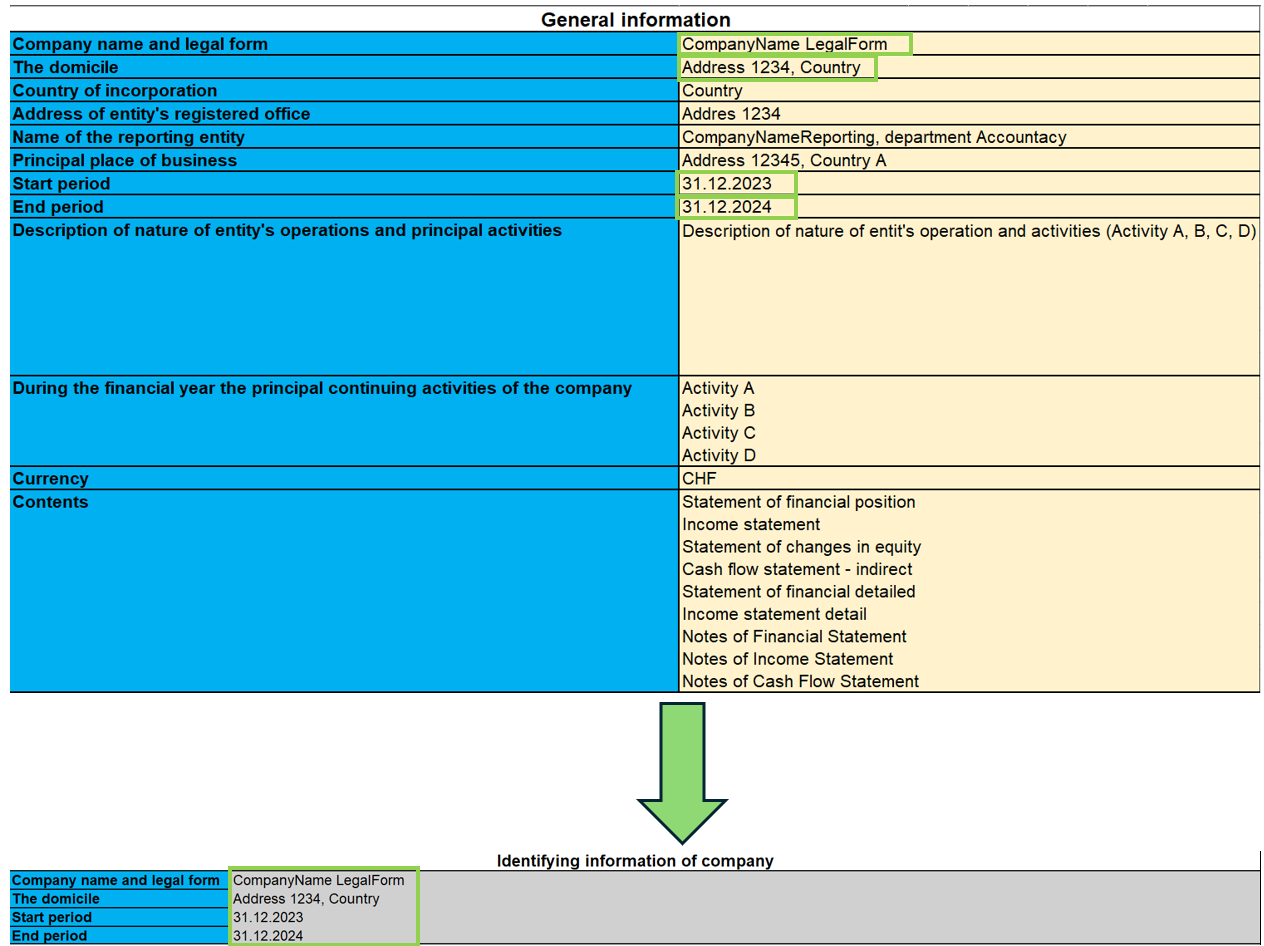
As shown in the image, the information entered on this sheet is carried over to all sheets, so that the company can be identified on each IFRS document, such as: the full name of the company, the address and registered office, and the beginning and end accounting year to be taken into account for accounting purposes.
Statement of financial position
The Statement of Financial Position presents the entity's assets, liabilities and equity for the current and comparative reporting periods.
In this part you are required to enter the budget amounts in the specific accounts. Totals and subtotals are calculated automatically by the formulas.
It should also be noted that for some accounts it is mandatory to complete the Notes. This is done by entering the amounts and other descriptive notes in the ‘Notes of Finacial Statement’ sheet.
If an account has notes, its amount for the last year refers to the corresponding cell of the account total put in the notes, so it is necessary to fill in the amounts in the notes first.
For the notes, there is also the possibility of consulting the documentation indicated in the ‘Reference documentation’ field, specifying the page and section where the information on the notes can be found.
Finally, there is a final check part to see if the total assets and liabilities are equal.
Modalities of use
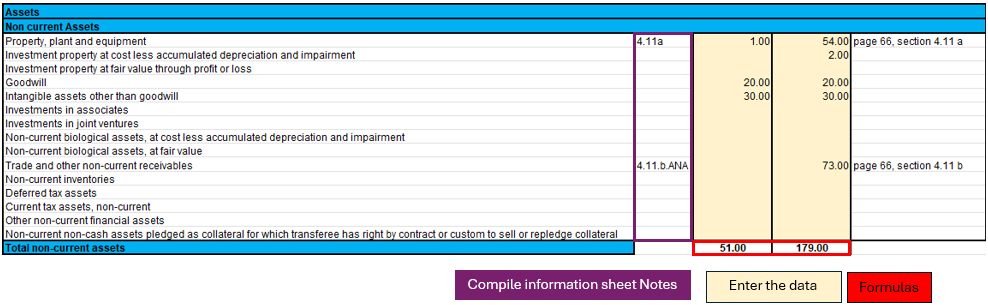
In the picture shown, a part of the Statement of Financial Position is selected as an illustrative example to guide the user. There are three highlighted parts in the image:
- Notes.
- The formulas.
- The data to be filled in.
Each part has its own specific function and in some cases the data are directly linked to each other.
Specifically, if an account has notes, it means that in the ending balance (31.12.xx) there will be the total of the amount calculated in the ‘Notes of financial statement’ sheet. This implies that in order to change that amount, one must fill in the account data on the "Notes of financial statement" sheet.
In this sheet one must therefore:
- Verify that the account is not linked to notes and enter the amount in the account.
- If there are notes, then only the ‘Notes of financial statement’ part of the sheet must be filled in.
The formulas integrated in this sheet will make the totals and subtotals of the accounts in the Statement of financial position.
Income Statement
The income statement is presented according to the classification ‘by nature of expense’.
This classification is an aggregation of costs according to their nature (e.g. depreciation, purchase of materials, transport costs, salaries, advertising costs, etc.) and are not allocated according to their purpose within the company.
The implementation of this classification was decided upon because it is simple and widely applicable for SMEs. The other classification was according to costs by function, where a distinction was made between costs of sales versus other costs (e.g. distribution costs or administrative costs) and this representation requires a considerable degree of discretion on the part of the end user.
As previously done for the Financial Statement, there are the amounts to be entered while the totals are already calculated by means of the formulas applied in the sheets.
In addition, a further breakdown has been made for EBIT (earnings before interest and tax) and EBT (earnings before interest).
Modalities of use
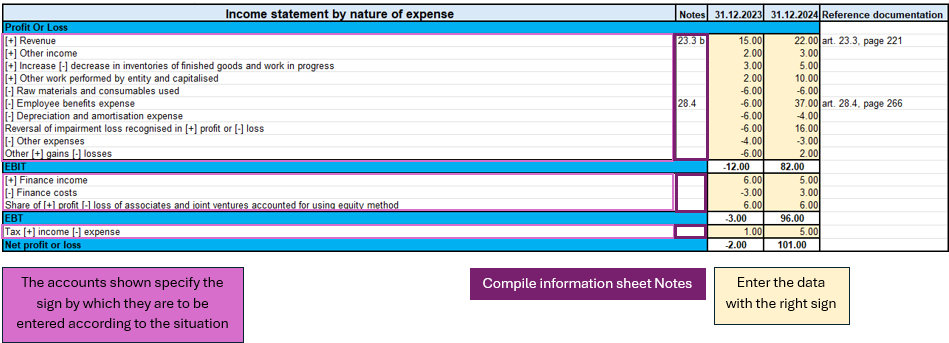
This figure highlights the important parts of the income statement.
Looking at the accounts, there are indications of the signs (+/-) to be used in the various circumstances, which implies that for accounts that have both positive and negative signs, there is an assessment of the positive or negative impact of that amount on the result of the income statement.
As previously seen in the ‘Statement of financial position’, there are also notes to be entered in the relevant sheet ‘Notes of income statement’ in order to be able to correctly define the amount, as the latter depends on the total in the notes.
In summary, what you need to do on this sheet are the following steps:
- Evaluate the circumstances of the account with both positive and negative sign and understand whether you are in a situation where it has a positive or negative impact on the result.
- Verify that the account is not linked to notes and enter the corresponding amount with the correct sign.
- If the account is correspondent with the notes, then only the ‘Notes of income statement’ sheet must be completed.
Statement Financial detailed
This document differs from the Statement of financial position in that there is more detail on the accounts. The official presentation of the accounts can be found in the ‘Statement of financial position’ sheet in terms of how the accounts are summarised; in this sheet, however, we have more detail, with the aim of avoiding filling in the notes directly in the specific sheet. The use of this sheet excludes the use of the ‘Statement of financial position’ sheet because they refer to the same notes.
The main difference is that not only the main accounts required as a presentation by IFRS for EMS are shown, but they are detailed in sub-categories of accounts that are the same as those found in the notes, so that using this document one can avoid filling in the notes, using only the sub-categories of accounts, except in some cases where the account requires descriptive textual type details, without using calculation formulas or amounts. For this reason, not all parts of notes are integrated, as some accounts require a textual type description.
To distinguish the main accounts from the sub-categories of accounts, the main categories are coloured dark, while the light categories are the accounts related to the notes.
If there are no subcategories of accounts (coloured light), then it is sufficient to go to the specific Notes of Statement or financial position sheet.
Modalities of use
In this image, you can see four essential parts of the document:
- Main accounts.
- Subcategories of the main accounts.
- Notes.
- The amounts to be entered.
- The formulas.
This part, there is more detail only if an account has notes, otherwise it is the same as the Statement of Financial Position. What requires attention is the verification of an account if it is an account with notes and has no sub-categories of accounts, if you find yourself in this situation then it means that the account requires an additional textual description to define some peculiarities in the ‘Notes of financial statement’ sheet.
On the other hand, for accounts that have notes but also account sub-categories, only the amounts of the sub-categories of the specific account need to be filled in. In this way, having filled in all the amounts of the sub-categories of the account, the formulas applied to the sub-categories will calculate the subtotals and the total of the main account.
So to summarise, the procedure for filling in this sheet is:
- I enter the amounts in the main accounts if there are no notes to refer to.
- If the main account has notes, I check that it has sub-accounts, if it does not, then I go to the ‘Notes of financial statement’ sheet and fill in the text description.
- If, on the other hand, the main account has notes and has the subcategories of accounts, then I only fill in the amounts of the subcategories.
In this example image in the Equity part, a case is illustrated where an account has notes but no account subcategories, which requires a textual description in the ‘Notes of financial statement’ sheet, and a normal case where there are notes with account subcategories.
Income statement detailed
Income statement detail is based on the same logic as the Statement of financial detailed, with the aim of providing a single document for its function, detailed by the accounts of the notes, without having to fill in the Notes of income statement.
There are the main accounts and when there are notes, they are detailed by the sub-categories of accounts that are part of them.
Modalities of use
As illustrated in the figure above, there are four equal parts to the ‘Statement of financial detailed’ sheet with the same logic.
The only difference is that there are no descriptive notes, so all accounts with notes are already with their sub-categories without requiring additional compilation on the ‘Notes of income statement’ sheet.
Therefore, to summarise, it is essential to follow these steps:
- Enter the amounts of the main accounts if they have no notes.
- If the main account has notes, enter the amounts only in the subcategories of the account.
The Statement of Changes in Equity
The Statement of Changes in Equity reflects changes in equity.
This part provides insight and transparency into decisions and their effect on the value of equity. It is also a useful tool for investors and other stakeholders to understand how the company has generated and utilised equity capital.
Modalities of use
In the sheet ‘Statement of changes equity’ as shown in the image, there is one part to pay attention to.
The first is the evaluation of the change in the account item, whether it increases or decreases, and then according to the sign (+/-) the amount must be written with the correct sign.
Unlike other documents, this one does not require notes.
So the process of completing the document is:
- Evaluate the account change and follow the indications on the sheet on the sign to be taken in the various circumstances (increase or decrease in the account).
- Enter the amount with the correct sign.
Cash flow indirect
The Indirect Cash Flow Statement is divided into four main sections:
1. Cash flow from operating activities
2. Cash flow from investing activities
3. Cash flow from financing activities
4. Net cash flow.
The document is independent of the other sheets, so you have to do your own calculations to deduct the various amounts to be included in the cash flow items.
The accounts are taken from the IFRS for SME taxonomy, first there are the profit or loss adjustments and then the operating activities are calculated.
Investing activities are characterised by the purchase or sale of fixed assets such as equipment, real estate, joint venture participations and others.
Cash flows from financing activities are related to the company's sources of financing, such as leasing, share issues, debt repayments or financing income. There is also the payment of dividends to shareholders.
In the last part of cash flow there are some clarifications to be made. The net change in cash is assessed in two steps, the first is calculated before the effect of the exchange rate change and the second after this change. In addition, as a form of control, the change in liquidity is also calculated, showing the changes in the period of activity, by calculating the difference between the initial and final liquidity balance.
Modalities of use
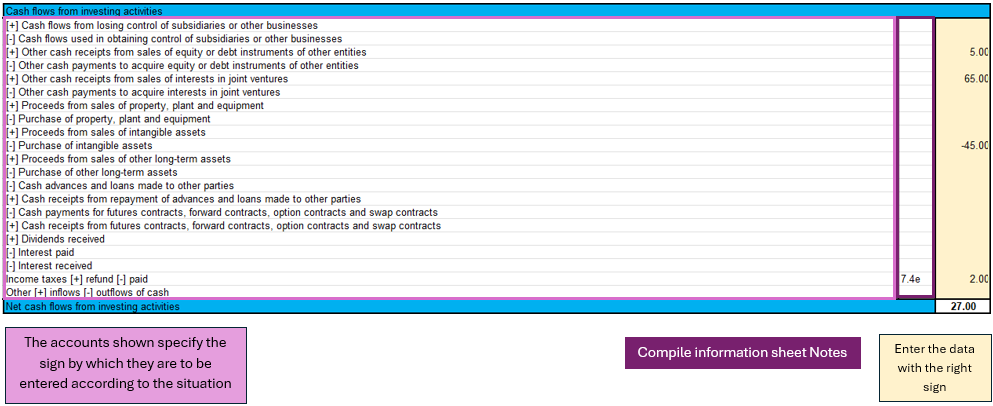
As shown in the figure of the cash flow for investing activities, three main components can be identified:
- The main accounts show the sign depending on the situation.
- For some accounts, the notes of cash flow statement are required.
- Entering the amounts requires attention with respect to the sign.
In the cash flow statement, reasoning on the implications of the balance sheet and profit and loss accounts is required in order to conclude which amount to enter in the specific item of the cash flow statement, so the conclusion depending on which cash flow statement has been analysed, could be an increase or decrease of an asset, a payment for property purchase, payment of dividends to shareholders,...
There is no sheet for this purpose, the user must reason with the amounts available, entered in the balance sheet and profit and loss account, and come to his own conclusions.
Next, having an amount, one must distinguish the situation as indicated in the sheet, in order to enter the amount with the correct sign.
Finally, in the event that it is required, fill in the notes of cash flow statement with the specific amounts in the case.
Notes
The notes are divided by the three IFRS documents:
- Notes to the Financial Statement.
- Notes of the Income Statement.
- Notes to the Cash Flow Statement.
As mentioned in the introductory section, the notes serve to supplement the information taken from the financial documents.
The note sheet contains four essential parts: the note code, reference account, amount and notes (text).
The note code is the reference for each part of the documents that serves to understand in which account the notes are to be completed.
The account represents the account taken from the document (Financial Statement, Income Statement, Cash Flow) to be detailed in the notes.
The amount is singular for the detailed account and is not always required because in some cases only a textual description is needed.
Notes as text are necessary if there are cases where only a description or more detailed customisation is required to explain an account.
Modalities of use
Case for the Financial Statement
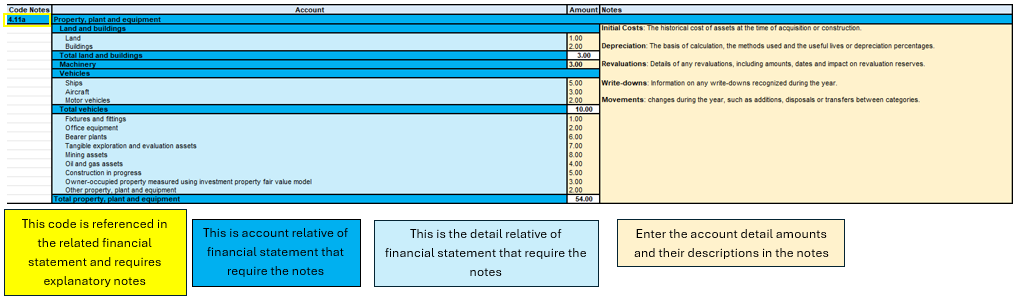
Figure of Excel in the sheet Notes of financial statement
In this image, four main components can be seen, the account reference code, the account, the detail grouping the sub-categories of accounts, the amounts to be entered with any textual notes.
The starting point for completing this sheet is then the financial statement, where we list which accounts need more detail, and then move on to complete the information in the notes sheet.
The data entry part concerns the amount of the detail account and any descriptive text.
The account totals and subtotals are calculated from the formulas, the account total is shown on the main sheet of the financial statement, so it is essential that if an account needs notes, it is only on the notes sheet.
Case for the Income Statement
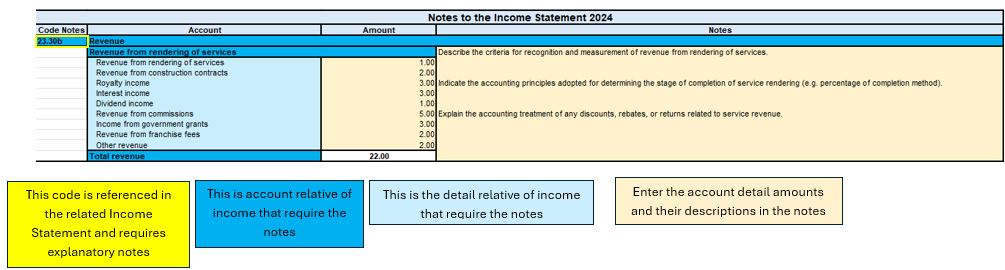
Figure of Excel in the sheet Notes of income statement
As seen above, the structure does not change for the Income statement notes. The main parts are always the same, as also for the cash flow notes.
To summarise therefore in this process one must:
- Depending on which sheet you are compiling, you must check that the analysed account of the financial statement, income statement or cash flow note is there.
- All the necessary data and information must be filled in.
- If there is a sub-account in the notes that is not needed or not used, you can simply leave it blank or enter a zero amount.
Objectives of the file
The process of creating the IFRS structure for SMEs took the official documentation and reconstructed a structure in the Excel template, with the aim of allowing the user to follow the IFRS reporting logic by entering the main information in the parts of the file.
The basic characteristics of such a file is the completeness of the document by having all the main parts required for IFRS, the usefulness of preferring the most widely used models that are more suitable for several companies, and excluding other more specialised models only in certain contexts.
The template provides a structured financial overview and helps users organize financial information according to the reporting logic of IFRS for SMEs.
In addition, the aim of IFRS for SMEs is to improve the comparability of financial data between different companies, to facilitate the analysis and interpretation of financial results by stakeholders outside the company, and to promote the adoption of IFRS for SMEs by providing a practical and accessible tool.
Free Excel template for the IFRS-SMEs
We make the model available without liability as per our Terms and Conditions of Use.
Cash Flow Statements and Financial Ratios [BETA]
在此文中
Cash Flow Statements and Financial Ratios [BETA]
Cash Flow Statements and Financial Ratios [BETA]
Advanced financial reporting and charts for your double entry accounting, inclusive of Cash Flow Statement, standard financial ratios, Dupont analysis and Altman index. Compare historical data over more years and forecast data with current year.
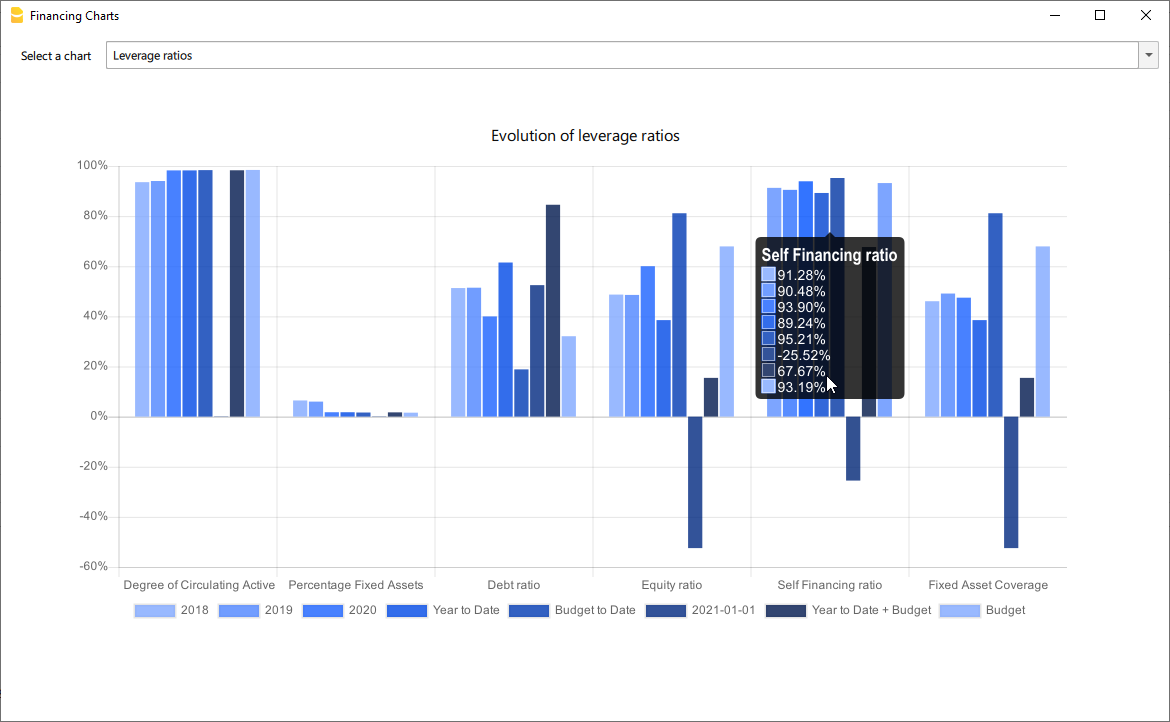
Easily add advanced financial reporting and charts to your existing double entry accounting. It works with any accounting plan, the first time you enter your groups/accounts in the settings dialog, and then all calculations and reporting will be done automatically. This extension is available in Banana Accounting Plus only with the Advanced plan. Update now!
How to start
First time setup:
- Open Banana Accounting Plus
- Open your existing Banana double entry accounting file.
- Go to the Extensions menu → Manage Extensions... command and install the Cash Flow Statements and financial Ratios extension.
- Map you accounting plan.
- Extensions menu → Cash Flow and Financial Ratio → Settings.
- Under Grouping enter the groups you have in your accounting plan in the predefined groups.
The extension uses a standard, simplified Balance and Profit and loss structure, that allows to automatically calculate the Financial Ratios. - Click OK to verify your data.
Check the Ignore warnings/errors if you want to save the data and complete the grouping later.
- Add information to some special transactions (dividends, change in reserve, disinvestment, investments) they can be identified for the Cash Flow Statements.
Run the reports (at any time).
- Open your Banana double entry accounting file.
- Menu Extensions → Cash Flow and Financial Ratio
- Financial Charts
- Financial Reports
Available reports and charts
- Reclassification and checks
- Reclassified balance sheet
- Reclassified Profit and Loss Statement
- Control sums
- Cashflow Statement
- Cash Flow statement based on the indirect method.
- Cash Flow ratios.
- Financial ratios and analysis
- Liquidity ratios:
- Financing ratios
- Profitability ratios
- Efficiency ratios
- Dupont Analysis
- Altman index
- Charts
- Evolution of ratios over time
- Evolution of the Reclassified balance sheet
- Evolution of the elements of the Reclassified Profit and Loss Statement.
Prerequisites
In order to be able to use this extension you have to:
- Use Banana Accounting Plus with the Advanced plan. We recommend using the Dev-Channel, some features or functionality present in the insider version may not yet be accessible in the regular version of Banana.
- Open a Double-entry accounting file.
It is important that the various accounting years files included in the analysis have the chart of accounts set up in the same way, at least as far as references to groups are concerned.
For example, if I want to analyze the accounting years: 2018, 2019, 2020, and I set up group 100 in the Liquidity grouping. I need to make sure that for all three years the group is the same.
Try the extension now
You have the opportunity to use a test accounting file with some random entries to get an idea of the extension's functionality. The file already includes the extension, so you don't even have to download it
You can test it by editing the transactions, the chart of accounts or the various settings in the dialog.
The accounting file does not exceed 70 transactions, so you can also try it out with the free or professional version and upgrade to the Advanced plan later.
Introduction
What is exactly the financial statement analysis?
Financial statement analysis is an accounting tool that provides an assessment of a company's economic, financial and asset condition. It is based on the financial statements and reports the data. It contains the profits and losses of a company and therefore serves to derive the general performance of the company.
Why is this activity very important for your SME ?
Until recently there were few SMEs that often used a financial statement analysis as larger companies could use it.
Today, times have changed. Reading the numbers well can make a difference within the strategy and management of an enterprise. Understanding which products it is worth investing in and which jobs can be neglected determines the difference between the growth or decline of a company.
This activity can be a source of interest for various subjects, external or internal to the company. Entities or external individuals can analyse their solvency profile (current or potential lenders), capacity to provide an adequate return on capital (for those who want to buy shares for example) or even just obtain information on the company's situation with respect to competition in the sector.
Through the comparative balance sheet analysis of the various elements available, it is possible to arrive at the following formulation of a "judgement" on the health of the company in all its dimensions:
- Economic
- Asset
- Financial
How it works
The financial statement analysis is based on two fundamental documents for a company:
- The Balance sheet
- The Profit and loss statement
In order to perform a correct analysis, it is always necessary to start from the reclassification of the accounts, which includes 3 phases in particular.
- Group the account items into groups
- Order such groups
- Bringing out intermediate results
The reclassification allows for a slightly cleaner first view of the company's situation and is already useful information can be obtained from it.
Analysis by Indexes
Once the intermediate results have been obtained, it is possible to proceed with the calculation of the indices useful for the analysis. The financial statements analysis by means of indexes is a very powerful tool that allows you to use indicators capable of providing a very concise assessment of one's own situation.
How should the data be interpreted?
Better results in terms of interpretation and evaluation are therefore achieved by analysing a series of balance sheets and studying the trend over time of the significant balance sheet ratios, so as to understand in which management is moving the company (dynamic financial statements analysis).
How do I evaluate them?
- Temporal evolution
- Comparison with average values of the sector
- Comparison with "normal" values i.e. with the benchmark
- Comparison with objectives
Response to results
This is the last activity of the analysis cycle, where the "relay" passes into the hands of those who deal with the Management of the Company, with data that speak clearly, the Manager will have to plan how to proceed using the right Project Management techniques.
The report contain errors?
If you notice incorrect data within the report or find that for some reason the calculated amounts do not match, please follow the steps below:
- Check that the data in your accounts are correct.
- Check that you have set up the groups correctly in the settings dialog.
If the errors persist, contact us via our feedback form and send us an example accounting file (*.ac2), even with little data, but allowing us to reproduce the possible problem and correct it.
Multi-language
The extension is available in the following languages:
- English
- Italian
- French (translation currently not complete)
- German (translation currently not complete)
And will adapt according to the language in which the application is set up. For all other languages, the standard version in English will be displayed.
Save your analysis
You can save the report in the following formats:
- Html
- Excel
- Latex
Settings Dialog
Dialog is accesible:
- By going to the Extensions menu→Cash Flow Statements and financial Ratios →Financial Reports.
- By going to the Extensions menu→Cash Flow Statements and financial Ratios →Settings.
Set up the groups
The first and most important step is to enter the groups or accounts number you are using in your account table.
Once you enter the groups the report and calculations are all done automatically, except for some specific transactions for the Cash Flow Statement.
- Groups must be entered manually
- Groups must be separated by a semi-colon ';'
- Both groups and accounts can be entered
- It is important to make sure that you include elements that exist in your chart of accounts, if are entered groups or accounts that do not exist in your chart of accounts, a message will be displayed on the row of the grouping concerned, returning those elements for which a match was not found in the chart of accounts. Once corrected, you only need to run the dialogue again and the message will disappear.
- By default, the groups within the dialogue refer to the Swiss SME chart of accounts, and it is possible to return to the base scenario by clicking the Restore Defaults button. Beware, however, that in this way the customisations made will be lost, and will be replaced with the default values.

All the necessary elements must be inserted within the different groupings defined in the dialogue (Liquidity, Fixed Asset,Owned base capital,...).
Assets
They show the total employment of a company, so the investments to which the company has allocated
the means found in carrying out its activity.
- Liquidity: Must include groups or accounts that define liquidity in the company, such as cash or bank
- Credits: Must include groups or accounts within which are recorded all the operations
concerning money due to buyers who didn’t paid yet for their purchases - Stocks: Must include groups or accounts with all goods for resale in the ordinary course of business.
- Fixed assets: Must include groups or accounts containing fixed assets elements, as:
- Buildings
- Computer equipment
- Computer software
- Furniture and fixtures
- Intangible assets
- Land
- Leasehold improvements
- Machinery
- Vehicles
Liabilities and Equity
Shows where company's resources come from. In general, the funds at the company's disposal are
classified in a way to distinguish between own funds (which flow into equity) and those from third parties.
- Short-term debt capital: Must include groups or accounts representing the company commitments that must be fulfilled, without any particular cancellation, in the current year.
- Long term debt capital: Must include groups or accounts containing that kind of capital that the company can have at its disposal for several years, on a fixed basis, and that can usually only be withdrawn within a set time limit.
- Own Base capital: Must include groups or accounts those group referring to the company's own capital.
- Reserves and Profits: Must include groups or accounts within which are recorded the amounts to be paid to reserves or designated as profits.
Revenues
Indicates what is produced by the company during a financial year. Whether it is an increase in the value of products or semi-finished products in the course of production or services in progress, revenue from the sale of products or services or the increase in the value of fixed assets thanks to own resources, all these heterogeneous factors add up.
- Sales turnover: Must include groups or accounts within which is recorded what is produced by the company during a financial year. Whether it is an increase in the value of products or semi-finished products in the course of production or services in progress.
Costs
- Costs of Merchandise and services: Must include those groups or accounts in which all costs relating to goods and services consumed during the annual financial year are recorded.
- Personnel Costs: Must include all those accounts referring to a cost due to personnel, such as:
- Salaries
- Social charges
- Severance Pay
- Pension and similar treatment
- Other costs
- Different Costs: Must include all other groups or accounts relating to costs during the operating period.
- Interests: Must include groups or accounts containing the costs of financing sources, such as bank interest payable or interest on loans.
- Depreciation and Adjustments: Must include groups or accounts where are registered possible revaluations and write-downs of equity investments, as well as of financial fixed assets and securities included in current assets that are not equity investments.
- Final Result: The group containing the difference between the costs and the revenues at the end of the year.
Average Number of employees
This information is useful for calculating efficiency ratios, enter the average number of employees in the company and find out information such as the average company revenue per employee.
Printing Preferences
To make the Analysis as close as possible to your needs you can set some preferences, and choose about the details of printing and analysis

Printing Details
- Page header: Include the header in the report, the header is composed with the information retrieved from the properties of the file.
- Logo: Choose whether to include your company logo in the report. for information on how to set up a logo visit this Logo set up page.
- Background color of headers: Choose the colors for the table headings
- Text color of headers: Choose the color for the texts in the table headings
- Report Without colors: Check the box for no colours in the report.
Analysis Details
- Number of previous years: Set the number of previous accounts (years) to be included in the analysis, which will be added to the current year and the Budget (if present and included).If you don't know how to set the previous year to a file, go to “File→File and Accounting Properties→Options Tab.
- Number of decimals: Choose how many numbers after the decimal point you want for the digits in the report, if you don't want to have decimals you only need to insert a zero 0.
- Include Budget: If you are using the Budget table for your financial planning, you have the possibility to include it in the analysis.
- Include Budget to date column: Include the columns showing the values of the budget up to that day, compare the values with those of the year-to-date.
- Include Current year projection column: You can include the projection for the current year. The programme uses the values in the budget table to return what could be the values at the end of the year.
- Current Date: Insert the current date. If no date is entered, the date of the day is taken automatically
- Include DuPont Analysis: Choose whether to include the Dupont Analysis
- Include Control Sums: Choose whether to include the table with the control sums, useful to inform in case of errors on the totals (assets/liabilities, operating result).
- Show the formulas column: Choose whether to show the column with the calculation formulas.
- Show the acronym column: Decide whether or not to show the acronym column, which is useful for identifying the elements used for formulas.
The columns of acronyms and formulas are complementary, that's beacuse the acronym column is useful to uderstand how the formulas are composed. if you dont need these columns, just uncheck the checkbox.
Set the benchmarks
Benchmarking is a method of assessing an organisation's competences based on comparison with the "best
in class", whatever sector it belongs to. So the Benchmark is a key performance indicator on the basis of
which a company assesses its performance with regarding to products, services and business processes.
You can customise these values depending on your company:
- Sector
- Size
- Targets
These values are only representative, which means that the figures you enter are not used in the analysis but are shown as they are. In the report, they are displayed in the Benchmark column, in the indexes tables, so that you can quickly assess the situation.

It's also possible to call the dialog from the opened report and change the parameters. The values of the
analysis will be updated automatically.
Cash Flow Statement
Cash Flow is an analytical tool that helps to visualise the positive and negative changes in liquidity as a result of management, with reference to a given period of time: it is in fact the reconstruction of monetary flows, then the difference between all the monetary income and expenditure of a company.
Cash Flow analysis is not subject to accounting rules and many investors use the data to assess the strength of the company.
Essentially, if the Cash Flow is positive, it shows the financial availability for the company within the reporting period, whereas if the cash flow is negative, it means that more resources have been absorbed than have been received.
Special Cash Flow transactions
The first step to obtain the Cash flow Statement i its to setup the account groups in the settings dialog, Most value needed for preparing the Cash Flow Statement can be calculated based on the changes of the standard account classification. Identifying Disinvestments, Revaluations, transactions and other specific movements effecting the cash flow, would require a restructuring of the account plan. We have therefore opted to identify these values, by adding a special code to the description of a transaction.
It is important that these transactions are made using the recommended account type or group, because the program searches for cashflow amounts in certain groups, so if an entry is made using another account type, there could be an error as the amount may not be found.
If we talk about entering a fixed asset account, the account must belong to one of the groups entered in the fixed assets section of the dialogue. For example, if I disinvest by selling a vehicle and I use the standard chart of accounts for SMEs, I can use the account Vehicles '1530', which is part of the group 150, which in the dialogue is entered under the section 'Tangible Assets' in the fixed assets.
- Disinvestments (#disinvest)
- A disinvestment simply represents the sale of a fixed asset such as a vehicle or machinery. When recording a disinvestment.
- Debit Column: Insert the account where you will collect the money from the sale, such as the post or the bank.
- Credit Column: Insert a fixed asset account that relates to the item sold.
- Knowing the amount of disinvestments, the program is able to calculate in detail the real amount of investments that have been made during the year. For an SME, the number of disinvestments during the accounting period usually remains quite small, whereas investment activities are much more frequent operations, which is why it is very important to find the real amount net of all other movements.
- A disinvestment simply represents the sale of a fixed asset such as a vehicle or machinery. When recording a disinvestment.
- Revaluations of fixed assets (#revaluations)
- Revaluation of a fixed asset is the accounting process of increasing the carrying value of a company's fixed asset or group of fixed assets to account for any major changes in their fair market value.
- Debit Column: Enter the account of the fixed asset item you are revaluing to increase its value.
- Credit Colum: Enter an income account, if you don't have a particular one you can enter it as extraordinary income.
- Revaluation of a fixed asset is the accounting process of increasing the carrying value of a company's fixed asset or group of fixed assets to account for any major changes in their fair market value.
- Devaluations of fixed assets (#devaluations)
- It works in the same way as a revaluation, but instead of increasing the value of the fixed asset it decreases it, which means that the accounting entry is also reversed, i.e. the income becomes a cost.
- Debit Column: Enter a cost account, if you don't have a particular one you can enter it as extraordinary cost.
- Credit Colum: Enter the account of the fixed asset item you are revaluing to increase its value.
- It works in the same way as a revaluation, but instead of increasing the value of the fixed asset it decreases it, which means that the accounting entry is also reversed, i.e. the income becomes a cost.
- Dividends (#dividends)
- Dividends are fees paid to shareholders and usually depend on the profit made. The payment of a dividend must be recorded in a specific liability account, and should appear under short-term liabilities.
- Debit Column: Enter the reported balance sheet Profit / Loss carried forward account.
- Credit Colum: Enter the specific account for dividends.
- Dividends are fees paid to shareholders and usually depend on the profit made. The payment of a dividend must be recorded in a specific liability account, and should appear under short-term liabilities.
Cashflow Statement
Cash flow is divided into three main components:
- Operating cash flow which originates from the core business operations of a company.
- Cash flow for the company, which is the cash flow available to all investors in the company.
- Cash flow available to shareholders, which only considers the cash flows that are due to the shareholders, resulting from the net of all payments made and received, including from debt holders.
Adding up all the totals you find the amount that corresponds to the change in liquidity for the period, which in turn when added to the value of the liquidity at the opening of the period should give you the current liquidity balance.
If the results do not match, an error message is displayed.
Acronym column
In the acronym column of the cashflow, the reference to the account taken into account in the calculation is entered, or in the case of special entries, the prefix of the entry, so that it is easy to see which item of the balance sheet or income statement a certain movement relates to.
Cash Flow verification
This table shows any differences between the change in cash flow calculated in the cashflow and the actual cash flow in the accounts, which in an optimal situation should match. If there is a difference in one of the years of analysis the amount in question is printed in red on a line below.
Usually, when an error occurs, the first thing to do is to check whether the amounts in the balance sheet and profit and loss statement are correct or whether there are differences between the assets and liabilities, for checking them, control sums are very useful because they immediately show whether there is a difference.
if you realise there is some error but you dont know exactly where, you can check the amounts by comparing the ones in the report with those in the chart of accounts.
The differences are generally due to an error when entering groups in the settings dialog, which can occur in two ways:
- One or more groups were not included
- One or more groups were entered under the wrong heading
In case the balance and profit and loss amounts are correct but the cashflow displays an error, is probably due to the fact that a group has been inserted in the wrong place.
Retained Earnings Statement
This table shows the movements made with the annual profit achieved. Starting from the reported annual profit it adds the profit for the period and adjusts the value by taking into account the payment of dividends and the creation or dissolution of reserves. The last two rows show the total undistributed profit, and the undistributed profit realised in the current year.

This information is somewhat supportive of Cash Flow but since earnings management does not directly affect cash, it is presented in a separate statement.
Record Transactions
It is useful to first record the transfer of the profit for the year from the profit and loss account to the profit shown in the balance sheet as shown in the example image.
In order to record the payment/discharge of reserves and the payment of dividends, it is sufficient to use the specific account of one of the above items and to decrease or increase the profit account shown in the balance sheet. The remaining amount (not allocated to reserves or dividends) then increases the retained earnings.

Cash Flow Ratios
In addition to the ratios already present, those ratios are added just below the Cashflow table and in the Charts
- Cashflow margin: Measures the amount of revenue a firm can convert into operating cash flow. When a firm is thriving, operating cash flow should grow alongside revenue. While profit margins measure a firm's pricing power; a declining cash flow margin also measures the health of customer and supplier relationships.
- Asset Efficiency Ratio: This is a basic ratio to show you how well the company uses its assets to generate cash flow. It’s best used to view the historical trend as well as to compare with competitors.
- Cashflow to current Liabilties: This ratio gives you an idea about the company’s debt management practices.It’s also a better indicator of the company’s ability to pay current liabilities than the current ratio or quick ratio
- Cashflow to Liabilities: Measures the amount of operating cash flow a firm generates on each dollar of total liabilities. Businesses that can't produce operating cash flow to pay off all their liabilities cannot continue to operate indefinitely, making this ratio an important indicator of liquidity as well as solvency
- Cashflow to Investments: Measures the amount a company outlays for capital assets for each dollar of cash dollar it generates from those investments.
Why Is Cash Flow Analysis Important?
Performing cash flow calculations in combination with constant monitoring of the company's cash flows is the winning formula for effective treasury management, and is useful for making the best use of available cash.
Thanks to the ability to generate cash flow and the financial solvency of the company, you gain confidence from banks and suppliers, as it symbolises a certain control over your business: the calculation of cash flow is in fact a way to detect the actual availability of the company, giving the possibility to face unexpected events or to plan consistently the future of projects.
For more information on Cashflow Analysis, please refer to the following page.
Balance Sheet and Profit and Loss Reclassification
Generate the Report by going to the Extensions menu→Cash Flow Statements and financial Ratios →Financial Reports.
The Report contains all the analysis data processed by the extension:
- Reclassified balance sheet
- Reclassified Profit and Loss Statement
- Control Sums table
Reclassified Balance Sheet
The reclassification of accounts allows for the display of a series of values, results and intermediate margins that contain more information than the traditional structure.
- Current Assets: All the assets of a company that are expected to be sold or used as a result of standard business operations over the next year.
- Fixed Assets: Items, such as property or equipment, a company plans to use over the long-term to help generate income.
- Total Assets: The sum of current assets and fixed assets.
- Debt Capital: Is the capital that a business raises by taking out a loan. It is a loan made to a company, typically as growth capital, and is normally repaid at some future date.
- Own Capital: It is the capital owned by the company.
- Total Liabilites and equity: The sum of Debt Capital and Own Capital.
Reclassified Profit and Loss Statement
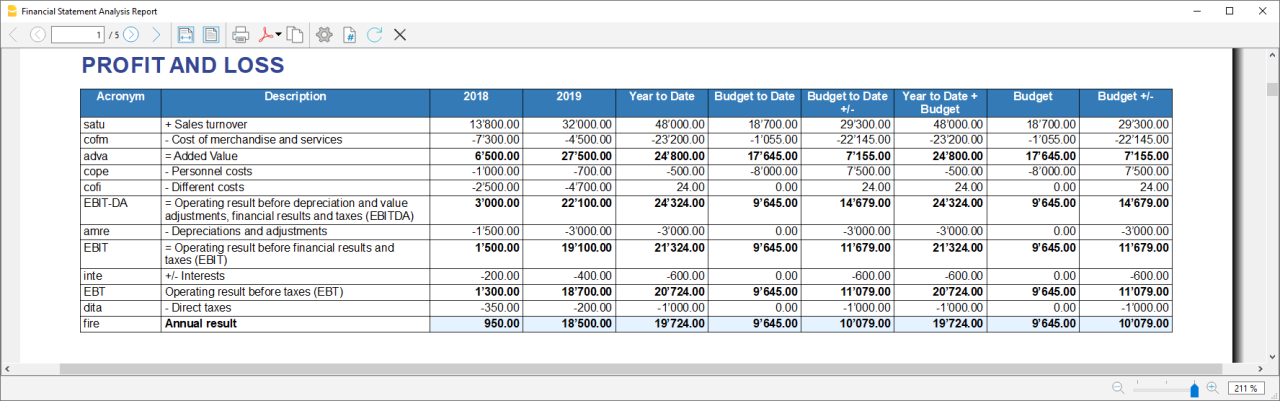
- Added value: The difference between operating costs and operating revenues incurred for resources outside the company, expresses the company's ability to create wealth and then remunerate the various production factors and stakeholders.
- MOL /EBITDA: "Earning Before Interests, Taxes, Depreciation and amortization" is obtained by subtracting from production revenues the costs of production (including internal costs such as personnel costs), without considering provisions and depreciation. As it does not contain economic items without monetary movement, its value assumes very important information for financial investors.
- EBIT :"Earning Before interests and Taxes", helps to understand whether the company is also able to cover the financial charges arising from its financial commitments.
Control Sums
Resumes the totals of the reclassified accounts (Assets, Liabilities and Equity , Annual Result). Checks that the sums calculated in the analysis match the totals in the accounting sheets and that Assets and Labilities and equity match.
- Accounting Total column: Represents the actual total in the accounts.
- Calculated Total column: Represents the total calculated by the program based on the groups entered.
- Difference column: Represents the difference found between the total in the accounts and the calculated total for each year. The value equal to 0, otherwise will be displayed an error message, which means that there may have been an error in entering the accounts/groups .In this case it is useful to check in the dialogue that you have entered the groups correctly.
Financial Ratios
Generate the Report by going to the Extensions menu→Cash Flow Statements and financial Ratios →Financial Reports.
The balance sheet ratios are formulas calculated on financial, economic and asset values. These ratios are derived from the income statement and balance sheet data. Balance sheet indices are important analysis tools that provide essential indications for the entrepreneur's activity.
It is widely used by all professionals who are interested in assessing the soundness of a company for their work.
In fact, banks use the balance sheet indexes to evaluate company loan applications.
the indexes are divided into four main types
- Liquidity ratios:
- Financing ratios
- Profitability ratios
- Efficiency ratios
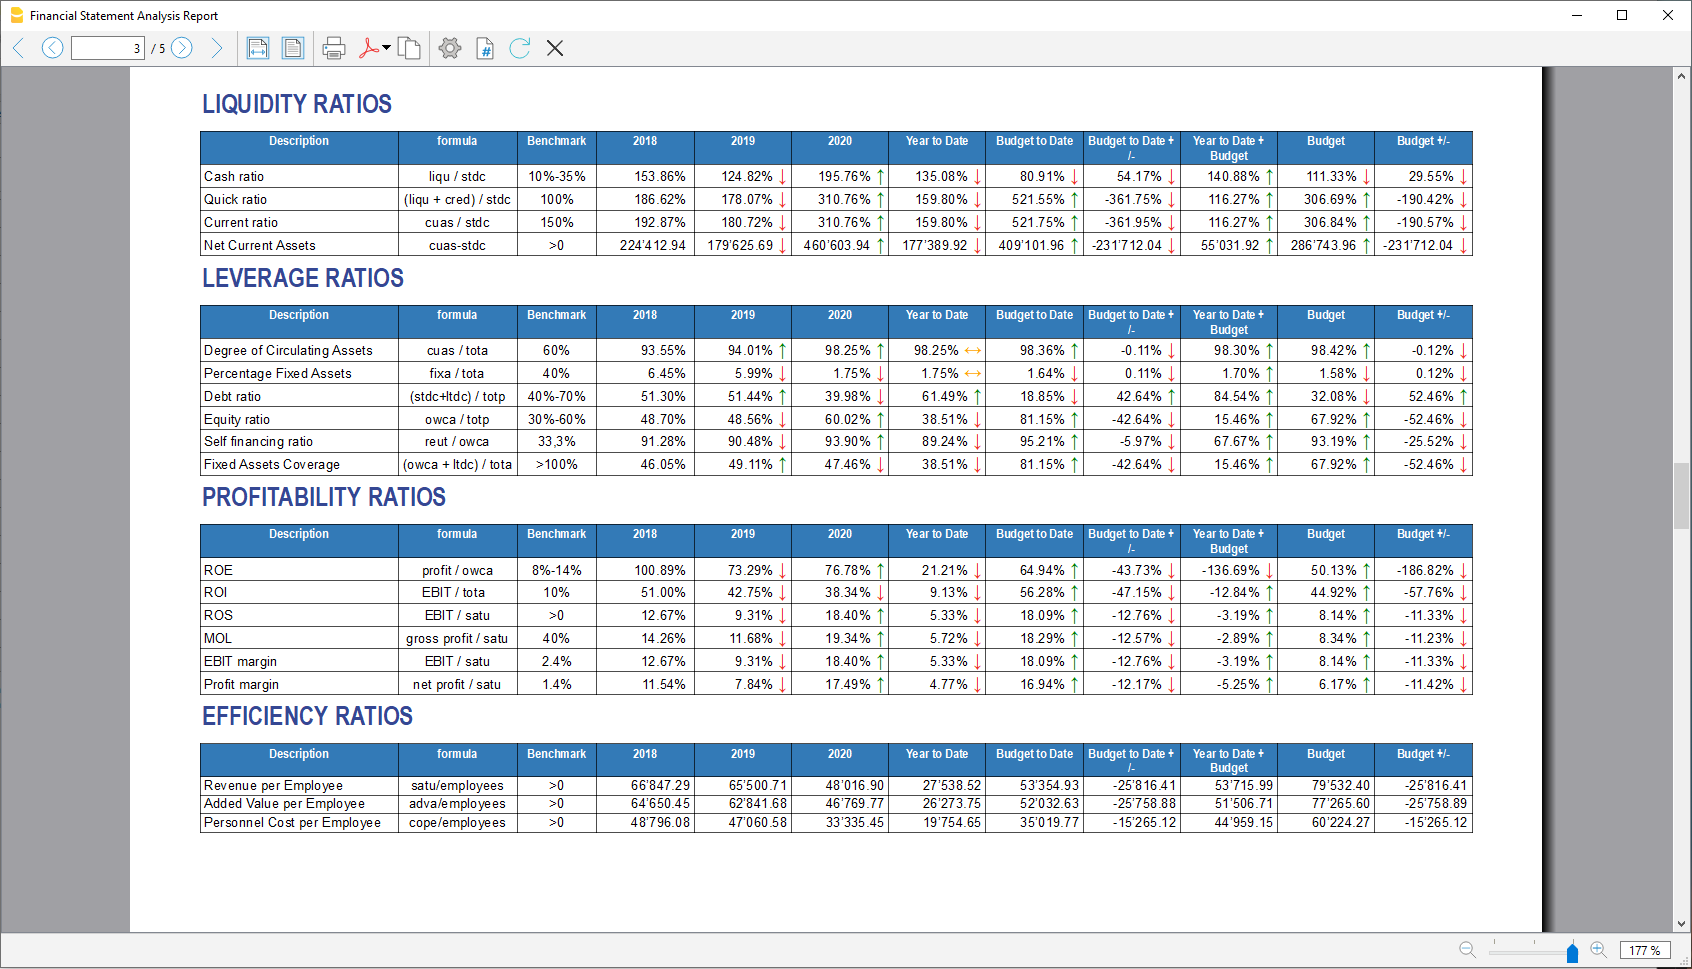
Liquidity ratios
An important class of financial metrics used to determine a debtor's ability to pay off current debt obligations without raising external capital. Liquidity ratios measure a company's ability to pay debt obligations and its margin of safety through the calculation of metrics.
- Cash ratio: Indicates the extent to which the company is able to repay its debts at the end of the term.
- Quick ratio: Indicates the extent to which the company is able to pay its debts when due.
- Current ratio: Indicates the extent to which the company is able to pay its short-term debts without touching fixed assets.
- Net Current Asset: Indicates the part of the current assets free of short-term commitments, which can therefore be used in the activity.
Financing ratios
They look at how much capital comes in the form of debt (loans) or assesses the ability of a company to meet its financial obligations.
- Degree of Circulating Assets: It allows us to understand whether there is a balance within the company's assets, a judgement can only be made if we have the average data for the same line of business.
- Percentage Fixed Assets: It is complementary to the previous one.
- Debt ratio: Indicates the extent to which the company has had to resort to external financing, the judgement depends very much on the branch of activity.
- Equity ratio: Is complementary to the previous one, equity ratio has the advantage of being less expensive.
- Self-Financing ratio: Indicates the extent to which the company has been able to accumulate undistributed profits.
- Fixed Asset coverage: The fixed assets must absolutely be financed from equity or possibly from long term capital, otherwise major repayment problems could occur.
Profitability ratios
Are useful to assess a business's ability to generate earnings relative to its revenue, operating costs, balance sheet assets, or shareholders' equity over time, using data from a specific point in time.
- Return on equity (ROE): By comparing the percentage obtained with the rates commonly applied for other investments, it is possible to understand whether the equity invested by the company gives a sufficient return or not.
- Return on investment (ROI): Identifies the return on invested capital. Basically it serves to understand how much the invested capital returns in terms of income.
- Gross Operating Margin (MOL) :Is a value that measures the profitability of a company. In other words, it measures the ability to make profit margins: Indicates the company's return on sales made.
- EBIT margin: Is the ratio of EBIT to turnover of a company. This ratio provides information on its profitability and helps to compare different companies and sectors.
- Profit margin: It represents what percentage of sales has turned into profits.
Efficiency ratios
Express the degree of efficiency of the company's factors of production, those chosen by us give us an indication of the relationship between the number of employees and the various margins of the profit and loss account. Efficiency indicators are related to profitability indicators, as higher productivity generates an improvement in profitability indicators.
- Revenue per Employee: An increase indicates greater efficiency of the company and a lowering of the break even point. Its increase is certainly an indicator of the good health of the company itself.
- Added Value per Employee: Gives evidence of efficiency in terms of cost reduction (e.g. economies of scale). If the revenue per capita index remains stable and the value added per capita index increases, this is evidence of cost efficiency.
- Personnel Cost per Employee: Highlights the trend in average personnel costs.
Within the tables and also visible the calculation formula of each index.
Dupont Analysis and Altman index Z-Score
Dupont Analysis
The Dupont model is a technique that can be used to analyse the profitability of a company using
traditional performance management tools. To enable this, the model integrates the elements of the Profit
and Loss Account and Balance Sheet.
Altman index Z-Score
The Z-Score is an index of the discriminating analysis used to determine the probability of bankruptcy of a
company within 2 years using statistical techniques.
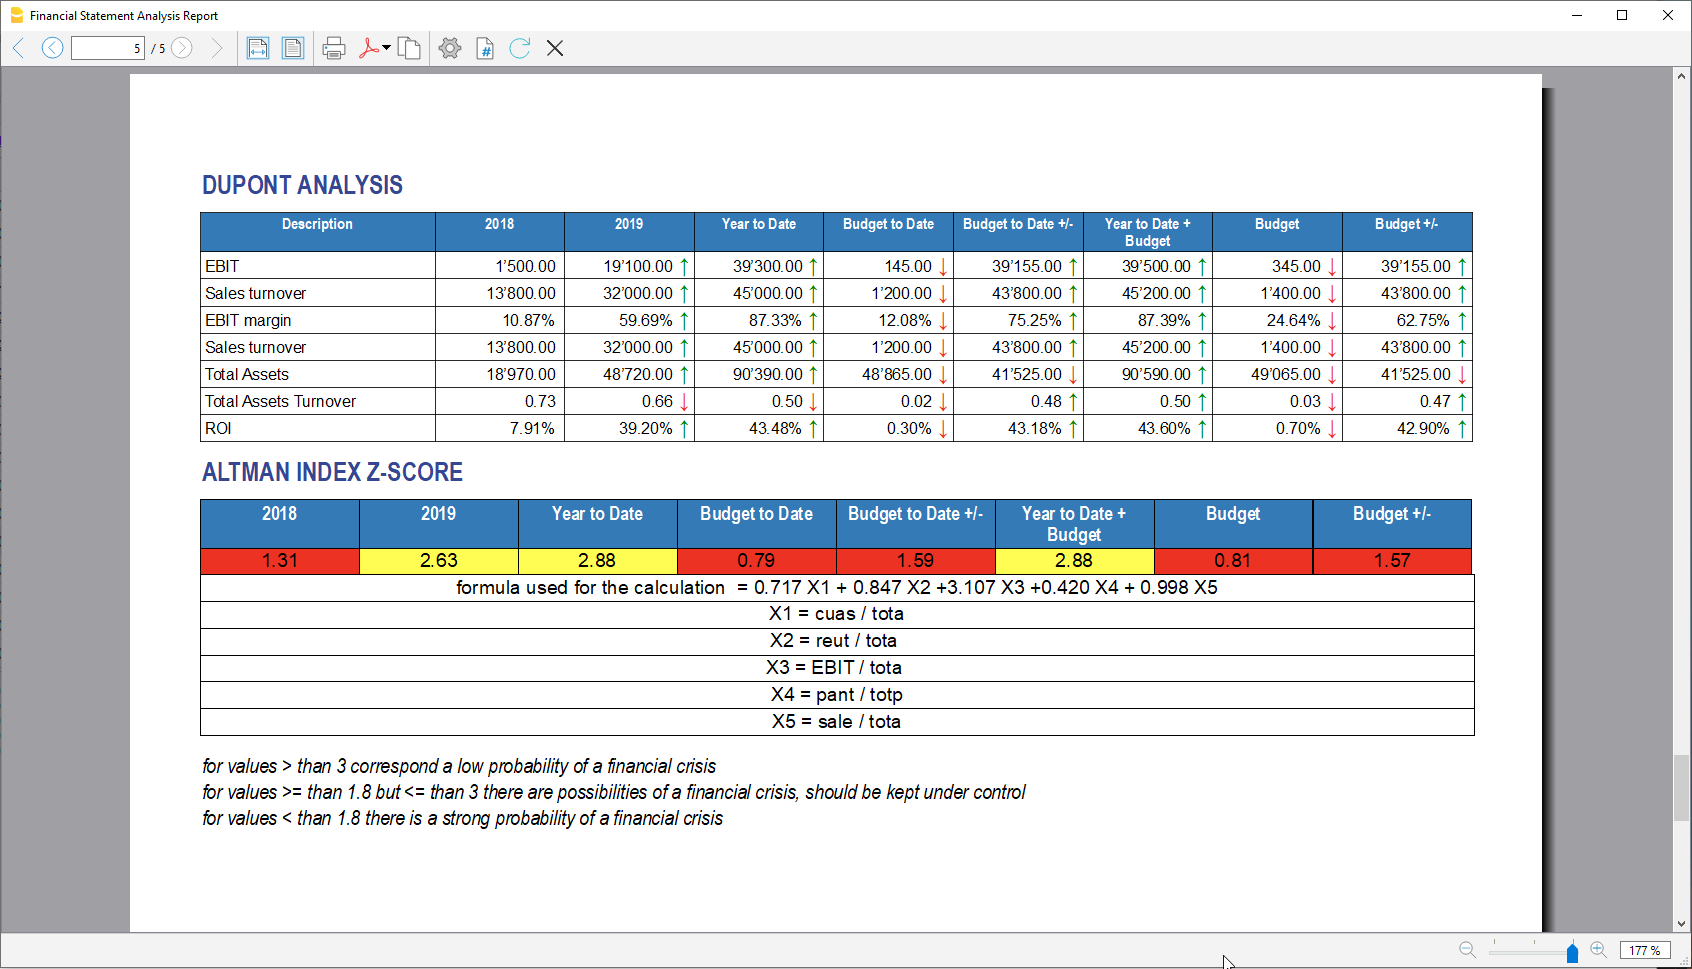
Financial Charts
It’s possible to access to the charts by going to the Extensions menu→Cash Flow Statements and financial Ratios →Financial Charts.
Charts allow you to read the same information as you can find in the report but in a clearer and more
intuitive way. Once the dialogue is open, you can move between the various elements thanks to a drop-down menu.
Ratios charts
- Financing ratios evolution
- Liquidity ratios evolution
- Profitability ratios evolution
- Efficiency ratios evolution
- Cashflow ratios evolution
These charts represent the evolution of the indexes over time. For each type of index there is a bar chart,
within which there is a section that represents the evolution over time of each index for each year included
in the analysis.
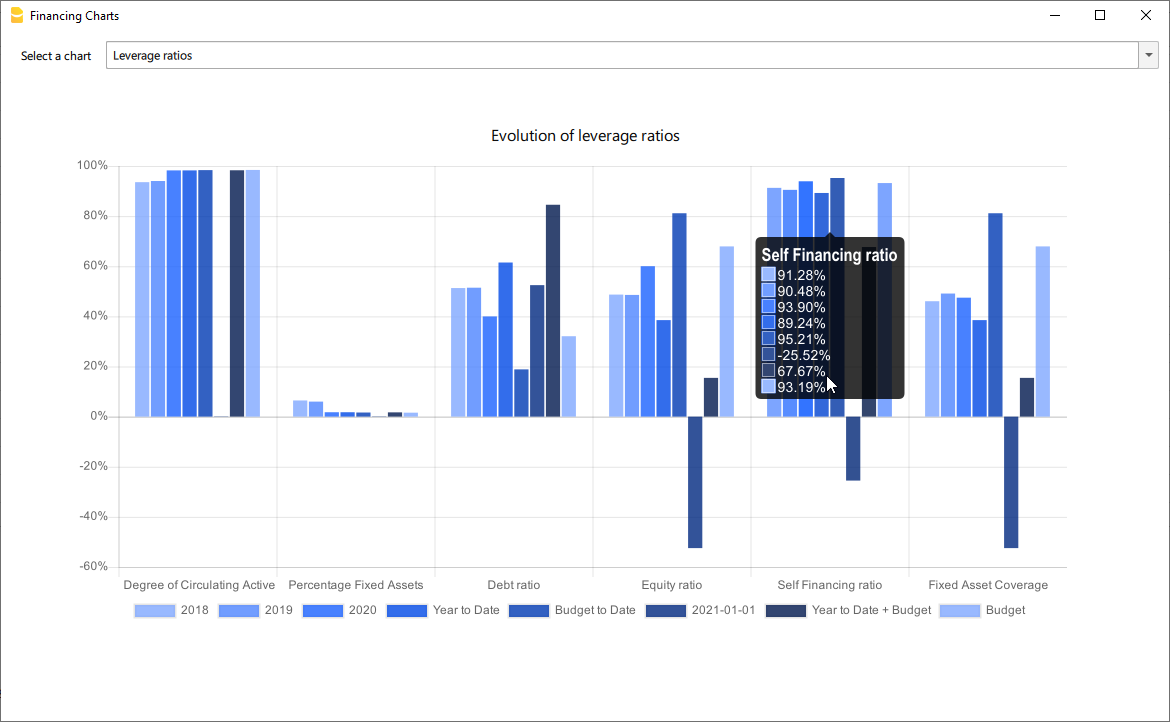
Reclassified Elements charts
- Reclassified asset variation
- Reclassified liabilities and equity variation
These charts show the time evolution of the reclassified assets, and reclassified liabilities, using stacked
chart. It is possible to see how and in what quantity the groups make up the total of assets and liabilities (in
percentage %)
Reclassified profit and loss variation
Shows by using histogram the value of the intermediate totals (EBIT,EBIT-DA,..) of the reclassified profit and loss account ,and their evolution over the time.
Airbnb, Booking.com, Vrbo and similiar hosting platform templates
Those who have an Airbnb rental business and are looking for a simple and efficient way to manage their finances will find the ideal solution in Banana Accounting Plus templates for several reasons.
With the templates, you can manage and track all expenses and income for all the rooms, apartments or houses you rent without any limits.
Moreover, you can manage the budget for your business in a flexible and personalized way. Whether you have multiple rooms, apartments or houses, you can keep track of specific income and expenses either collectively or divided for each individual rental unit. Additionally, you can set the budget according to irregular or regular deadlines such as monthly, quarterly, semi-annually or annually. This way, you can adapt the budget to your financial and business planning needs.
Through the budget feature in the templates, you can also make financial forecasts for your short-term rental business. You can gain a clear and detailed overview of your future income and plan ahead for all your activities.
Inventory management is another useful and powerful functionality offered by Banana Accounting Plus. You can keep track of all the items relevant to your business, categorizing them by room, apartment or rented house. This way, you will always be aware of what you own and easily manage the purchase or replacement of any necessary assets. With Banana Accounting Plus, you can create all the accounting files you need without limitations.
Regarding the management of income from hosting platforms such as Airbnb, Booking.com, Vrbo and others, the templates provide you with the option to record both the actual income deposited into your bank account and all other rental-related income, especially the commissions paid to the platforms. This information is crucial for tax purposes as it allows you to comply with the rules of the country where you operate your business.
For those who have an Airbnb business and are looking for a simple and efficient way to manage their finances, Banana Accounting Plus templates provide the ideal solution for other several reasons too.
Available templates
There are two templates available for short-term rental hosts on Airbnb, Booking.com, Vrbo or similar platforms.
The completely free template is suitable for those without accounting knowledge who want to manage the finances of their business. The second template is designed for those with double-entry accounting knowledge and who manage a business using multiple assets and possibly different currencies:
- Free template based on Banana Accounting Plus Cash Manager.
- Double-entry and multi-currency template.
All the functionalities and features described in the free template are also included in the double-entry multi-currency template.
In each template, you can easily view some sample accounting entries.
Manage Airbnb reservations
With Banana Accounting Plus templates, you have complete control over your reservations even before they are paid. This allows you to keep track of all bookings in your file, ensuring you are always up to date on availability and key dates. You can input reservations into the system and monitor them, making planning and management of your rental properties easier.
In addition to managing reservations, the templates also allow you to record payment receipts and income. This is particularly useful for monitoring and ensuring compliance with maximum nights allowed regulations in your country. You will have an accurate record of guest stays and corresponding income, providing clear and transparent documentation for regulatory compliance purposes.
Manage Airbnb Experiences
Banana Accounting Plus templates also enables you to manage and track Airbnb experience reservations. If you offer unique experiences such as sailing trips, mountain bike tours, tastings or others, you can record these specific bookings and efficiently monitor them. You will have a comprehensive overview of your Airbnb experience activities, including booking details and corresponding income.
With Banana Accounting Plus templates you simplify the financial management of your Airbnb rental business. You can take advantage of all the features offered and gain a clear and organized view of your finances.
Manage Airbnb business budget and financial forecasts
The Budget table in all Banana Accounting Plus files provides a comprehensive tool for creating your business budget and forecasting future financials.
This feature, always accessible through the Tools > Add/Remove functionalities menu, allows you to generate cash flow statements, liquidity plans and investment plans.
For more advanced needs, you can create budgets using formulas and automatic calculations. Additionally, you can obtain monthly, quarterly and annual financial forecasts as well as projections for multiple years.
Explore the full documentation on budget management and financial forecasting with Banana Accounting Plus.
Manage inventory along with their corresponding receipts
On all files, Banana Accounting Plus allows the display of the Link column in the Transactions table, enabling you to attach supporting documents to each accounting entry.
If needed, there are other predefined columns that you can easily show in your accounting file.
Additionally, with Banana, you can add your custom columns, additional tables, and link them to existing ones. Refer to the documentation on enabling the display of predefined columns and adding columns and new tables to your file.
The ability to add new tables and create custom columns also allows you to integrate the inventory of items in the rooms and apartments you rent into your file and attach relevant documentation, which can be useful, for example, for warranty or insurance purposes.
If you prefer you can create a dedicated new file to create and manage the inventory of your rooms and rented apartments. With all Banana Accounting Plus subscription plans, there are no limits on the number of files you can create and manage.
Handle the accounting recording of the fees you pay to platforms
Using a spreadsheet like Excel or Google Sheets doesn't always allow for proper management of income received from platforms such as Airbnb, Booking.com, Vrbo or similar ones. Often, the income received in your bank account does not include the commissions you need to pay to the platforms.
These platforms deduct the commissions before making payments, but there are countries where you are required to declare the gross income for tax purposes, including the deducted commissions.
With Banana Accounting Plus you can record the gross income you receive, ensuring that everything is accurately accounted for and that your bank balance always matches the actual balance in your account.
Check the example entries in the provided templates pages to see how this accounting record is done.
Free Airbnb template for income and expenses management: ideal also for Booking.com and Vrbo
在此文中
Free Airbnb template for income and expenses management: ideal also for Booking.com and Vrbo
Free Airbnb template for income and expenses management: ideal also for Booking.com and Vrbo
Take a look at the template for managing income and expenses for hosts on Airbnb, Booking.com, Vrbo or similar hosting platform on Banana Accounting Plus Web. Click on the Open in browser button below, then click on Start Banana Accounting Web and wait for the template to load to get an immediate idea of how it works.
直接在网页中打开Banana财务会计+
无需任何安装,可以直接在您的浏览器上运行 Banana财务会计+。客制化您的模板,输入发生业务并将文件保存在您的电脑上。
在浏览器中打开模板 Open tutorial in WebApp模板文件
Manage your accommodation on Airbnb, Booking.com, Vrbo or the platforms you use with this free template and keep track of your finances easily and efficiently.
The Banana Accounting Plus template is superior to an Excel spreadsheet or a Google Sheet but avoids potential errors and time loss due to formula management. This way, you have a completely free accounting management template specifically designed for hosts.
With Banana Accounting Plus, unlike Excel or Google spreadsheets, there are no limits on the number of rooms, apartments or houses you can manage, and it allows you to easily track income and expenses for each individual rental property and your entire short-term rental business.
With this template, you can record and monitor all your income and expenses quickly and easily, providing you with a clear and detailed snapshot of your finances and how to optimize expenses. The accounting management template on Banana Accounting Plus offers a simple and effective way to organize and analyze all the financial data that is important for hosts.
Here are some of the key features and benefits of the free accounting management template:
- Easy to use: the template is designed to be intuitive and user-friendly, even for those who are not accounting experts. No technical skills or in-depth knowledge of Excel spreadsheets are required to use it. Banana Accounting also has extensive online documentation in multiple languages readily available.
- Startup budget: create, manage and update the budget of your startup to generate detailed and useful reports and forecasts for the success of the business.
- Income tracking: record all income generated from bookings, including payments from platforms, booking fees and reimbursement of cleaning expenses for rooms, apartments or houses, with all the necessary tracking details.
- Expense management: keep track of all expenses associated with your properties, such as utilities, cleaning, maintenance and supplies. Choose the level of detail you prefer for each expense associated with your rental properties. Add, edit, group and customize expenses you want to monitor without limitations.
- Track rental property information: easily track guest names, rented room, apartment or house, check-in and check-out dates, total nights stayed, number of guests per booking, the source of guests' bookings and payment dates from platforms.
- Automatic calculations: the template performs calculations automatically for you, without the potential errors of Excel or Google Sheet formulas, providing a clear overview of your cash flow, profits and expenses for your entire business or for a single room, apartment or house you manage.
- Detailed reports: generate comprehensive and professional financial reports, including profit and expense statements, balance sheets and more. These reports will help you make informed decisions and have detailed control over your finances.
- Manage hosting platform Experiences: easily and quickly manage the Experiences you offer on Airbnb, Vrbo or other similar platform.
- Customizable: the template can be easily customized to fit your specific needs. You can add custom categories, modify, group and personalize all the details you want to monitor according to your preferences.
- Privacy: it's important to note that the data entered into Banana Accounting is not used for commercial purposes. Your information remains confidential, offline and is not repurposed in any way.
This free template for income and expense accounting management for hosts managing their short-term rental properties simplifies the management of your finances, saves you valuable time, and provides you with a clear and comprehensive overview of your income and expenses professionally.
Banana Accounting is a highly versatile and customizable accounting software that can be used for broader accounting purposes beyond managing hosts on Airbnb, Booking.com, Vrbo and other hosting platforms.
Totally free
This template is based on the Cash Manager feature of Banana Accounting Plus, which can be used for free and without limitations with the free subscription plan.
Create and save the file
You can open and save your new file to start either through Banana Accounting Plus Web or by downloading and installing the software on your computer:
- Download and install Banana Accounting Plus.
- Click on File > New.
- Select Cash Manager.
- Search for the Category Business.
- Select the template "Income and expenses management template for Airbnb or similar platforms".
- Click on Create.
If you click on the text "More info...", you will be directed to this specific documentation page for the template. On this page, you can always find the tutorial file including sample records.
Using the command File > File Properties, set your references, the accounting period with opening, closing dates and the base currency. In the Address section, fill in the fields for the entity managing the rental properties. If necessary, change the base currency of the accounting file in the Accounting section.
With the command File > Save As, save the file. It is useful to include the name of your business and the year in the file name. For example, "BusinessName-2023.ac2".
Also, refer to the article on organizing accounting files locally, on a network, and in the cloud.
Banana Accounting Plus Web Access
When you have downloaded and saved your new accounting file to open and use it from the web, you can bookmark the following link to access Banana Accounting Plus Web. However, it is recommended to download and install Banana Accounting Plus on the computers where it is needed, because Banana Accounting Plus Web does not yet have all the features available.
Create the budget
With Banana Accounting Plus, you can easily create a startup budget for your new short-term rental business on Airbnb, Booking.com, Vrbo and other platforms, and forecast all the costs you'll need to deal with. Consult all the relevant documentation on how to create a budget with Banana Accounting for detailed information.
Customize and categorize expenses
If you prefer, you can group similar costs into categories and maintain the detail for each type of expense:
- Properties costs: mortgage payments, repairs and insurance coverage.
- Initial setup expenses: spending on furniture and household utensils.
- Bills: electricity, gas and water expenses.
- Supplies: expenses for items like linens, toiletries and cleaning products.
- Business expenses: costs related to accounting, software and taxes.
- Other costs: payments for cleaners, laundry services and ads.
See how you can easily create accounts groups.
Recording transactions
In the Transactions table, record all transactions in chronological order, including debtor payments and invoice payments, as well as other types of transactions. The recordings can always be sorted and viewed instantly. You can highlight rows, correct any mistakes and copy and paste previously entered transactions.
To expedite data entry, we suggest using the various features of Banana:
- The auto-completion data entry feature automatically retrieves previously entered data.
- The recurring transactions feature (in the Actions menu) allows you to store frequently recurring transactions in a dedicated table.
- You can import data from bank statements, automatically capturing all bank transactions.
- You can link each recording to its corresponding digital document, and with a simple click, you can view the document. Refer to accounting files and digital documents for better document organization.
- Use the sort recordings command to arrange rows in chronological order.
- Use the print/preview command to print or export the journal in PDF format.
Bank transactions import
You can import bank statements, eliminating the need for manual entry.
Additionally, with the Advanced plan, it also allows for easy management of rules to automate accounting according to your specified criteria. This significantly reduces the effort required for accounting management, resulting in unmatched time savings.
Print financial statements or accounting reports
To view and print the financial statements at any time, click on the Report menu > Enhanced financial statements with groups. You can customize them or have an accounting report for a specific period.
Obtain detailed and customizable reports on all expenses and revenues of your business with Airbnb. You can compare them with the budget to always keep track of the performance of your startup.
If you manage multiple rooms, apartments or rental properties, you can keep track of expenses and revenues allocated to each individual property you rent. You can also create room-specific budgets and compare the results with the actual expenses and earnings whenever you want.
Advanced management
If you want, you can manage your Airbnb business in an advanced and optimized way through the rental management view called Manage Rentals. This allows you to keep track of all the necessary information about the reservations you receive. For those who offer Airbnb Experiences, there is the experiences management view, called Manage Experiences, available to track guest bookings related to experiences.
Navigate between the various available views to keep all the relevant data under control.
Questions or specific requests
Do you have any questions or specific requests regarding this template for Airbnb hosts or other short-term rental platforms? Please e-mail us.
Sample records for managing income and expenses for Airbnb hosts or other hosting platforms
Here are the sample accounting records for this template.
Recording an Airbnb or other platform revenue transaction
Record revenue from online platforms such as Airbnb, where you receive booking fees, with the preferred breakdown of the collected amounts and platform commissions. If you want, keep track of the ad from which the guest made the reservation, the check-in and check-out dates, the number of guests for the booking, the booked nights, the room or flat rented and the date of payment from the online platform.
To print the receipt to be given to the guest upon arrival, enter the receipt number in the Doc column and use the designated printer extension. You can also attach the receipt to the corresponding revenue record using the Link column.

Recording an expense for your short-term rental business
Record the expenses you incur for your Airbnb business by indicating the date of the expense, a description of the purchase, the amount incurred, the expense category, and the room or flat associated with your monetary outflow. You can always attach your receipts using the Link column.
Airbnb template for multi-currency accounting management
在此文中
Airbnb template for multi-currency accounting management
Airbnb template for multi-currency accounting management
Manage your business on Airbnb or other similar platform with this double-entry accounting template featuring multi-currency management. You'll find all the features of the free template, plus the ability to manage multiple assets.
直接在网页中打开Banana财务会计+
无需任何安装,可以直接在您的浏览器上运行 Banana财务会计+。客制化您的模板,输入发生业务并将文件保存在您的电脑上。
在浏览器中打开模板 Open tutorial in WebApp模板文件
This template is useful for comprehensive and efficient accounting management for Airbnb hosts who need a system that supports double-entry bookkeeping and handles multiple currencies. Banana Accounting Plus provides a wide range of features to track the income and expenses of your short-term rental business.
Banana Accounting Plus is an advanced accounting software that is superior to Excel, yet it is simpler and more cutting-edge, catering to the common needs of Airbnb hosts. The accounting template has been specifically designed to offer a comprehensive and customizable solution for the financial management of your Airbnb properties. It allows you to track expenses, record income, monitor cash flow and much more.
The key features of this accounting template for Airbnb include:
- Asset Management: this template encompasses all the features of the free template for Airbnb, Booking.com, Vrbo and similar hosting platforms and provides an advanced solution for those with greater needs. It allows you to manage unlimited assets compared to the free template.
- Double-Entry Bookkeeping: the template adheres to the fundamental accounting principle of double-entry bookkeeping, ensuring the accuracy and correctness of your financial records.
- Multi-Currency Management: if you manage Airbnb properties using different currencies, Banana Accounting enables you to record and track income and expenses in different currencies, simplifying international financial management.
- Advanced Reporting: the software offers the ability to generate detailed reports on your finances, including profit and loss statements, account statements, balance sheets and detailed budgets. These reports provide you with a comprehensive overview of the performance of your Airbnb properties.
- User-Friendly: the software is designed to be user-friendly, even for those new to double-entry bookkeeping or without extensive accounting experience. The accounting template is intuitive, and the extensive available online documentation guides you step-by-step in managing your finances.
Banana Accounting Plus is intuitive, easy to use and simplifies your accounting management for Airbnb.
Example of a multi-currency income transaction for hosts
Here's how to use the multi-currency feature of Banana Accounting Plus:
- Set the desired currency exchange rate through the Exchange Rates table.
- Perform the accounting entry by entering date, description, bank of the currency received, income account, amount in the currency received and specify the currency received. Banana Accounting Plus will automatically calculate the amount in the main currency used for managing your Airbnb accounting.

Image of the Exchange Rates table
Image of the Transactions table where to record the income received from Airbnb or similar platform.
Accounting templates with crypto currencies
Accounting with crypto currencies Bitcoin (cash)
在此文中
Accounting with crypto currencies Bitcoin (cash)
Accounting with crypto currencies Bitcoin (cash)
模板预览
Shop XX
Basic Currency: BTC
Cash Manager
| Group | Account | Description | Sum In |
|---|---|---|---|
| Cash | Cash | ||
| Group | Category | Description | Sum In |
|---|---|---|---|
| OPERATING RESULT | |||
| INCOME | |||
| Sales | Sales | Total Income | |
| Withdrawal from CA | Withdrawal from current account | Total Income | |
| Services | Services | Total Income | |
| Other | Other | Total Income | |
| Total Income | TOTAL INCOME | Result | |
| EXPENSES | |||
| Tranfers to Post Account | Tranfers to post office account | Total Expenses | |
| Stamps | Purchase stamps | Total Expenses | |
| Mail Letters | Mail letters and packages | Total Expenses | |
| Mailing Supplies | Mailing supplies | Total Expenses | |
| Stationery & Appliances | Stationery, appliances | Total Expenses | |
| Cleaning | Cleaning | Total Expenses | |
| Rent | Rent | Total Expenses | |
| Energy | Electricity, water | Total Expenses | |
| Telephone and Fax | Telephone and fax | Total Expenses | |
| Real estate upkeep | Real estate upkeep | Total Expenses | |
| Window Dressing | Window dressing | Total Expenses | |
| Publicity | Publicity, flyers | Total Expenses | |
| Agency Fees | Agency fees | Total Expenses | |
| Payment for Goods | Payment for goods | Total Expenses | |
| Salaries and Personal Loans | Salaries and personal loans | Total Expenses | |
| Fees and other Permits | Fees and other permits | Total Expenses | |
| Total Expenses | TOTAL EXPENSES | Result | |
| Result | RESULT | ||
| COST AND PROFIT CENTERS | |||
| DIVISION | |||
| .S | Shop and personnel management | T1 | |
| .G | Goods management | T1 | |
| .I | Investments | T1 | |
| T1 | TOTAL DIVISION | ||
Income & Expense Accounting with crypto currencies Bitcoin
在此文中
Income & Expense Accounting with crypto currencies Bitcoin
Income & Expense Accounting with crypto currencies Bitcoin
模板预览
Company XXX
Basic Currency: BTC
Income & Expense accounting
| Group | Account | Description | Sum In |
|---|---|---|---|
| ESTATE | |||
| Cash | Cash | Total | |
| Post | Post office current account | Total | |
| Bank 1 | Bank 1 | Total | |
| Clients | Clients | Total | |
| Prepaid Taxes | Prepaid taxes | Total | |
| Inventory | Inventory | Total | |
| Transitory Assets | Transitory assets | Total | |
| Machinery | Machinery and appliances | Total | |
| Office Furniture | Office furniture | Total | |
| Computer | Computer | Total | |
| Software | Software | Total | |
| Car | Car | Total | |
| Real Estate | Real Estate | Total | |
| Suppliers | Suppliers | Total | |
| Bank loan c/c | Bank loan c/c | Total | |
| Total | TOTAL |
| Group | Category | Description | Sum In |
|---|---|---|---|
| OPERATING RESULT | |||
| INCOME | |||
| Income from Services | Income from services | Total Income | |
| Income from Sales | Income from sales | Total Income | |
| Other Income | Other income | Total Income | |
| Total Income | TOTAL INCOME | Result | |
| EXPENSES | |||
| Purchase Goods | Purchase goods for resale | Total Expenses | |
| Salaries | Salaries | Total Expenses | |
| Social Contributions | Social contributions | Total Expenses | |
| Pension Fund | Pension fund | Total Expenses | |
| Accident Insurance | Accident insurance | Total Expenses | |
| Health Insurance | Health insurance | Total Expenses | |
| Rent | Rent | Total Expenses | |
| Machinery and Appliances | Upkeep machinery and appliances | Total Expenses | |
| Car Expenses | Car expenses | Total Expenses | |
| Other Insurances | Other insurances | Total Expenses | |
| Fees | Fees | Total Expenses | |
| Electricity | Electricity | Total Expenses | |
| Office Supplies | Office supplies | Total Expenses | |
| Telephone, Fax | Telephone, Fax | Total Expenses | |
| Mailing Fees | Mailing fees | Total Expenses | |
| Publicity | Publicity | Total Expenses | |
| Interest on Bank Loan | Interest on bank loan | Total Expenses | |
| Bank and CC Fees | Bank and current account fees | Total Expenses | |
| Depreciation Machinery | Depreciation machinery and appliances | Total Expenses | |
| Depreciation real estate | Ammortize real estate | Total Expenses | |
| Taxes | Taxes | Total Expenses | |
| Total Expenses | TOTAL EXPENSES | Result | |
| Result | RESULT | ||
| COST AND PROFIT CENTERS | |||
| DIVISION CAR EXPENSES | |||
| ;7000 | Petrol | C1 | |
| ;7001 | Insurance, other fees | C1 | |
| ;7002 | Repairs | C1 | |
| C1 | TOTAL DIVISION CAR EXPENSES | ||
Double-Entry Accounting with crypto currencies Bitcoin
在此文中
Double-Entry Accounting with crypto currencies Bitcoin
Double-Entry Accounting with crypto currencies Bitcoin
模板预览
Company XX
Basic Currency: BTC
Double-entry
| Group | Account | Description | Sum In | Gr1 |
|---|---|---|---|---|
| BALANCE SHEET | ||||
| ASSETS | ||||
| Cash | Cash | Total Assets | ||
| Post | Post office current account | Total Assets | ||
| Bank 1 | Bank 1 | Total Assets | ||
| Clients | Clients | Total Assets | ||
| Total Clients | Total Clients | Total Assets | 1 | |
| Prepaid Taxes | Prepaid taxes | Total Assets | ||
| Inventory | Inventory | Total Assets | ||
| Transitory Assets | Transitory assets | Total Assets | ||
| Machinery & Appliances | Machinery and appliances | Total Assets | ||
| Office Forniture | Office furniture | Total Assets | ||
| Computer | Computer | Total Assets | ||
| Software | Software | Total Assets | ||
| Car | Car | Total Assets | ||
| Real Estate | Real Estate | Total Assets | ||
| Total Assets | TOTAL ASSETS | 00 | 1 | |
| LIABILITIES | ||||
| Suppliers | Suppliers | Total Liabilities | ||
| Total Suppliers | Total Suppliers | Total Liabilities | 1 | |
| Bank Loan c/c | Bank loan c/c | Total Liabilities | ||
| Transitory Liabilities | Transitory liabilities | Total Liabilities | ||
| Start-up Capital | Start-up capital | Total Liabilities | ||
| Private Account | Private account | Total Liabilities | ||
| Reserves | Reserves | Total Liabilities | ||
| Profit or Loss forward | Profit or loss brought forward | Total Liabilities | ||
| Profit or loss of the current year | Profit or loss of the current year | Total Liabilities | 1 | |
| Total Liabilities | TOTAL LIABILITIES | 00 | 1 | |
| 1 | ||||
| PROFIT & LOSS STATEMENT | ||||
| REVENUE | ||||
| Income from Services | Income from services | Total Revenue | ||
| Income from Sales | Income from sales | Total Revenue | ||
| Other Income | Other income | Total Revenue | ||
| Total Revenue | TOTAL REVENUE | 02 | ||
| EXPENSES | ||||
| Purchase Goods | Purchase goods for resale | Total Expenses | ||
| Salaries | Salaries | Total Expenses | ||
| Social Contributions | Social contributions | Total Expenses | ||
| Pension Fund | Pension fund | Total Expenses | ||
| Accident Insurance | Accident insurance | Total Expenses | ||
| Health Insurance | Health insurance | Total Expenses | ||
| Rent | Rent | Total Expenses | ||
| Upkeep Machinery | Upkeep machinery and appliances | Total Expenses | ||
| Car Expenses | Car expenses | Total Expenses | ||
| Other Insurances | Other insurances | Total Expenses | ||
| Fees | Fees | Total Expenses | ||
| Electricity | Electricity | Total Expenses | ||
| Office Supplies | Office supplies | Total Expenses | ||
| Telephone, Fax | Telephone, Fax | Total Expenses | ||
| Mailing Fees | Mailing fees | Total Expenses | ||
| Publicity | Publicity | Total Expenses | ||
| Interest on Bank Loan | Interest on bank loan | Total Expenses | ||
| Bank and CC Fees | Bank and current account fees | Total Expenses | ||
| Depreciation Machinery | Depreciation machinery and appliances | Total Expenses | ||
| Depreciation Real Estate | Depreciation real estate | Total Expenses | ||
| Taxes | Taxes | Total Expenses | ||
| Total Expenses | TOTAL EXPENSES | 02 | 1 | |
| 02 | Profit(-) Loss(+) from Profit & Loss Statement | Profit or loss of the current year | 1 | |
| 00 | Difference should be = 0 (blank cell) | |||
| CLIENTS/SUPPLIERS REGISTER | ||||
| Clients | ||||
| CL.001 | Company 1 | 10A | ||
| CL.002 | Company 2 | 10A | ||
| CL.003 | Company 3 | 10A | ||
| 10A | Total Clients | Total Clients | 1 | |
| Suppliers | ||||
| SU.001 | Company 1 | 20A | ||
| SU.002 | Company 2 | 20A | ||
| SU.003 | Company 3 | 20A | ||
| 20A | Total Suppliers | Total Suppliers | 1 | |
| COST AND PROFIT CENTERS | ||||
| Division car expenses | ||||
| .PET | Petrol | CE | ||
| .INS | Insurance, other fees | CE | ||
| .REP | Repairs | CE | ||
| CE | Total Division car expenses | 1 | ||
Double-Entry Accounting for digital currencies Bitcoin and Ethereum (Base Currency ETH)
在此文中
Double-Entry Accounting for digital currencies Bitcoin and Ethereum (Base Currency ETH)
Double-Entry Accounting for digital currencies Bitcoin and Ethereum (Base Currency ETH)
Template for professional multi currency accounting software for digital currencies with up to 19 digit. Easily mix Bitcoin, Ethereum or any other digital or traditional currency.
模板预览
Company XX
Basic Currency: BTC
Double-entry with foreign currencies
| Group | Account | Description | Currency | Sum In | Gr1 |
|---|---|---|---|---|---|
| BALANCE SHEET | |||||
| ASSETS | |||||
| Cash | Cash | USD | Total Assets | ||
| Bank CHF | Bank CHF | CHF | Total Assets | ||
| Bank USD | Bank USD | USD | Total Assets | ||
| Bank EUR | Bank EUR | EUR | Total Assets | ||
| Bitcoins | Bitcoins | BTC | Total Assets | ||
| Ethereum | Ethereum | ETH | Total Assets | ||
| Clients | Clients | USD | Total Assets | ||
| Total Clients | Total Clients | Total Assets | 1 | ||
| Prepaid taxes | Prepaid taxes | USD | Total Assets | ||
| Inventory | Inventory | USD | Total Assets | ||
| Transitory assets | Transitory assets | USD | Total Assets | ||
| Machinery | Machinery and applicances | USD | Total Assets | ||
| Office furniture | Office furniture | USD | Total Assets | ||
| Computer | Computer | USD | Total Assets | ||
| Software | Software | USD | Total Assets | ||
| Car | Car | USD | Total Assets | ||
| Real Estate | Real Estate | USD | Total Assets | ||
| Total Assets | TOTAL ASSETS | 00 | 1 | ||
| LIABILITIES | |||||
| Suppliers | Suppliers | USD | Total Liabilities | ||
| Total Suppliers | Total Suppliers | Total Liabilities | 1 | ||
| Bank loan c/c | Bank loan c/c | USD | Total Liabilities | ||
| Transitory liabilities | Transitory liabilities | USD | Total Liabilities | ||
| Start-up capital | Start-up capital | USD | Total Liabilities | ||
| Private account | Private account | USD | Total Liabilities | ||
| Reserves | Reserves | USD | Total Liabilities | ||
| Profit or loss forward | Profit or loss brought forward | USD | Total Liabilities | ||
| Profit or loss of the current year | Profit or loss of the current year | Total Liabilities | 1 | ||
| Total Liabilities | TOTAL LIABILITIES | 00 | 1 | ||
| 1 | |||||
| PROFIT/LOSS STATEMENT | |||||
| REVENUE | |||||
| Income from services | Income from services | USD | Total Revenue | ||
| Income from sales | Income from sales | USD | Total Revenue | ||
| Other income | Other income | USD | Total Revenue | ||
| Exchange rate profit | Exchange rate profit | USD | Total Revenue | ||
| Exchange rate differences | Exchange rate differences | USD | Total Revenue | ||
| Total Revenue | TOTAL REVENUE | 02 | |||
| EXPENSES | |||||
| Purchase Goods | Purchase goods for resale | USD | Total Expenses | ||
| Salaries | Salaries | USD | Total Expenses | ||
| Social contributions | Social contributions | USD | Total Expenses | ||
| Pension fund | Pension fund | USD | Total Expenses | ||
| Accident insurance | Accident insurance | USD | Total Expenses | ||
| Health insurance | Health insurance | USD | Total Expenses | ||
| Rent | Rent | USD | Total Expenses | ||
| Upkeep machinery and appliances | Upkeep machinery and appliances | USD | Total Expenses | ||
| Car expenses | Car expenses | USD | Total Expenses | ||
| Other insurances | Other insurances | USD | Total Expenses | ||
| Fees | Fees | USD | Total Expenses | ||
| Electricity | Electricity | USD | Total Expenses | ||
| Office supplies | Office supplies | USD | Total Expenses | ||
| Telephone, Fax | Telephone, Fax | USD | Total Expenses | ||
| Mailing fees | Mailing fees | USD | Total Expenses | ||
| Publicity | Publicity | USD | Total Expenses | ||
| Interest on bank loan | Interest on bank loan | USD | Total Expenses | ||
| Bank and current account fees | Bank and current account fees | USD | Total Expenses | ||
| Depreciation machinery | Depreciation machinery and appliances | USD | Total Expenses | ||
| Depreciation real estate | Depreciation real estate | USD | Total Expenses | ||
| Taxes | Taxes | USD | Total Expenses | ||
| Exchange rate loss | Exchange rate loss | USD | Total Expenses | ||
| Total Expenses | TOTAL EXPENSES | 02 | 1 | ||
| 02 | Profit(-) Loss(+) from Profit & Loss Statement | Profit or loss of the current year | 1 | ||
| 00 | Difference should be = 0 (blank cell) | ||||
| CLIENTS/SUPPLIERS REGISTER | |||||
| Clients | |||||
| CL.001 | Company 1 | USD | 10A | ||
| CL.002 | Company 2 | USD | 10A | ||
| CL.003 | Company 3 | USD | 10A | ||
| 10A | Total Clients | Total Clients | 1 | ||
| Suppliers | |||||
| SU.001 | Company 1 | EUR | 20A | ||
| SU.002 | Company 2 | USD | 20A | ||
| SU.003 | Company 3 | USD | 20A | ||
| 20A | Total Suppliers | Total Suppliers | 1 | ||
| COST AND PROFIT CENTERS | |||||
| DIVISION CAR EXPENSES | |||||
| .PET | Petrol | USD | C1 | ||
| .INS | Insurance, other fees | USD | C1 | ||
| .REP | Repairs | USD | C1 | ||
| C1 | TOTAL DIVISION CAR EXPENSES | 1 | |||
| Ref.Currency | Currency | Text |
|---|---|---|
| BTC | EUR | Euro |
| BTC | CHF | Swiss Francs |
| BTC | USD | US Dollar |
| BTC | ETH | Ether |
Double-Entry Accounting for digital currencies Bitcoin and Ethereum (Base currency USD)
在此文中
Double-Entry Accounting for digital currencies Bitcoin and Ethereum (Base currency USD)
Double-Entry Accounting for digital currencies Bitcoin and Ethereum (Base currency USD)
Template for professional multi currency accounting software for digital currencies with up to 19 digit. Easily mix Bitcoin, Ethereum or any other digital or traditional currency.
模板预览
Company XX
Basic Currency: USD
Double-entry with foreign currencies
| Group | Account | Description | Currency | Sum In | Gr1 |
|---|---|---|---|---|---|
| BALANCE SHEET | |||||
| ASSETS | |||||
| Cash | Cash | USD | Total Assets | ||
| Post | Post office current account | USD | Total Assets | ||
| Bank USD | Bank USD | USD | Total Assets | ||
| Bank EUR | Bank EUR | EUR | Total Assets | ||
| Bitcoins | Bitcoins | BTC | Total Assets | ||
| Ethereum | Ethereum | ETH | Total Assets | ||
| Clients | Clients | USD | Total Assets | ||
| Total Clients | Total Clients | Total Assets | 1 | ||
| Prepaid taxes | Prepaid taxes | USD | Total Assets | ||
| Inventory | Inventory | USD | Total Assets | ||
| Transitory assets | Transitory assets | USD | Total Assets | ||
| Machinery | Machinery and applicances | USD | Total Assets | ||
| Office furniture | Office furniture | USD | Total Assets | ||
| Computer | Computer | USD | Total Assets | ||
| Software | Software | USD | Total Assets | ||
| Car | Car | USD | Total Assets | ||
| Real Estate | Real Estate | USD | Total Assets | ||
| Total Assets | TOTAL ASSETS | 00 | 1 | ||
| LIABILITIES | |||||
| Suppliers | Suppliers | USD | Total Liabilities | ||
| Total Suppliers | Total Suppliers | Total Liabilities | 1 | ||
| Bank loan c/c | Bank loan c/c | USD | Total Liabilities | ||
| Transitory liabilities | Transitory liabilities | USD | Total Liabilities | ||
| Start-up capital | Start-up capital | USD | Total Liabilities | ||
| Private account | Private account | USD | Total Liabilities | ||
| Reserves | Reserves | USD | Total Liabilities | ||
| Profit or loss forward | Profit or loss brought forward | USD | Total Liabilities | ||
| Profit or loss of the current year | Profit or loss of the current year | Total Liabilities | 1 | ||
| Total Liabilities | TOTAL LIABILITIES | 00 | 1 | ||
| 1 | |||||
| PROFIT/LOSS STATEMENT | |||||
| REVENUE | |||||
| Income from services | Income from services | USD | Total Revenue | ||
| Income from sales | Income from sales | USD | Total Revenue | ||
| Other income | Other income | USD | Total Revenue | ||
| Exchange rate profit | Exchange rate profit | USD | Total Revenue | ||
| Exchange rate differences | Exchange rate differences | USD | Total Revenue | ||
| Total Revenue | TOTAL REVENUE | 02 | |||
| EXPENSES | |||||
| Puchase goods | Purchase goods for resale | USD | Total Expenses | ||
| Salaries | Salaries | USD | Total Expenses | ||
| Social contributions | Social contributions | USD | Total Expenses | ||
| Pension fund | Pension fund | USD | Total Expenses | ||
| Accident insurance | Accident insurance | USD | Total Expenses | ||
| Health insurance | Health insurance | USD | Total Expenses | ||
| Rent | Rent | USD | Total Expenses | ||
| Upkeep machinery and appliances | Upkeep machinery and appliances | USD | Total Expenses | ||
| Car expenses | Car expenses | USD | Total Expenses | ||
| Other insurances | Other insurances | USD | Total Expenses | ||
| Fees | Fees | USD | Total Expenses | ||
| Electricity | Electricity | USD | Total Expenses | ||
| Office supplies | Office supplies | USD | Total Expenses | ||
| Telephone, Fax | Telephone, Fax | USD | Total Expenses | ||
| Mailing fees | Mailing fees | USD | Total Expenses | ||
| Publicity | Publicity | USD | Total Expenses | ||
| Interest on bank loan | Interest on bank loan | USD | Total Expenses | ||
| Bank and current account fees | Bank and current account fees | USD | Total Expenses | ||
| Depreciation machinery | Depreciation machinery and appliances | USD | Total Expenses | ||
| Depreciation real estate | Depreciation real estate | USD | Total Expenses | ||
| Taxes | Taxes | USD | Total Expenses | ||
| Exchange rate loss | Exchange rate loss | USD | Total Expenses | ||
| Total Expenses | TOTAL EXPENSES | 02 | 1 | ||
| 02 | Profit(-) Loss(+) from Profit & Loss Statement | Profit or loss of the current year | 1 | ||
| 00 | Difference should be = 0 (blank cell) | ||||
| CLIENTS/SUPPLIERS REGISTER | |||||
| Clients | |||||
| CL.001 | Company 1 | USD | 10A | ||
| CL.002 | Company 2 | USD | 10A | ||
| CL.003 | Company 3 | USD | 10A | ||
| 10A | Total Clients | Total Clients | 1 | ||
| Suppliers | |||||
| SU.001 | Company 1 | EUR | 20A | ||
| SU.002 | Company 2 | USD | 20A | ||
| SU.003 | Company 3 | USD | 20A | ||
| 20A | Total Suppliers | Total Suppliers | 1 | ||
| COST AND PROFIT CENTERS | |||||
| DIVISION CAR EXPENSES | |||||
| .PET | Petrol | USD | C1 | ||
| .INS | Insurance, other fees | USD | C1 | ||
| .REP | Repairs | USD | C1 | ||
| C1 | TOTAL DIVISION CAR EXPENSES | 1 | |||
| Ref.Currency | Currency | Text |
|---|---|---|
| USD | EUR | Euro |
| USD | CHF | Swiss Francs |
| USD | BTC | Bitcoin |
| USD | ETH | Ether |
Essential Expense Manager PDF report with embedded receipts
在此文中
Essential Expense Manager PDF report with embedded receipts
Essential Expense Manager PDF report with embedded receipts
Easily enter and categorize you expenses and create a PDF report with embedded receipts. A simple and effective solution for all expenses reporting needs for SME and non-profit. It's totally free for up 70 expense entries for reporting.
直接在网页中打开Banana财务会计+
无需任何安装,可以直接在您的浏览器上运行 Banana财务会计+。客制化您的模板,输入发生业务并将文件保存在您的电脑上。
在浏览器中打开模板 Open tutorial in WebApp模板文件
Improving how employee expenses are managed is crucial for all businesses.
Whether employees are traveling for work or working from home, keeping track of their expenses and making sure they get reimbursed correctly has become a complex task.
Banana Accounting expense manager functionality to create a PDF dossier is essential and cost-effective for the majority of small and medium-sized businesses. It helps track expenses, improves transparency and makes it smoother for employees to interact with the company's accounting department.
All in one PDF report with embedded receipts
Banana Accounting create a PDF report with embedded receipts. The PDF file includes everything is necessary for reporting, approval and reimbursement.
- The list of expenses with all information necessary and the link to receipt.
- The report of the categorized expenses, for accounting purposes.
- The scanned receipt's files.
PDF file can embed other files. If you don't know just open this example PDF file and click on the link (look the link icons on the left in the image below), so that the receipt document will directly open (some browser don't show the files, better use Adobe Acrobat Reader that is free to use).
Totally free for up to 70 expense entries
The Banana Accounting template is designed to benefit companies of all sizes. The expense manager template is a software entirely free for up to 70 expense entries, making it a very accessible solution.
How to start
Using this Banana Accounting functionality allows you to obtain your PDF dossier with expenses categorized and embedded in a simple and immediate way:
- Install Banana Accounting
- Open the template file and save to a directory, where you also scan your documents.
- Scan your receipts or invoices (Banana Accounting does not perform the scanning).
- Enter the incurred expenses in the Transaction table and add a Link to the scanned receipt file.
- With File menu > Create Pdf Dossier create the PDF report (check the Include attachments).
- Transmit the file for reimbursement.
Now you'll be ready to send your PDF dossier by email to the accounting department, for approval and reimbursement.
This workflow is essential and cost-effective for the majority of small and medium-sized businesses.
Add the payment methods used by employees
If you wish, you can manage the payment methods used for expenses through the CC3 column.
To enable it, double-click on the column headers in the Transactions table. In the window that opens, on the left, enable the display of the Cc3 column and confirm with the Ok button.
Manage the different payment methods from the Categories table by adding the accounting accounts with a semicolon in front. You can add as many payment methods as you prefer.
Add the quantity columns to manage travel kilometers
To manage travel expenses based on the distance traveled, it could be useful to enable the display of columns related to quantities.
To enable them, double-click on the column headers in the Transactions table. In the window that opens, on the left, enable the display of the columns Quantity, ReferenceUnit, UnitPrice, and confirm with the Ok button.
Remember to enter Unit Price in the Transactions table with a negative sign.
Additional features of the Essential Expense Manager
Easy Expense Logging: the core of this tool is a user-friendly interface. Employees can quickly record their expenses by entering the date, category, amount and payment method. This reduces mistakes and ensures accurate data entry.
Digital Receipts: instead of using paper receipts, the software lets employees attach digital copies of receipts. This prevents losing receipts and keeps expense records secure.
Detailed PDF Reports: the software is great at creating comprehensive expense reports. These reports include all embedded receipts in a single PDF file, which can be easily shared with accountants through email. The reports break down expenses, categories and receipts, promoting transparency.
Customizable Categories: the software lets administrators customize expense categories to fit the company's needs. This ensures that expenses are organized in a way that matches the company's reporting and analysis requirements.
Easy Access: the expense manager can be shared through email, which is helpful for remote employees or those who often travel for work.
Data Privacy: it's important to note that the data entered into Banana Accounting is not used for commercial purposes. Your information remains confidential, offline and is not repurposed in any way.
WooCommerce Products Export-Import [BETA]
在此文中
WooCommerce Products Export-Import [BETA]
WooCommerce Products Export-Import [BETA]
This extension allows you to create your own inventory based upon the products listed in WooCommerce. You may update your inventory in Banana Accounting by aligning it with the details of products already listed on WooCommerce and export your inventory product data in a format already set up to import into WooCommerce to start selling online.
WooCommerce extension description
This extension for importing and exporting products sold on WooCommerce online shop simplifies and optimizes the integration between your online store and Banana Accounting software.
The extension either allows the export of products already listed in your inventory from Banana Accounting to your WooCommerce online store, or may become an intuitive and efficient solution to easily allow you to import products directly from your online store into Banana Accounting.
Banana Accounting is superior to Excel, allowing you to swiftly edit product details at any time and it guarantees that the information remains aligned to your online store on WooCommerce.
The Banana Accounting extension offers you the opportunity to export product data already present in your Banana Accounting inventory in a format already prepared for import into WooCommerce. This streamlines the input and/or management of products in your online store, enabling you to maintain coherence and consistency between the two platforms and to begin selling online more seamlessly.
As it is crucial to manage product information accurately and effortlessly in your online store and inventory, this extension allows you to do so in a simple and secure manner. With the export file obtained from the WooCommerce platform, you can easily create your inventory in Banana Accounting or update existing products directly in Banana Accounting to align them with those present on your online store.
Both functions eliminate the need for lengthy and complex manual procedures and reduce the risk of transcription errors, ensuring data accuracy and efficiency.
This solution is suitable for those who want to manage the inventory in a simple way, exporting or importing to WooCommerce whenever they desire. It is not suitable for those looking for a cloud solution that automatically synchronizes warehouse management with WooCommerce.
Banana Accounting key features
Easy: the Banana Accounting software is easy to use and every file can be shared through email, which is helpful for a easy support too.
Privacy: it's important to note that the data entered into Banana Accounting is not used for commercial purposes. Your information remains confidential, offline and is not repurposed in any way.
Beta version
This extension is published in BETA version. We recommend creating a backup copy of the inventory file. Having regular file backups is always useful in any context. This WooCommerce extension require a subscription to Banana Accounting Plus Advanced version.
Primary Key Used
The Id column from Banana's Items table will be exported and used as the primary key for import and it must contain the product's SKU reference of WooCommerce online shop.
Those who already have a warehouse in Banana Accounting can replace the codes in the Id column using the Rename function from Banana's Data menu. This function will automatically replace the Id value even in the Transactions table.
Create/Update products from WooCommerce
The Create/Update products from WooCommerce function will create the products exported from WooCommerce (CSV file format) in the Items table of the inventory in Banana Accounting if they do not exist. If products with the same Id value already exist, it will update the values in the Description, Quantity begin and Unit Price columns in the Items table with the information present in the exported file from WooCommerce.
Export products for WooCommerce
The Export products for WooCommerce function will export data from the Id, Description, Quantity balance and Unit Price columns in the Items table into a CSV file format, ready to be imported into WooCommerce.