Modelos Universal Noprofit
INPAS Standard Templates
Understanding INPAS and the benefits of Banana Accounting
The International Non-Profit Accounting Standard (INPAS) is the first international accounting standard developed specifically for non-profit organisations (NPOs). Published in October 2025, it provides a common framework for preparing clear, consistent and transparent financial reports, helping organisations strengthen accountability and build trust with donors, funders and other stakeholders.
INPAS addresses the specific financial reporting needs of non-profit organisations, including the management of restricted and unrestricted funds, grants, donations, project expenses and financial reporting. Its objective is to help organisations clearly demonstrate where their resources come from, how they are managed and how they are used to achieve their mission.
Benefits of Banana Accounting for INPAS
Banana Accounting simplifies accounting and helps non-profit organisations prepare the financial information required by INPAS, using ready-to-use accounting templates designed for the standard.
With Banana Accounting, organisations can:
- Manage their accounting easily: record income, expenses, donations, grants, assets and liabilities in a single accounting file.
- Track restricted and unrestricted funds: use segments to monitor the financial activities and balances associated with individual funds.
- Monitor projects and activities: use cost and profit centres to analyse income and expenses for each project without creating separate accounting files.
- Manage donors and donations: track contributions from individual donors and generate personalised donation statements using an available extension.
- Generate financial statements: prepare the Statement of Financial Position and Statement of Income and Expenses directly from the accounting records.
- Simplify financial reporting: reduce repetitive work and organise the information needed to complete additional INPAS financial statements and disclosures.
For example, when an organisation receives a donation for a specific project, Banana Accounting can record the transaction while simultaneously identifying the relevant fund, project and donor.
Banana Accounting and the free INPAS Excel template work together to support the preparation of financial reports. Banana manages the accounting records and generates the main accounting statements, while Excel helps complete the additional financial statements and explanatory notes.
The templates support the preparation of INPAS financial reports but do not automatically guarantee compliance. Each organisation remains responsible for applying the applicable requirements of the standard and completing its financial reporting.
INPAS key accounting documents
Statement of Financial Position
The balance sheet is an essential document that provides a detailed view of your organization's financial health, clearly showing assets, liabilities and net assets. Because of the flexibility of the INPAS standard, you can present the financial statements either vertically or horizontally, tailoring them to the specific needs of your nonprofit.
This document can be generated easily using Banana Accounting template.
Statement of Income and Expenses
This document shows your organization's income and expenses during a period. Proper management of the income statement is crucial to demonstrate how resources were used to achieve its mission-related objectives.
This document can be generated easily using Banana Accounting template.
Statement of Changes in Net Assets
This document is critical to understanding the changes that have occurred in net assets during the fiscal year. The INPAS standard provides a sequence of elements that transparently reflects the changes, making clear the impact of financial activities on the organization's assets.
Statement of Cash Flows
The cash flow statement, which shows cash flows, is essential for monitoring your organization's liquidity and ability to fund its activities. With our INPAS template, you can present this information in a clear and accessible way, improving transparency to donors and board members.
Explanatory notes
Explanatory notes are a mandatory part of INPAS financial statements. They include the basis of preparation, material accounting policies, information about individual funds and their movements, relevant grants and donations, delivery obligations where applicable, and other disclosures required by INPAS.
The notes must also include relevant comparative information for the previous reporting period.
Comparative information and Narrative reporting
INPAS requires comparative financial information for the previous reporting period.
Full INPAS compliance also requires a narrative report describing the NPO's mission, activities, performance and principal risks. The narrative report can be prepared separately, for example in Word, but must be included as part of the NPO's general purpose financial report to declare full INPAS compliance.
During the first two years following transition to INPAS, an NPO may declare compliance with the financial statement requirements only, subject to the transitional provisions.
References
- International Financial Reporting For Non Profit Organisations: https://www.inprf.org
INPAS reporting with segments and cost and profit centres
For a non-profit organisation (NPO), recording a payment is only the beginning. It also needs to know which fund the money belongs to, which project it supports and, when relevant, who provided it. Banana Accounting lets you add these details to the same transaction without creating a separate set of ordinary accounts for every fund, project or donor.
This helps an NPO organise the information needed for INPAS fund accounting, the analysis of expenses and fundraising cost disclosures. The software helps collect and analyse information. It does not, by itself, certify an INPAS-compliant financial report.
Segments: manage accounting by fund
INPAS requires non-profit organisations to distinguish between restricted and unrestricted funds.
With Banana Accounting, segments help you track each fund separately, without creating a different chart of accounts or accounting file for every fund.
A segment is simply a code added after an account to identify the fund to which the amount belongs.
The INPAS templates provided by Banana Accounting include:
- :Fund A, :Fund B and :Fund C: restricted funds used for specific purposes.
- :General: the unrestricted General Fund, used for resources without those restrictions.
You can add as many additional funds as needed.
Segments are defined in the Accounts table.
How to use segments
In the Transactions table, add the segment after the relevant account code.
For example, an organisation receives a restricted donation of EUR 727 for Fund A.
Double-entry accounting

- Debit account: Bank:Fund A
- Credit account: Grants restricted Project 1:Fund A
- Amount: 727.00
Income & Expense accounting

- Account: Bank:Fund A
- Category: Grants restricted Project 1:Fund A
- Income: 727.00
In both cases, Banana identifies the bank amount and the donation income as belonging to Fund A.
Practical rule: For ordinary transactions, add the same segment to both accounts when both amounts belong to the same fund. This helps you track the fund's assets, liabilities, income and expenses.
When transferring amounts between different funds, use the appropriate segment for each side of the transaction.
Segments do not require separate bank accounts. They simply help organise accounting information by fund.
How to view financial reports by fund
To view the financial information for each fund, use Reports > Accounting Report or Enhanced Balance Sheet by Groups, and activate Subdivision by Segment.
Important: The total displayed in an individual segment card does not necessarily represent the fund's balance. Depending on how transactions are recorded, amounts may cancel each other out or appear twice. Use reports subdivided by segment to examine the different accounting positions and reconcile each fund's balance.
Cost and profit centres: track projects, activities and donors
While segments help you identify which fund a transaction belongs to, cost and profit centres help you monitor individual projects, activities and donors.
For example, an association may want to know how much money it received for a project, how much it spent and who made the donations.
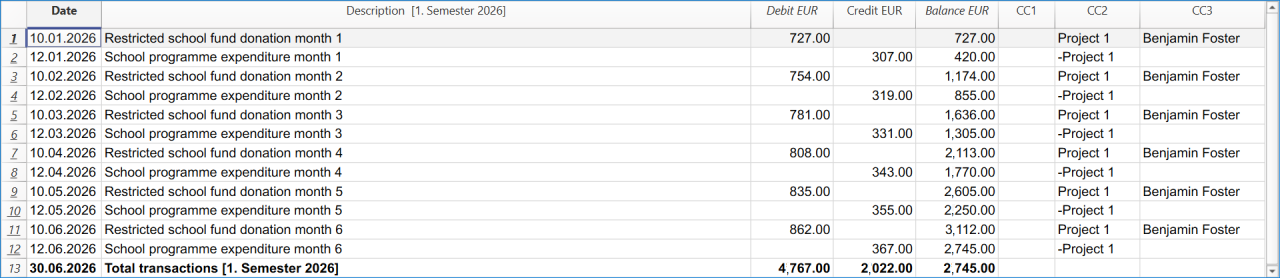
With Banana Accounting, you can track this information directly in your accounting transactions, without creating separate accounts or accounting files for each project or donor.
How to use cost and profit centres
Banana provides three independent columns for cost and profit centres:
- CC1 – Activities or campaigns: for example .Campaign 1.
- CC2 – Projects: for example ,Project 1.
- CC3 – Donors: for example ;Benjamin Foster.
Each column can contain as many cost centres as needed. However, only one cost centre per column can be assigned to a single transaction. The same transaction can include up to three cost centres, one in each column (CC1, CC2 and CC3). The INPAS templates use CC2 for projects and CC3 for donors, while CC1 remains available for other activities.
Centres are defined in the Accounts or Categories table using their corresponding prefix (dot, comma or semicolon).
In the Transactions table, simply enter the centre name without the prefix. For example, enter Project 1 in CC2 and Benjamin Foster in CC3.
You can use segments and cost and profit centres together in the same transaction to identify the fund, project and donor.
Track project income and expenses
Cost and profit centres can track income, expenses or both. You decide whether each transaction adds to or subtracts from the centre's total.
For example, an association receives a donation of EUR 727 for Project 1 and later spends EUR 307 on the same project.
Recording the donation:
- Amount: EUR 727
- CC2: Project 1 (adds EUR 727)
Recording the expense:

- Amount: EUR 307
- CC2: -Project 1 (subtracts EUR 307)
The centre automatically calculates the result: EUR 727 income − EUR 307 expenses = EUR 420 net result for Project 1.
As you record additional transactions, the project's total is updated automatically. This allows you to monitor its financial activity throughout the year.
The minus sign before the centre name determines whether the amount is subtracted from the centre's total. It does not change the ordinary accounting entry.
The same principle can be used to track donations by donor in CC3, including refunds or corrections.
In Income & Expense accounting, an optional setting can make cost-centre signs follow the categories. Use this setting only when it matches the way you want to calculate the totals.
Understanding cost and profit centre totals
A cost or profit centre shows only the transactions assigned to it. It provides an additional analysis without changing the ordinary accounting records.
When used consistently for project income and expenses, it helps you understand how much a project has received, spent and retained.
However, if the centre also includes advances, transfers or other balance-sheet movements, its total does not necessarily represent the project's operating result.
Cost and profit centres are useful for monitoring activities but do not replace the financial statements required by INPAS.
Supporting INPAS expense and fundraising disclosures
Ordinary expense accounts support the required analysis in the Statement of Income and Expenses, while cost/profit centres give an additional operational breakdown. For example, a centre for a fundraising campaign can collect the costs associated with that activity, and a project centre can collect the project's income and expenses. INPAS requires an appropriate expense analysis in the Income Statement; an internal cost-centre card does not replace it.
Under INPAS, fundraising costs may need to be reported by donation and grant fundraising, commercial/trading activities and investment management, including relevant direct, shared and support costs. Banana's accounts and analytical centres help identify the underlying entries, but allocation methods and the required gross disclosures must still be prepared and documented.
One transaction, three dimensions of information
On 10 January 2026, the association receives a restricted donation of EUR 727 from Benjamin Foster for Project 1 within Fund A.
In the Double-entry accounting tutorial, the transaction is recorded as follows:
- Date: 2026-01-10
- Description: Restricted school fund donation month 1
- Debit account: Bank:Fund A
- Credit account: Grants restricted Project 1:Fund A
- Amount: 727.00
- CC2 (project): Project 1
- CC3 (donor): Benjamin Foster
One transaction updates the ordinary accounts, identifies the restricted fund, links the donation to the project and associates the receipt with the donor.
The same principle applies to the unrestricted General Fund using the segment :General.
These dimensions are independent: a project can use more than one fund, and a fund can finance more than one project. This allows an NPO to maintain detailed information without unnecessarily multiplying its ordinary accounting accounts.
Generate donation statements for donors
Banana Accounting also helps non-profit organisations simplify donor administration by generating personalised donation statements directly from their accounting records.
With the Donation statement for Associations (Banana+) extension, an NPO can:
- Generate individual donation statements for a selected donor or multiple donors.
- Automatically calculate the total donations received during a selected period.
- Include the details of individual donation transactions.
- Personalise the statements with the organisation's logo, donor information and signature.
- Print or save the statements as PDF documents, which donors may use for tax purposes where permitted by applicable legislation.
Donors must be configured as CC3 cost centres in the accounting file to use this donation statement extension. This is already the structure used in the INPAS templates.
By assigning each donation to the appropriate donor in CC3, the association can reuse the same accounting information for donor tracking, financial analysis and the preparation of donation statements, avoiding duplicate data entry.
Before issuing donation statements, review the transactions assigned to each donor in CC3. Grant advances and other transactions may require separate treatment depending on their nature and the applicable tax rules.
The availability of tax deductions and the legal requirements for donation certificates depend on the country and the tax status of the organisation. Banana generates the document but does not determine its fiscal validity.
How to view the results
- Cost/profit-centre card: from Reports > Account/Category cards, select Cost centres to view the movements and analytical balance of a centre. The grouped totals are also visible in the appropriate Accounts or Categories section.
- Segment card: open the segment's account card to inspect the entries carrying that segment. Remember that its net movement may be zero or may include duplicated amounts, depending on how the transaction was classified.
- Report by segment: use Reports > Accounting Report or Enhanced Balance Sheet by Groups, then activate Subdivision by Segment. This is the appropriate way to examine the related assets, liabilities, income and expenses separately.
What Banana helps achieve under INPAS
Banana Accounting helps non-profit organisations simplify their daily accounting and organise the financial information needed for INPAS reporting.
With Banana, organisations can:
- Manage funds: track restricted and unrestricted funds, including movements and transfers between them.
- Monitor projects: analyse income, expenses and fundraising costs using cost and profit centres.
- Track donations: manage individual donors and generate personalised donation statements using an available extension.
- Generate financial reports: prepare the Statement of Financial Position and Statement of Income and Expenses, and collect information for additional INPAS statements and explanatory notes.
By keeping all accounting information in one file, Banana reduces manual work, avoids duplicate data entry and makes financial information easier to review.
Banana Accounting supports INPAS reporting but does not automatically guarantee compliance. Each organisation remains responsible for applying the standard correctly and completing the required financial statements, comparative information, explanatory notes and Narrative Report.
Managing restricted funds and grant advances with Banana Accounting
A restricted fund contains resources that must be used for a specified purpose under the relevant INPAS criteria. A fund is not necessarily a separate bank account, and it is not the same thing as a project or a donor. With Banana Accounting, you can use segments to identify funds, cost centres to monitor projects and donor centres to track individual contributors, all within the same accounting entries.
This guide uses illustrative examples from the INPAS Banana templates. The amounts are in EUR, and opening balances are assumed to be zero.
First, distinguish a restriction from a delivery obligation
Two donations may both be earmarked for a purpose, but they do not necessarily have the same accounting treatment:
- Restricted donation without a delivery obligation: a donor gives money for a particular purpose, without imposing a qualifying delivery obligation. When the NPO controls the money or has a right to receive it, the donation is generally recognised as income, attributed to the appropriate restricted fund.
- Grant with a delivery obligation: a funding agreement requires the NPO to complete an identifiable, enforceable activity or deliverable. If the money is received before that obligation is fulfilled, the amount is initially recorded as a liability, not grant income. Revenue is recognised when, or as, the obligation is fulfilled.
A restriction on how money may be spent does not automatically create a delivery obligation. The terms of the agreement must be assessed before choosing the entry.
Receiving a restricted donation without delivery obligations
On 10 January 2026, the association receives EUR 727 from Benjamin Foster for Project 1. The donation is restricted to Fund A, but does not include a qualifying delivery obligation.
Double-entry accounting
- Date: 2026-01-10
- Description: Restricted school fund donation month 1
- Debit account: Bank:Fund A
- Credit account: Grants restricted Project 1:Fund A
- Amount: 727.00
- CC2: Project 1
- CC3: Benjamin Foster
Income & Expense accounting
- Date: 2026-01-10
- Description: Restricted school fund donation month 1
- Income: 727.00
- Expenses: leave empty
- Account: Bank:Fund A
- Category: Grants restricted Project 1:Fund A
- CC2: Project 1
- CC3: Benjamin Foster
Result: EUR 727 increases the bank balance and is recognised as income attributable to Fund A.
Paying project expenses
On 12 January 2026, the association pays EUR 307 for school programme expenses.
Double-entry accounting
- Date: 2026-01-12
- Description: School programme expenditure month 1
- Debit account: Expenses Project 1:Fund A
- Credit account: Bank:Fund A
- Amount: 307.00
- CC2: -Project 1
- CC3: leave empty
Income & Expense accounting

- Date: 2026-01-12
- Description: School programme expenditure month 1
- Income: leave empty
- Expenses: 307.00
- Account: Bank:Fund A
- Category: Expenses Project 1:Fund A
- CC2: -Project 1
- CC3: leave empty
Result: considering these first two transactions alone, Fund A has EUR 727 of income and EUR 307 of expenses, producing a surplus of EUR 420. The CC2 analytical centre also shows EUR 420 because income is added and expenses are subtracted.
Receiving an advance with delivery obligations
On 11 February 2026, the association receives an advance of EUR 3,000 attributed to Olivia Reynolds. The funding agreement includes qualifying delivery obligations that have not yet been fulfilled.
Double-entry accounting

- Date: 2026-02-11
- Description: Fund B advance with enforceable delivery obligations
- Debit account: Bank:Fund B
- Credit account: Grant oblig. liability:Fund B
- Amount: 3,000.00
- CC2: leave empty
- CC3: Olivia Reynolds
Income & Expense accounting

- Date: 2026-02-11
- Description: Fund B advance with enforceable delivery obligations
- Income: 3,000.00
- Expenses: leave empty
- Account: Bank:Fund B
- Category: Grant oblig. liability:Fund B
- CC2: leave empty
- CC3: Olivia Reynolds
Result: the bank balance increases by EUR 3,000 and a corresponding liability is recognised. The advance is not yet grant revenue and does not increase Fund B's net assets.
In the Income & Expense model, Grant oblig. liability is an account defined in the Accounts table. Although it is entered in the Category column, the amount is reported as a liability rather than revenue.
CC2 is deliberately left empty because the project has not yet earned this income.
Recognising revenue after fulfilling delivery obligations
On 27 May 2026, the association achieves a milestone under the grant agreement and recognises EUR 1,200 as revenue.
Double-entry accounting

- Date: 2026-05-27
- Description: Recognition of part of Fund B advance, milestone achieved
- Debit account: Grant oblig. liability:Fund B
- Credit account: Grants restricted Project 2:Fund B
- Amount: 1,200.00
- CC2: Project 2
- CC3: leave empty
Income & Expense accounting

- Date: 2026-05-27
- Description: Recognition of part of Fund B advance, milestone achieved
- Income: 1,200.00
- Expenses: leave empty
- Account: Grant oblig. liability:Fund B
- Category: Grants restricted Project 2:Fund B
- CC2: Project 2
- CC3: leave empty
Result: EUR 1,200 is transferred from the grant liability to recognised income. No additional money enters the bank. After this transaction, EUR 1,800 of the original advance remains a liability.
The tutorial includes a second milestone of EUR 1,200 on 10 October 2026. After both milestones, the remaining liability relating to this EUR 3,000 advance is EUR 600.
How to interpret the accounting results
Considering only the first four example transactions, and not all other transactions recorded in the annual tutorial:
- Bank: EUR 3,420 (EUR 727 received, less EUR 307 paid, plus EUR 3,000 received in advance).
- Outstanding delivery obligation liability: EUR 1,800 after the first milestone.
- Recognised income: EUR 1,927 (EUR 727 for Fund A and EUR 1,200 for Fund B).
- Expenses: EUR 307 for Project 1.
- Net assets generated by these four transactions: EUR 1,620, consisting of EUR 420 for Fund A and EUR 1,200 for Fund B.
The advance is therefore correctly distinguished from revenue. It increases the bank balance immediately, but affects the reported income only when the related delivery obligations are fulfilled.
Fund transfers, opening balances and reporting
- No fictitious bank payments: moving an amount from unrestricted to restricted net assets is not automatically a movement of cash. Do not record a bank payment just to create a fund balance.
- Transfers must be permitted: INPAS allows transfers between funds only where legally permitted. Describe and reconcile them in the fund movement disclosures.
- General Fund: The INPAS tutorials include a dedicated :General segment for the unrestricted General Fund. This allows general transactions and transfers involving unrestricted resources to be identified separately from restricted funds. INPAS does not require this particular segment code; it is a practical organisational choice within Banana Accounting.
- Opening balances: opening balances assigned to individual segments may require dedicated segment opening entries or the appropriate carry-forward procedure in Banana.
- Fund reconciliation: for each relevant fund, explain its purpose and reconcile the opening balance, recognised income, expenses, other changes, permitted transfers and closing balance. Do not treat a segment card's total as the net assets of that fund.
INPAS reporting reminder
Fund accounting is covered by INPAS, while revenue from grants and donations with or without delivery obligations is covered by INPAS. Banana provides detailed ledger and reporting tools to prepare this information, but the NPO remains responsible for assessing its grant agreements, allocating transactions correctly, preparing the required statements and completing the explanatory notes.
International Non-Profit Accounting Standard - INPAS Standard Template
En este artículo
International Non-Profit Accounting Standard - INPAS Standard Template
International Non-Profit Accounting Standard - INPAS Standard Template
The INPAS International standard template for associations provides a comprehensive framework for organizing financial transactions and reporting for associations adhering to international standards.
Abrir en Banana WebApp
Abra Banana Contabilidad Plus en su navegador sin necesidad de instalación. Personaliza la plantilla, introduce las transacciones y guarda el archivo en tu ordenador.
Abrir plantilla en WebApp Abrir tutorial en WebAppDocumentación de la plantilla
The INPAS International template for associations provides a comprehensive framework for organizing financial transactions and reporting for associations adhering to international standards.
This chart of accounts template is designed to streamline accounting processes, ensure consistency in financial reporting and facilitate compliance with regulatory requirements. With a user-friendly format and customizable accounts name, associations can efficiently track income, expenses, assets and liabilities, enabling clear and transparent financial management. Whether managing donations, membership dues or program expenditures, this template offers flexibility and adaptability to suit the unique needs of diverse associations while promoting transparency and accountability in financial operations.
The NPO is responsible for ensuring that its financial reports comply with all applicable INPAS requirements. Using the template alone does not guarantee compliance.
Banana Accounting provides the accounting information needed to prepare the Statement of Financial Position and the Statement of Income and Expenses.
The Excel template supports the preparation of the remaining financial statements and explanatory notes. The narrative report can be prepared separately, for example in Word, but must be included as part of the NPO's general purpose financial report to declare full INPAS compliance.
Create your file
- Create a new file, starting from this template (Template ID +11255), using one of the methods explained.
- With the command File → File properties, set the period, the association name and the basic currency.
- With the command File → Save as, save the file. Enter the association name and year in the file name.
For example "no-profit-20YY.ac2".
See also Organize accounting files locally, online or in the cloud
Customize the Accounts table
Once you have entered the transactions, you can check the Accounts table. You will have an overview of your assets, liabilities, income and expenses, which allows you to keep your balance under control.
Customize the Accounts table to suit your needs: you can add, delete and edit accounts, groups or descriptions.
Enter Opening Balances
In the Opening column enter the opening balances of the Accounts. Negative asset account amounts are entered with a minus sign in front.
Enter the balances of the previous year
INPAS requires comparative financial information for the previous reporting period.
To enter the previous year's balances in Banana Accounting, go to the Previous view and enter the amounts in the Previous Year column. Ensure that comparative information is also included in the other required financial statements and related notes.
Enter the Transactions
Register the accounting transactions in the journal. Enter the date, the document number and the description. Enter the destination account into the Debit account column, and the account of origin in the Credit account. Then add the amount.
You can modify the journal at any time.
Manage funds, grants and donations, project and operating expenses
Under INPAS, the NPO must identify its funds and classify them as restricted or unrestricted. Each fund may relate to a specific project or another purpose.
Income, expenses, non-financial assets, long-term liabilities, and assets or liabilities linked to delivery obligations must be tracked separately for each fund. Other short-term assets and liabilities should also be tracked by fund when this can be done without excessive cost or effort.
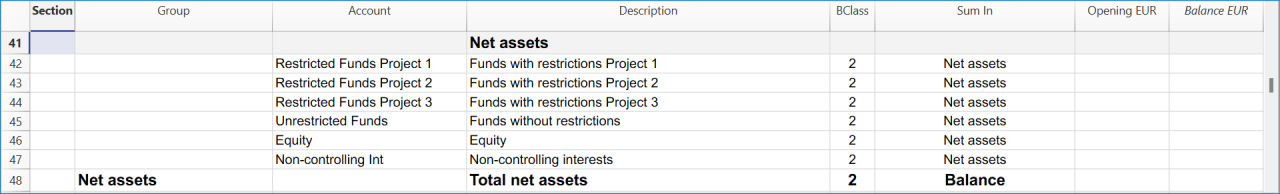
Manage grants and donations in the Income Statement.
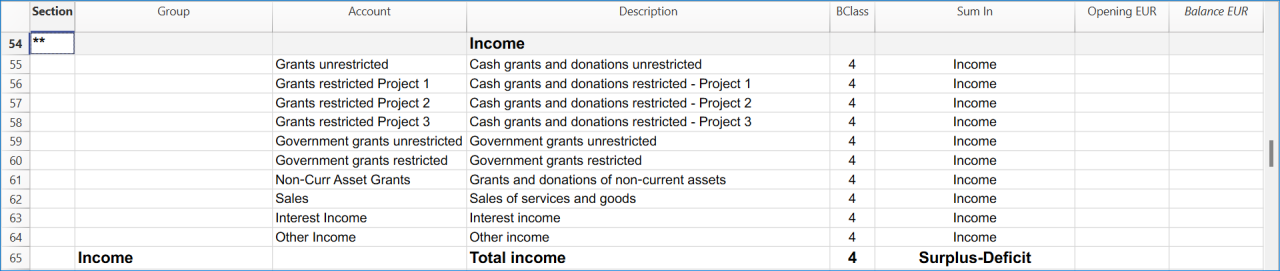
Manage projects expenses and operating expenses in the Income Statement.
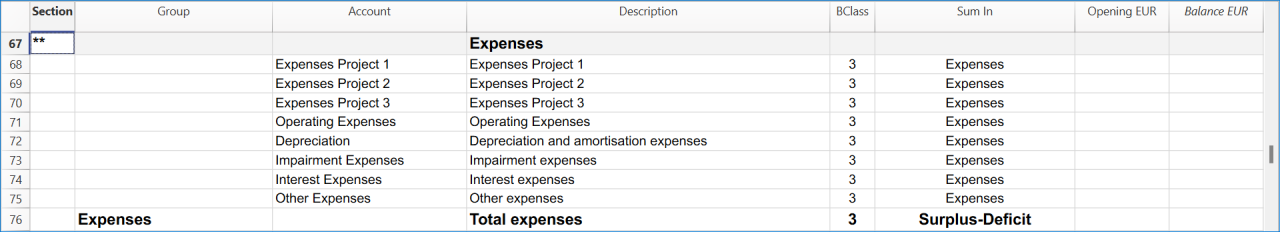
Recording transactions by fund
In this template, segments identify the fund to which each accounting amount belongs:
- :Fund A, :Fund B and :Fund C: restricted funds.
- :General: unrestricted General Fund.
For ordinary transactions, add the segment after both the Debit and Credit accounts when they belong to the same fund.
Projects are tracked separately using cost centres CC2, and donors using CC3.
The following examples show how to record donations, expenses, grant advances and transfers between funds.
Receiving a restricted donation without delivery obligations
The organisation receives EUR 727 from Benjamin Foster for Fund A and Project 1:
- Date: 2026-01-10
- Debit account: Bank:Fund A
- Credit account: Grants restricted Project 1:Fund A
- Amount: 727.00
- CC2: Project 1
- CC3: Benjamin Foster
The donation is recognised as income attributed to Fund A because it does not include a qualifying delivery obligation.
Paying project expenses
The organisation pays EUR 307 for school programme costs:
- Date: 2026-01-12
- Debit account: Expenses Project 1:Fund A
- Credit account: Bank:Fund A
- Amount: 307.00
- CC2: -Project 1
- CC3: leave empty
For these two transactions, Fund A records EUR 727 of income and EUR 307 of expenses, resulting in a surplus of EUR 420.
Receiving an advance with delivery obligations
The organisation receives EUR 3,000 in advance for Fund B. The grant agreement includes qualifying delivery obligations that have not yet been fulfilled:
- Date: 2026-02-11
- Debit account: Bank:Fund B
- Credit account: Grant oblig. liability:Fund B
- Amount: 3,000.00
- CC2: leave empty
- CC3: Olivia Reynolds
The amount is initially recognised as a liability, not as revenue.
Recognising revenue after fulfilling delivery obligations
When the first milestone is achieved, EUR 1,200 is recognised as grant revenue:
- Date: 2026-05-27
- Debit account: Grant oblig. liability:Fund B
- Credit account: Grants restricted Project 2:Fund B
- Amount: 1,200.00
- CC2: Project 2
- CC3: leave empty
The liability decreases and recognised income increases, without a new bank receipt.
Recording unrestricted income in the General Fund
The tutorial includes an unrestricted donation receipt of EUR 25,000:

- Date: 2026-01-02
- Debit account: Bank:General
- Credit account: Grants unrestricted:General
- Amount: 25,000.00
- CC2: leave empty
- CC3: Miles Thompson
The segment :General identifies the transaction as belonging to the unrestricted General Fund.
Recording transfers between funds
The tutorial includes a permitted transfer of EUR 900 from the General Fund to Fund A.
The bank allocation is recorded as:

- Date: 2026-04-18
- Debit account: Bank:Fund A
- Credit account: Bank:General
- Amount: 900.00
The corresponding movement between the fund accounts is recorded as:

- Date: 2026-04-18
- Debit account: Unrestricted Funds:General
- Credit account: Restricted Fund A:Fund A
- Amount: 900.00
These entries distinguish the change in the bank's fund attribution from the movement in fund net assets.
The transfer does not represent an external cash flow and does not create additional income or expenses for the association.
A transfer between restricted and unrestricted funds must be permitted under the applicable fund restrictions. An internal designation alone does not create a restricted fund under INPAS. A qualifying external restriction or fundraising commitment is required.
Checking and reporting fund balances
Use the reports subdivided by segment to analyse the financial information attributed to each fund. These reports display assets, liabilities, income and expenses separately for each fund.
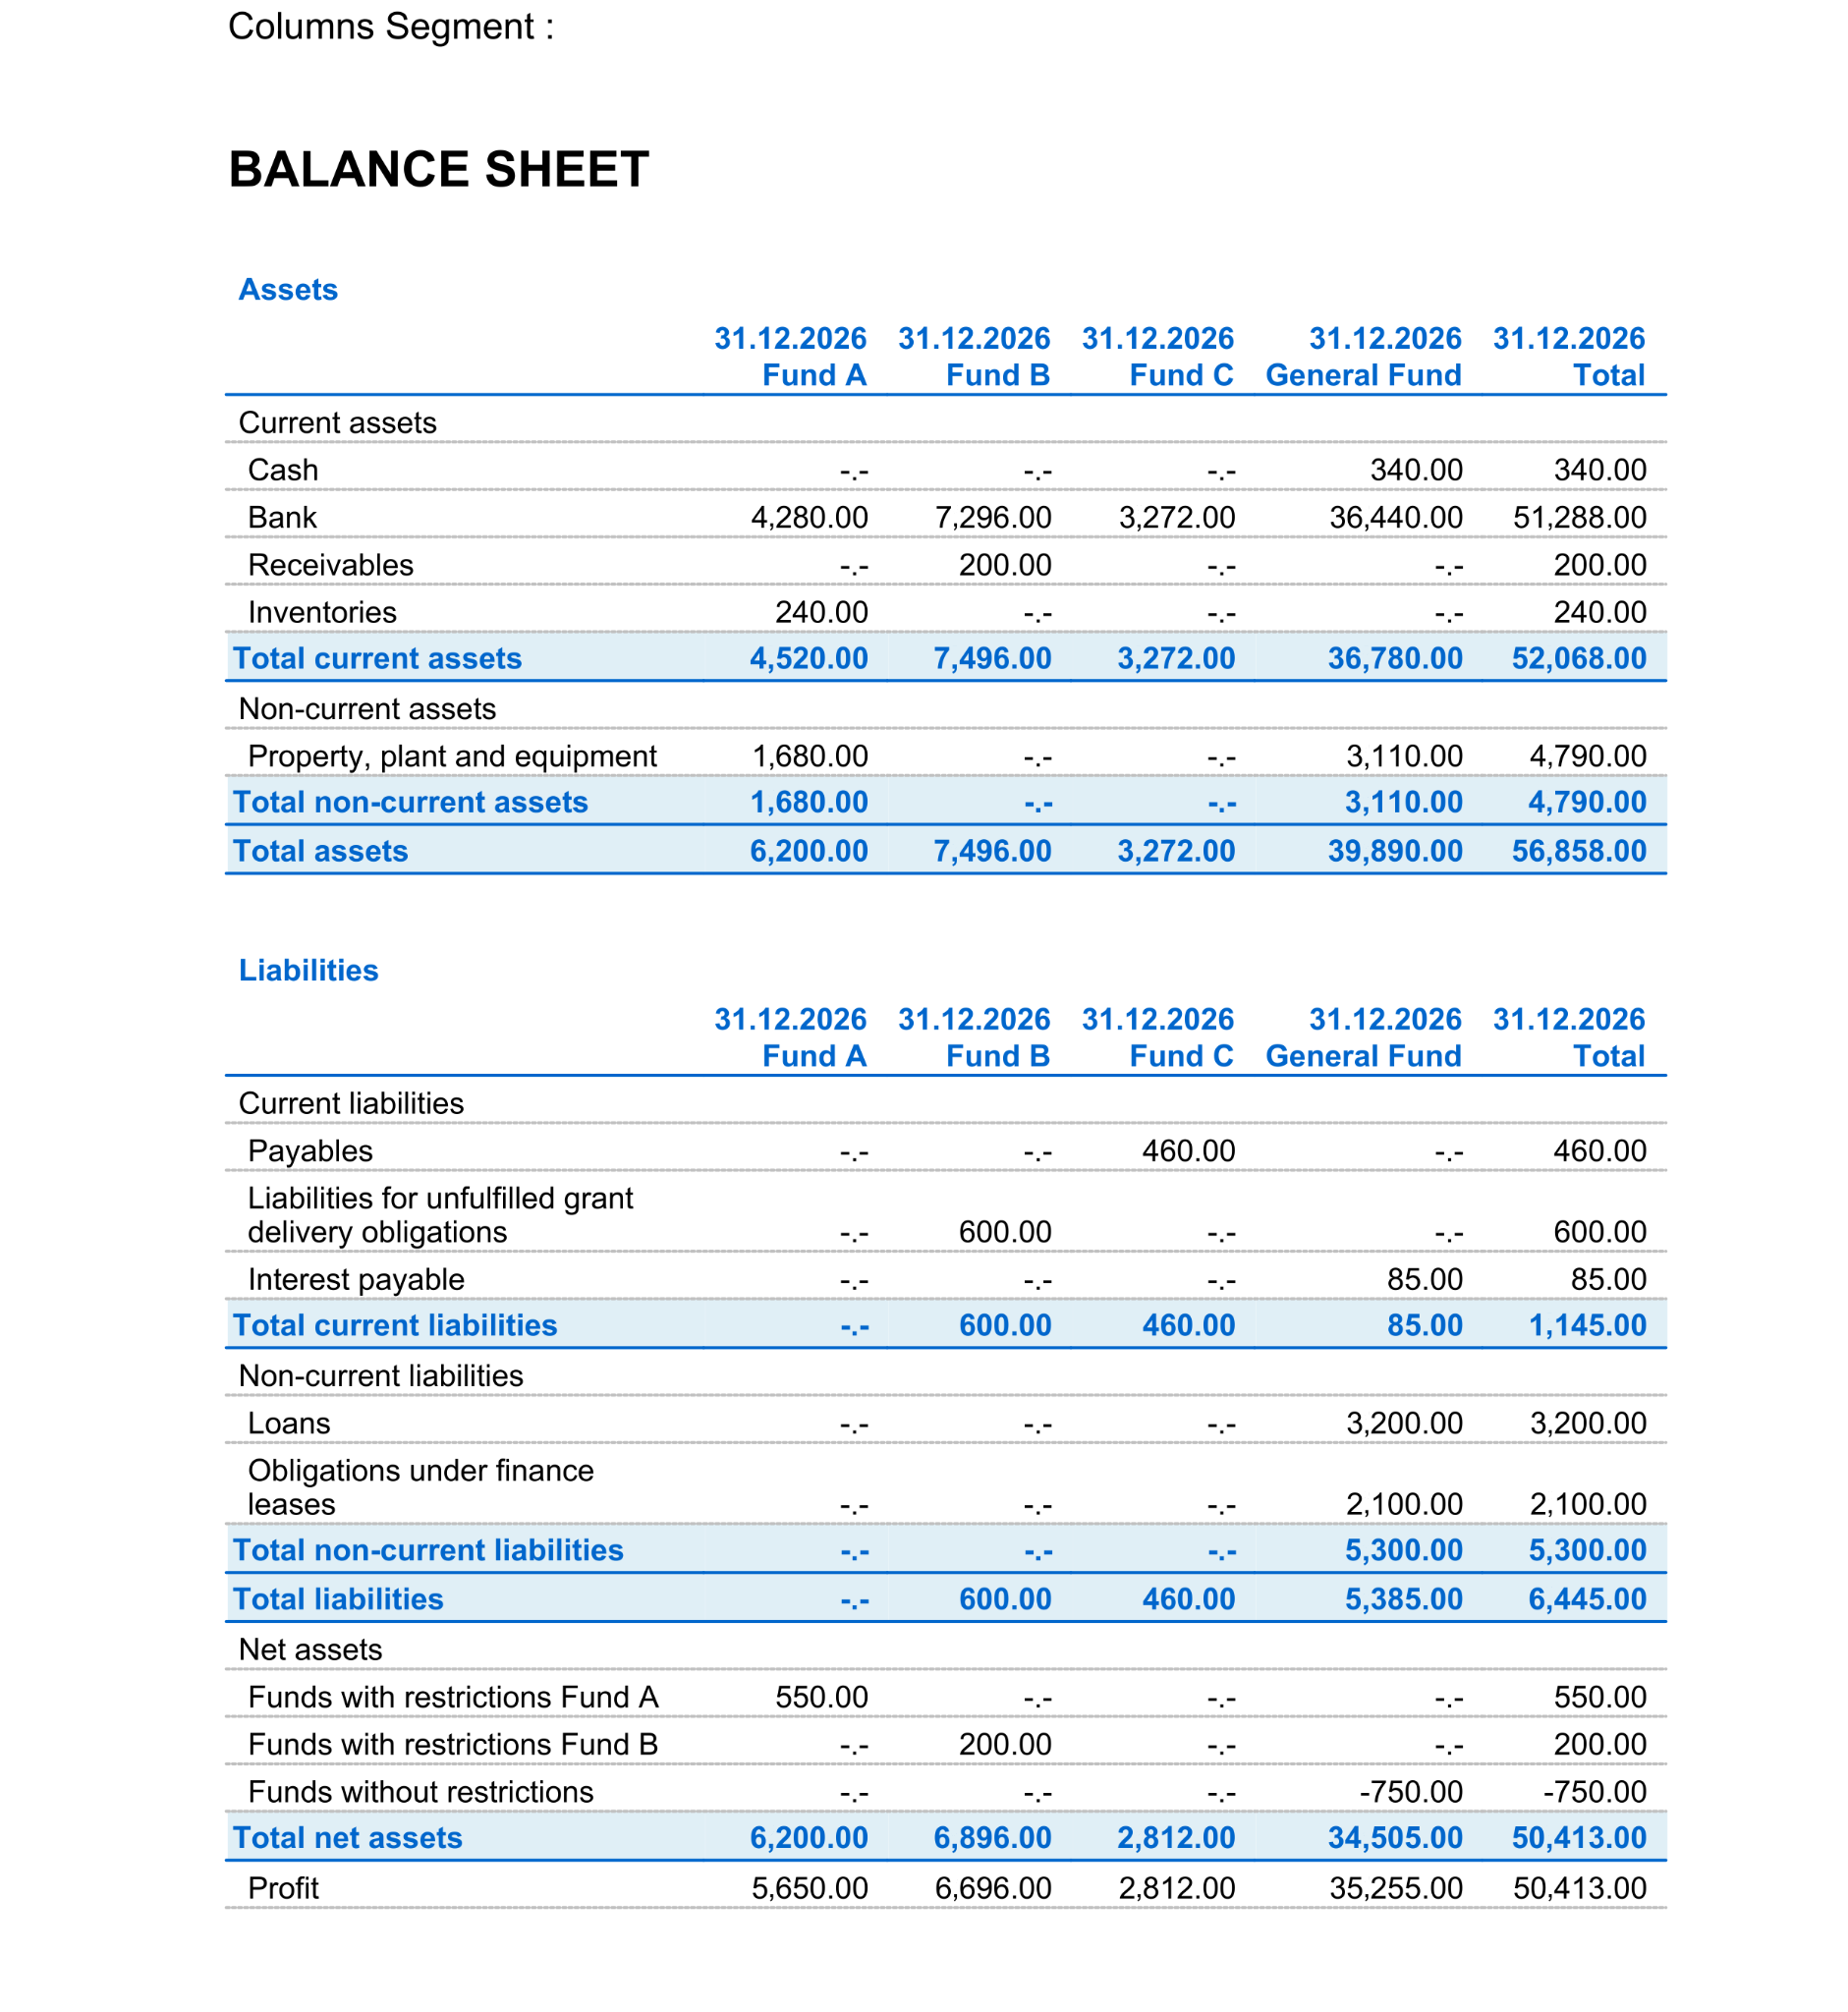
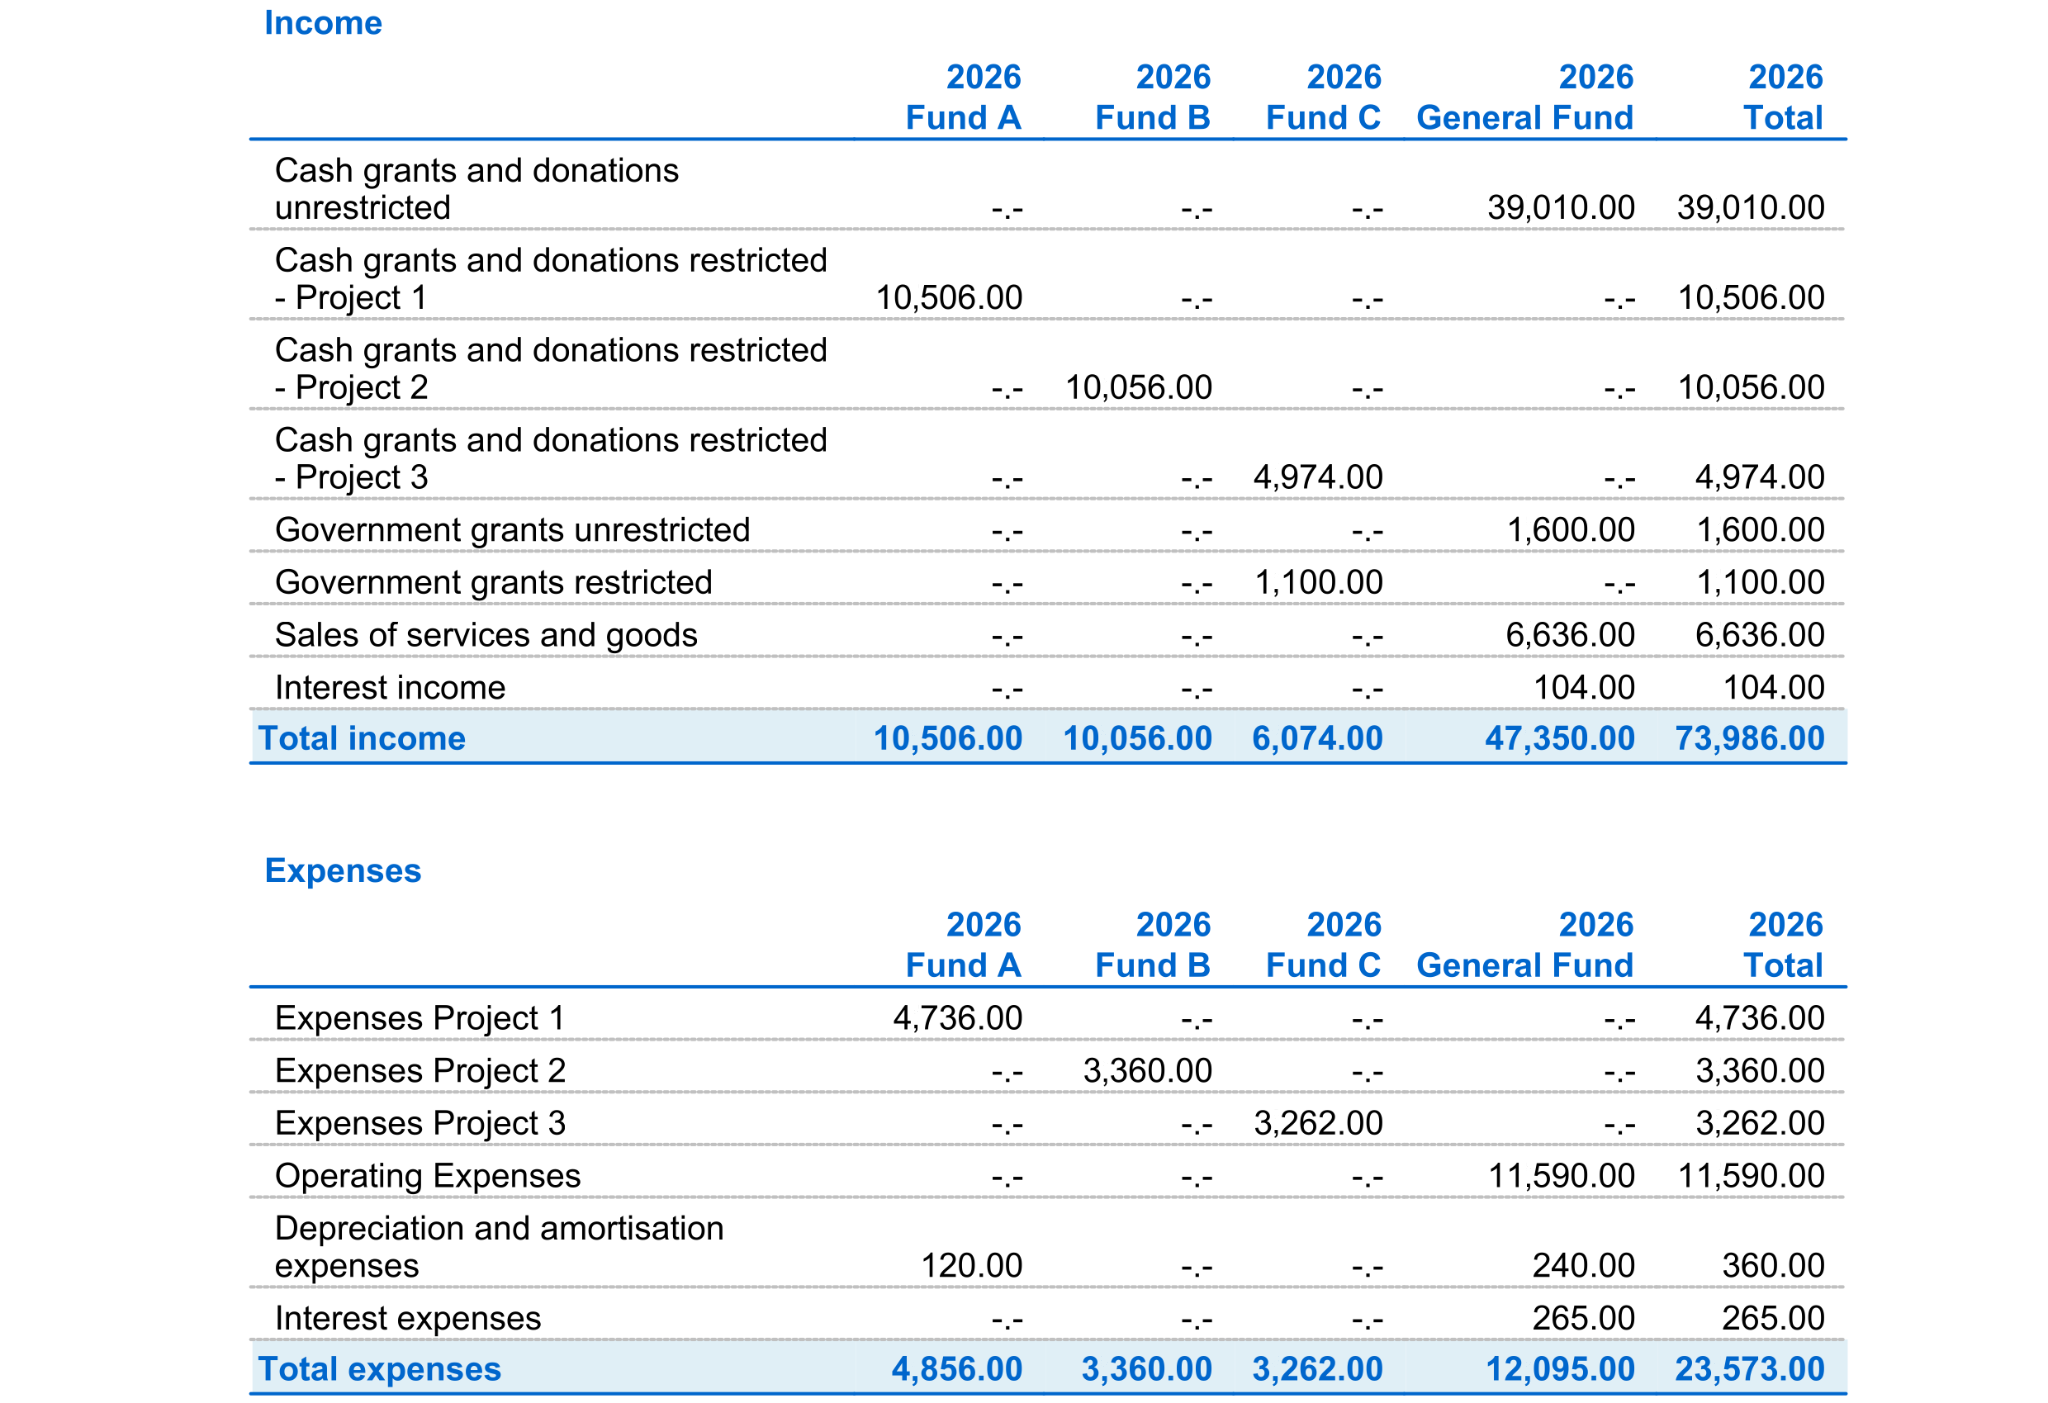
The balance displayed on an individual segment account card does not necessarily represent the fund's net asset balance: when the same segment appears on both sides of a transaction, its movements can offset each other.
All fund balances in the Statement of Financial Position must be reconciled with opening balances, income, expenses, other changes and permitted transfers. Additional fund information must be disclosed in the notes to the financial statements, as required by INPAS.
A restriction on the use of a donation does not automatically create a liability.
Get the Statement of Financial Position and the Income Statement
At any time of the year you can create your Balance sheet, which is a financial report of your assets, liabilities and equity and the Profit and Loss statement, which includes income and expenses. You will achieve optimal reports because you can always modify the data until they are perfect. You have the possibility to print out your statements or save them in PDF format.
Complete the documentation using the Excel Template
After preparing the Statement of Financial Position and the Statement of Income and Expenses in Banana Accounting, use the Excel template to complete the additional financial statements and explanatory notes.
The NPO must ensure that all applicable INPAS requirements are met before declaring compliance with the Standard.
Income & Expenses: INPAS Standard Template
En este artículo
Income & Expenses: INPAS Standard Template
Income & Expenses: INPAS Standard Template
The INPAS International standard Income & Expenses template for associations provides a comprehensive framework for organizing financial transactions and reporting for associations adhering to international standards.
Abrir en Banana WebApp
Abra Banana Contabilidad Plus en su navegador sin necesidad de instalación. Personaliza la plantilla, introduce las transacciones y guarda el archivo en tu ordenador.
Abrir plantilla en WebApp Abrir tutorial en WebAppDocumentación de la plantilla
The NPO is responsible for ensuring that its financial reports comply with all applicable INPAS requirements. Using the template alone does not guarantee compliance.
INPAS requires accrual-based financial reporting, meaning that income and expenses must be recorded in the period to which they relate, even when payments occur at a different time. For example, an expense relating to December but paid in January may need to be recorded in December. When using this Income & Expense template, additional accounting adjustments may therefore be necessary to correctly report income, expenses, assets and liabilities.
Recording transactions by fund
This template uses segments to identify restricted funds (:Fund A, :Fund B, :Fund C) and the unrestricted General Fund (:General).
For ordinary transactions, add the segment after both the Account and Category codes when they belong to the same fund.
For example, Bank:Fund A and Grants restricted Project 1:Fund A identify the bank amount and the donation income as belonging to Fund A.
Projects are tracked separately using cost centres CC2, and donors using CC3.
The following examples show how to record donations, expenses, grant advances and transfers between funds.
Receiving a restricted donation without delivery obligations
The organisation receives EUR 727 from Benjamin Foster for Fund A and Project 1:
- Date: 2026-01-10
- Income: 727.00
- Expenses: leave empty
- Account: Bank:Fund A
- Category: Grants restricted Project 1:Fund A
- CC2: Project 1
- CC3: Benjamin Foster
The donation is recognised as income attributable to Fund A.
Paying project expenses
The organisation pays EUR 307 for Project 1:
- Date: 2026-01-12
- Income: leave empty
- Expenses: 307.00
- Account: Bank:Fund A
- Category: Expenses Project 1:Fund A
- CC2: -Project 1
- CC3: leave empty
Considering these two transactions alone, the project shows a surplus of EUR 420.
Receiving an advance with delivery obligations
The organisation receives EUR 3,000 in advance for Fund B:
- Date: 2026-02-11
- Income: 3,000.00
- Expenses: leave empty
- Account: Bank:Fund B
- Category: Grant oblig. liability:Fund B
- CC2: leave empty
- CC3: Olivia Reynolds
In this example, Grant oblig. liability is a balance-sheet account defined in the Accounts table, not an income category.
Although EUR 3,000 is entered in the Income column because money is received, it is recognised as a liability, not as grant revenue.
Recognising revenue after fulfilling delivery obligations
The association recognises EUR 1,200 after completing part of its obligations:
- Date: 2026-05-27
- Income: 1,200.00
- Expenses: leave empty
- Account: Grant oblig. liability:Fund B
- Category: Grants restricted Project 2:Fund B
- CC2: Project 2
- CC3: leave empty
This is a non-cash accounting adjustment. It reduces the outstanding liability and recognises revenue without increasing the bank balance.
Recording unrestricted income in the General Fund
The tutorial includes an unrestricted donation receipt of EUR 25,000:

- Date: 2026-01-02
- Income: 25,000.00
- Expenses: leave empty
- Account: Bank:General
- Category: Grants unrestricted:General
- CC2: leave empty
- CC3: Miles Thompson
The segment :General assigns the recognised income to the unrestricted General Fund.
Recording transfers between funds
The tutorial includes a permitted reallocation of EUR 900 from the General Fund to Fund A:

- Date: 2026-04-18
- Income: 900.00
- Expenses: leave empty
- Account: Bank:Fund A
- Category: Bank:General
- CC2: leave empty
- CC3: leave empty
This transaction changes the fund attribution of an existing bank balance. It does not represent an external bank receipt, create new revenue or change the association's total cash balance.
Both Account and Category refer to balance-sheet accounts, and the segment is used on each side to identify the source and destination funds.
The association must ensure that transfers between funds are permitted by the applicable restrictions.
Checking fund movements and net assets
Use reports subdivided by segment to analyse the income, expenses and relevant assets and liabilities attributed to individual funds. Each fund can be displayed in a separate column.
The balance-sheet report provides an overview of assets and liabilities by fund. The final balance represents net assets, not necessarily the annual surplus or deficit. The organisation must ensure that net assets are correctly classified and presented in the INPAS financial statements.
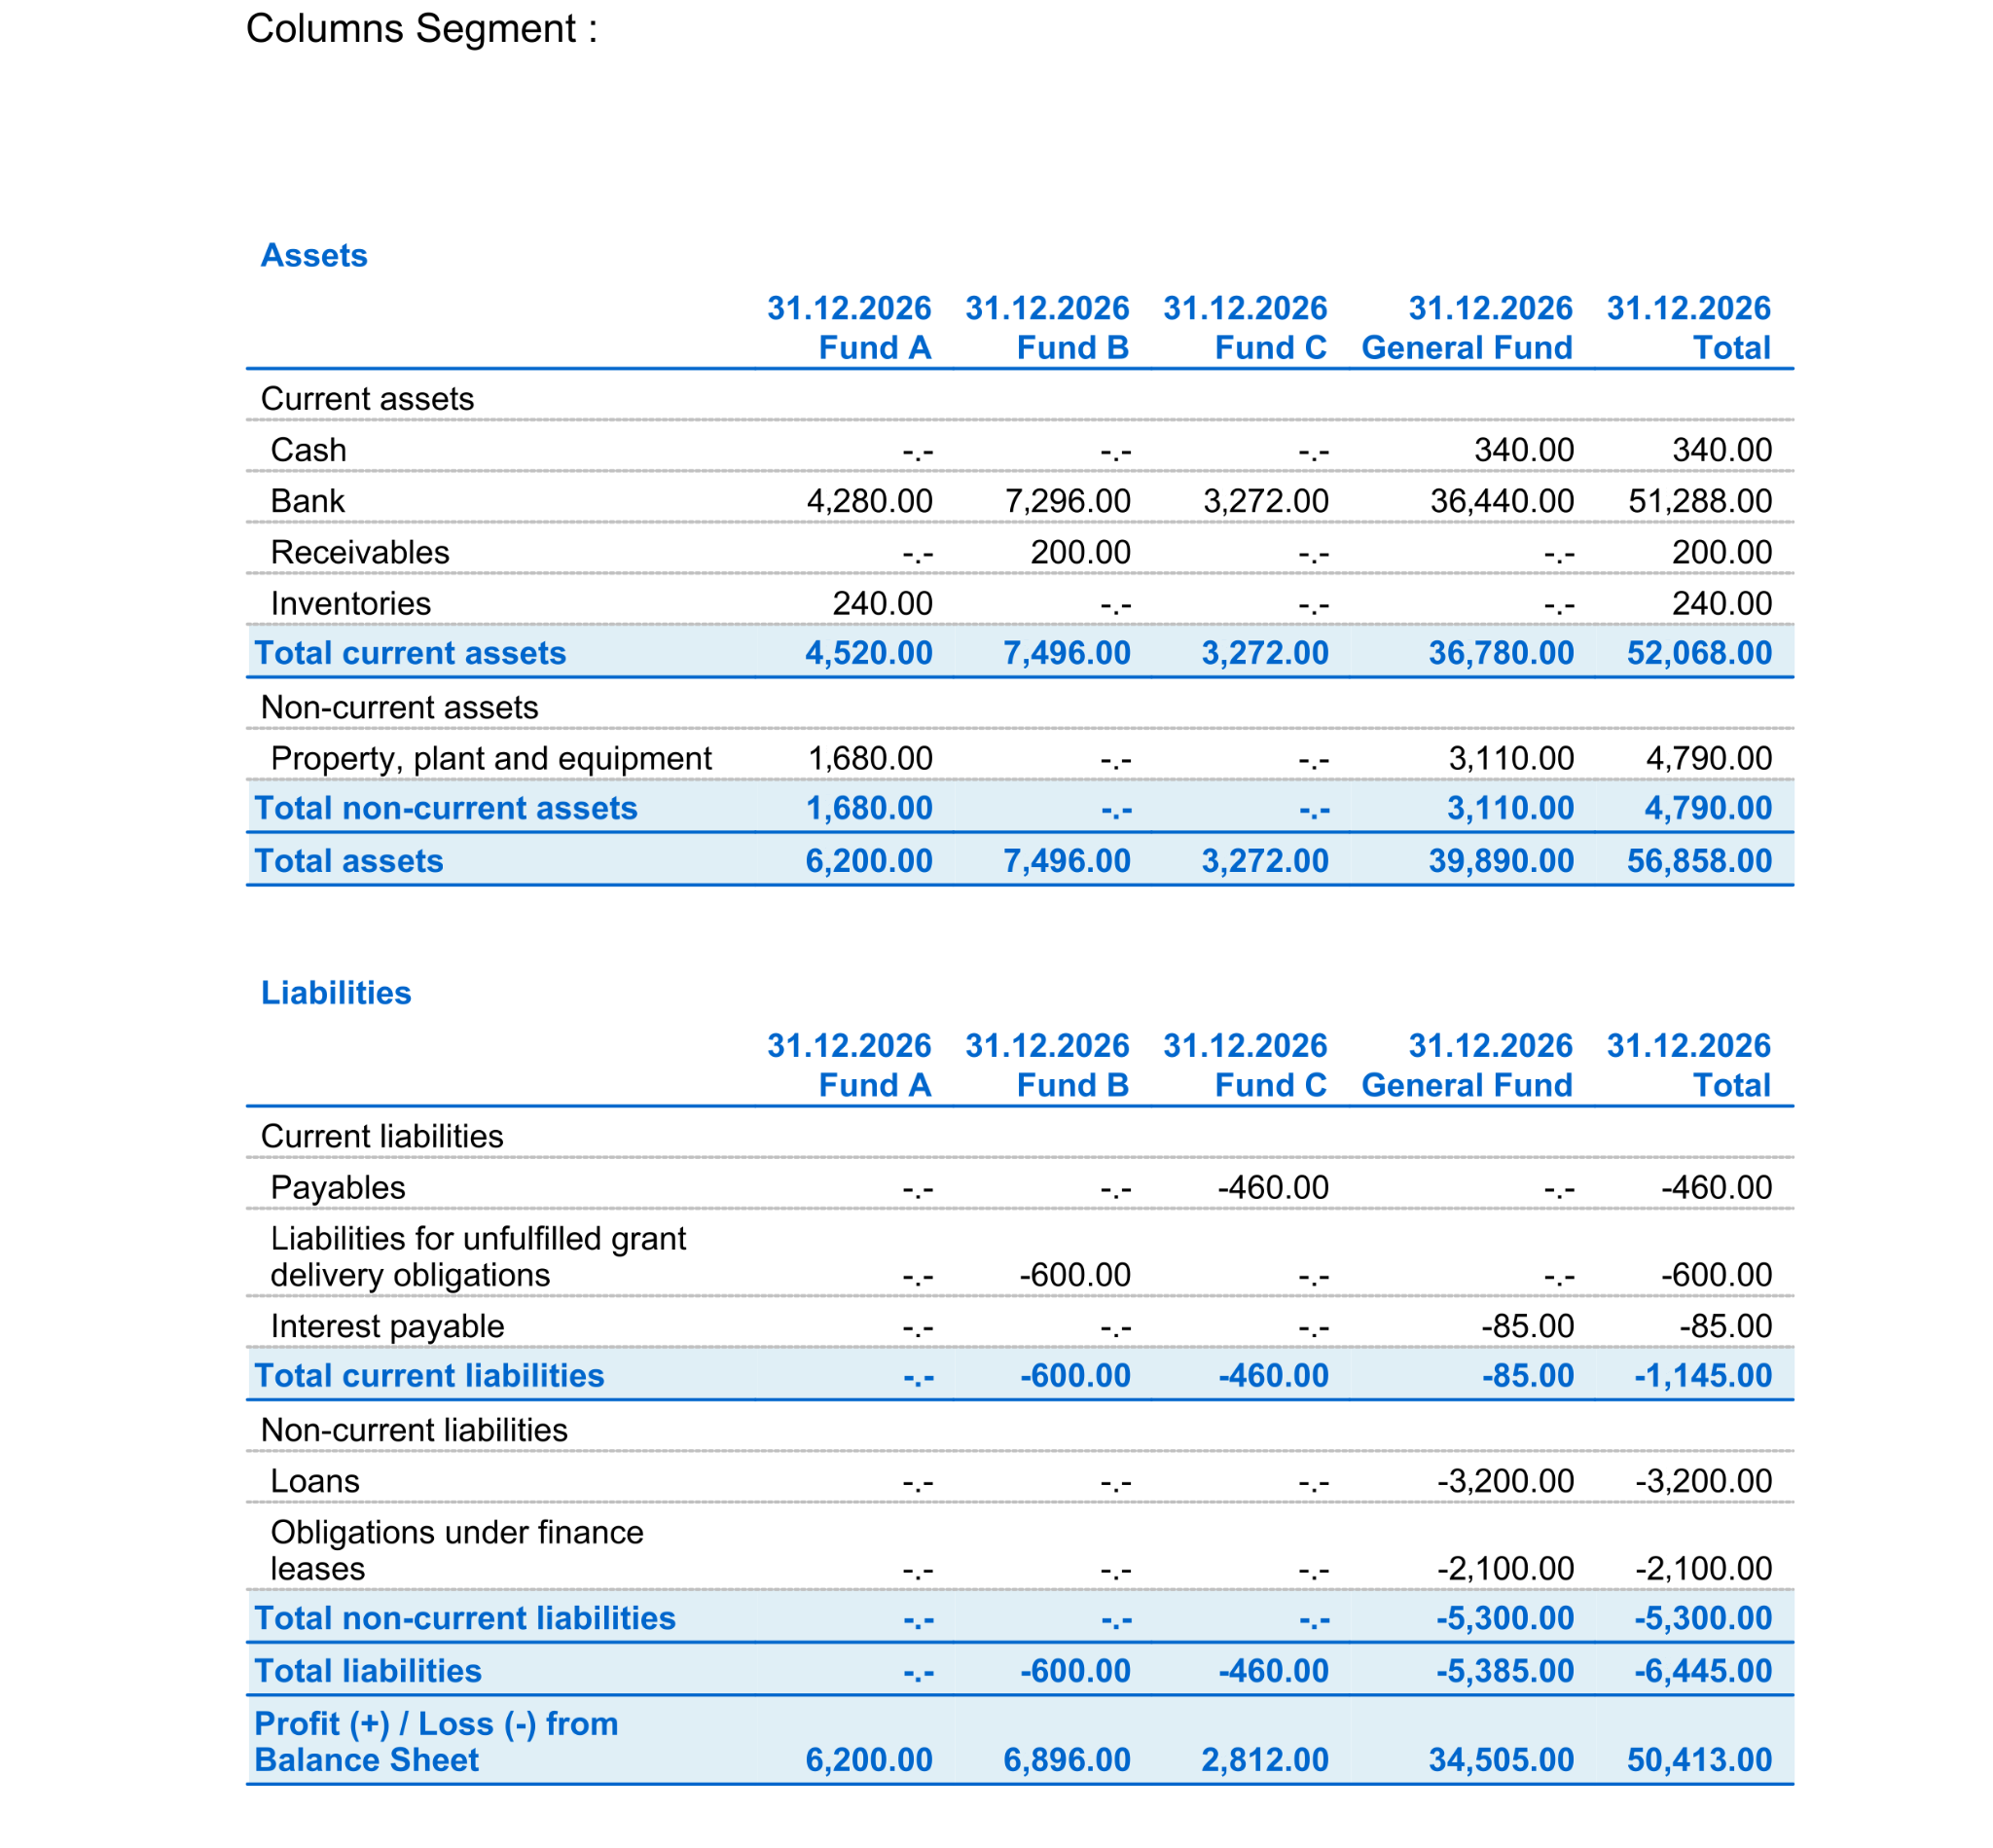
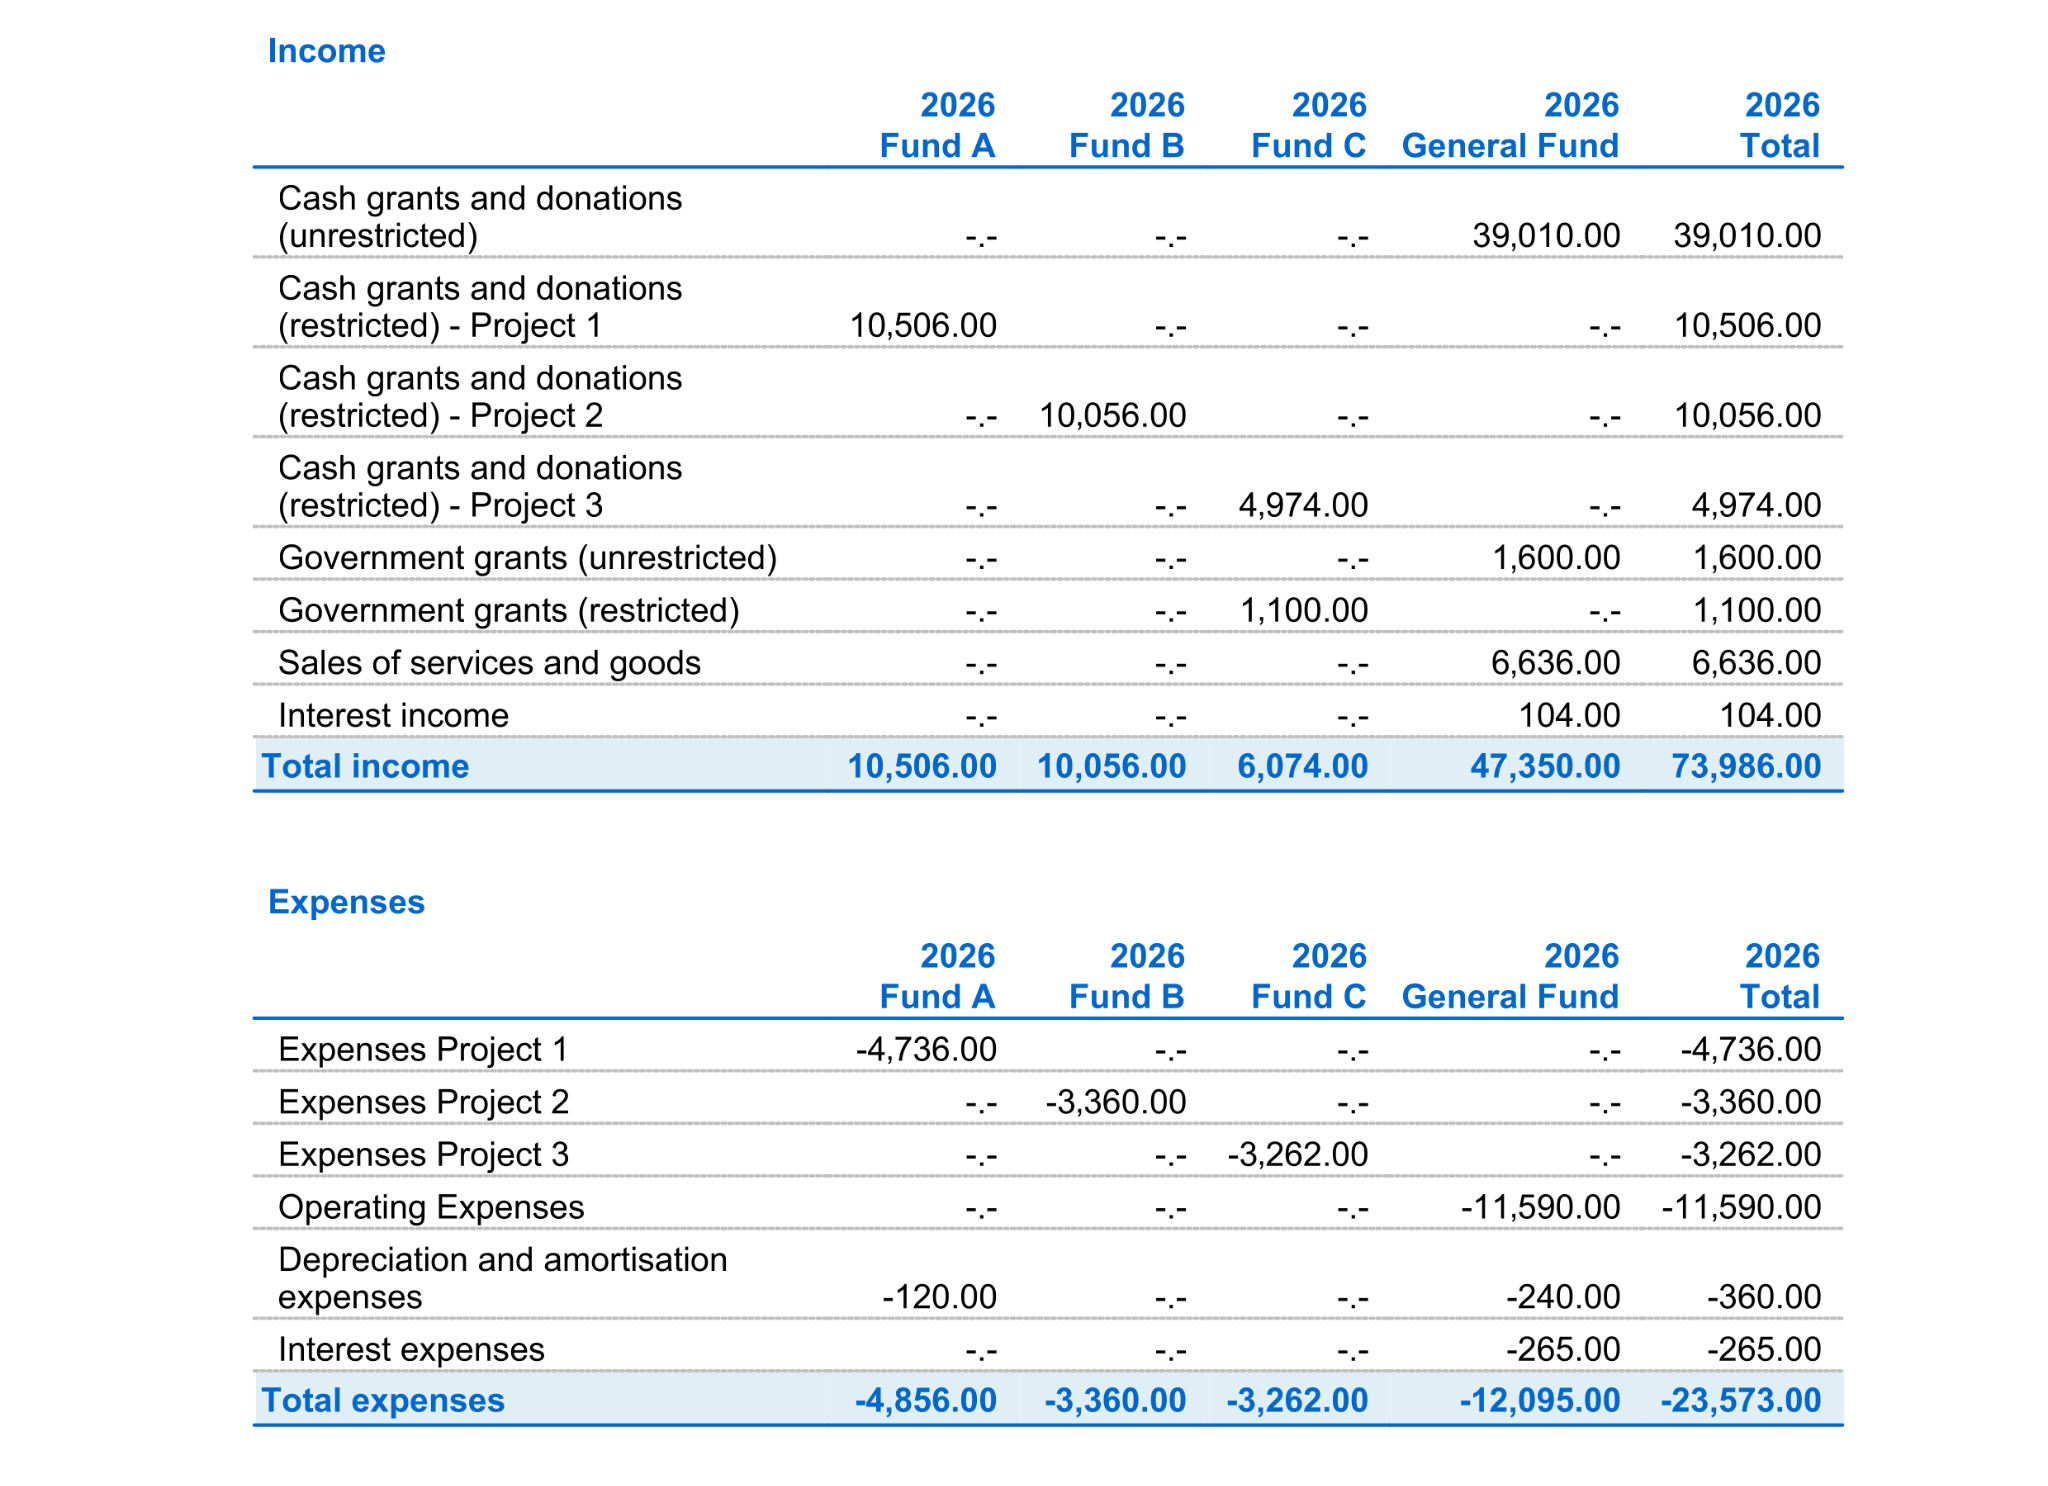
The balance shown on an individual segment card is not necessarily the fund's net asset balance. Some transactions affect liabilities instead of income, and transfers or non-cash adjustments may involve two segment-attributed positions.
For example, the EUR 3,000 advance received for Fund B is initially a liability. It does not represent a deficit in the fund's net assets.
The organisation must reconcile opening balances, recognised income, expenses, permitted transfers, other changes and closing balances for each relevant fund.
INPAS requires accrual-based financial reporting. Additional year-end adjustments may be necessary to ensure that the financial statements are complete.
Free INPAS Excel Template
En este artículo
Free INPAS Excel Template
Free INPAS Excel Template
The free INPAS Excel Template helps non-profit organisations prepare and complete their financial statements in accordance with the International Non-Profit Accounting Standard (INPAS 2025). It includes worksheets for the Statement of Financial Position, Statement of Income and Expenses, Statement of Changes in Net Assets, Statement of Cash Flows and Explanatory Notes. Used alongside Banana Accounting, it supports a simpler and more efficient reporting process. Banana manages daily accounting, tracks funds, projects and donations, and generates the Statement of Financial Position and Statement of Income and Expenses. Excel helps complete the additional financial statements, explanatory notes and comparative information required by INPAS. Together, these tools help reduce manual work, improve consistency and make financial reporting easier. Each organisation remains responsible for reviewing its completed reports to ensure that all applicable INPAS requirements, including disclosures and narrative reporting, are met.
Contabilidad libro de caja para organización sin ánimo de lucro
En este artículo
Contabilidad libro de caja para organización sin ánimo de lucro
Contabilidad libro de caja para organización sin ánimo de lucro
Inicia la gestión contable, de forma clara y transparente, de tu asociación u organización sin ánimo de lucro, Utilizando esta sencilla plantilla apta para cualquier persona, con el método de libro de caja.
Abrir en Banana WebApp
Abra Banana Contabilidad Plus en su navegador sin necesidad de instalación. Personaliza la plantilla, introduce las transacciones y guarda el archivo en tu ordenador.
Abrir plantilla en WebAppTemplate preview
Asociación XX
Contabilidad 2022
Moneda base: USD
Cash Manager
| Grupo | Cuenta | Descripción | Sumar en |
|---|---|---|---|
| 1000 | Efectivo | ||
| Grupo | Categoría | Descripción | Sumar en |
|---|---|---|---|
| RESULTADO OPERATIVO | |||
| INGRESOS | |||
| 4000 | Ventas varias | 4 | |
| 4010 | Pagos de membresía | 4 | |
| 4020 | Donaciones | 4 | |
| 4030 | Otros | 4 | |
| 4 | TOTAL INGRESOS | 00 | |
| GASTOS | |||
| 3000 | Gastos para Proyecto A | 3 | |
| 3005 | Gastos para Proyecto B | 3 | |
| 3010 | Gastos para Proyecto C | 3 | |
| 3025 | Papelería, equipos, limpieza, etc. | 3 | |
| 3030 | Coste postal | 3 | |
| 3035 | Alquiler, electricidad, agua | 3 | |
| 3040 | Teléfono y fax | 3 | |
| 3050 | Publicidad, folletos, imprenta | 3 | |
| 3055 | Reembolso a voluntarios | 3 | |
| 3060 | Tasas y otras licencias | 3 | |
| 3065 | Gastos imprevistos | 3 | |
| 3070 | Gastos menores no registrados | 3 | |
| 3075 | Otros | 3 | |
| 3 | TOTAL GASTOS | 00 | |
| 00 | RESULTADO | ||
| CENTROS DE COSTES Y BENEFICIOS | |||
| Listado de miembros | |||
| ;MA | Montgomery Alexander | TM | |
| ;WB | Weelt Bob | TM | |
| ;JB | Johnson Bill | TM | |
| ;SA | Smith Ada | TM | |
| ;MC | Montgomery Chloe | TM | |
| TM | Total miembros | ||
Contabilidad ingresos y gastos para organización sin ánimo de lucro
En este artículo
Contabilidad ingresos y gastos para organización sin ánimo de lucro
Contabilidad ingresos y gastos para organización sin ánimo de lucro
Inicia la gestión contable, de forma clara y transparente, de tu asociación u organización sin ánimo de lucro. Utilizando esta sencilla plantilla apta para cualquier persona, con el método de ingresos y gastos.
Abrir en Banana WebApp
Abra Banana Contabilidad Plus en su navegador sin necesidad de instalación. Personaliza la plantilla, introduce las transacciones y guarda el archivo en tu ordenador.
Abrir plantilla en WebAppTemplate preview
Asociación XX
Contabilidad 2022
Moneda base: USD
Contabilidad de ingresos y egresos
| Grupo | Cuenta | Descripción | Sumar en |
|---|---|---|---|
| PATRIMONIO | |||
| 1000 | Efectivo | 1 | |
| 1010 | Cuenta Corriente postal | 1 | |
| 1020 | Cuenta Corriente bancaria | 1 | |
| 1100 | Clientes | 1 | |
| 1150 | Impuestos anticipados | 1 | |
| 1300 | Activos transitorios | 1 | |
| 1400 | Mobiliario de oficina | 1 | |
| 1500 | Hardware/Software | 1 | |
| 2000 | Proveedores | 1 | |
| 2050 | IVA Automático | 1 | |
| 2060 | IVA Autoridades fiscales | 1 | |
| 2100 | Préstamo bancario c/c | 1 | |
| 2400 | Préstamo bancario a largo plazo | 1 | |
| 2700 | Pasivos transitorios | 1 | |
| 1 | TOTAL | ||
| CENTROS DE COSTES Y BENEFICIOS | |||
| Listado de miembros | |||
| ;MA | Montgomery Alexander | TM | |
| ;WB | Weelt Bob | TM | |
| ;JB | Johnson Bill | TM | |
| ;SA | Smith Ada | TM | |
| ;MC | Montgomery Chloe | TM | |
| TM | Total miembros |
| Grupo | Categoría | Descripción | Sumar en |
|---|---|---|---|
| RESULTADO OPERATIVO | |||
| INGRESOS | |||
| 4200 | Ventas varias | 4 | |
| 4400 | Pagos de membresía | 4 | |
| 4500 | Donaciones | 4 | |
| 4 | TOTAL INGRESOS | 00 | |
| GASTOS | |||
| 3000 | Gastos para Proyecto A | 3 | |
| 3001 | Gastos para Proyecto B | 3 | |
| 3002 | Gastos para Proyecto C | 3 | |
| 3005 | Bienes adquiridos para reventa | 3 | |
| 3010 | Alquiler, electricidad, agua | 3 | |
| 3020 | Impuestos | 3 | |
| 3050 | Seguros | 3 | |
| 3070 | Honorarios | 3 | |
| 3080 | Limpieza | 3 | |
| 3090 | Material de oficina | 3 | |
| 3100 | Teléfono | 3 | |
| 3110 | Coste postal | 3 | |
| 3130 | Imprenta y publicidad | 3 | |
| 3140 | Intereses negativos bancarios | 3 | |
| 3150 | Comisiones Banco y cuentas corrientes | 3 | |
| 3160 | Depreciación mobiliario | 3 | |
| 3170 | Otros | 3 | |
| 3 | TOTAL GASTOS | 00 | |
| 00 | RESULTADO | ||
Contabilidad partida doble para organización sin ánimo de lucro
En este artículo
Contabilidad partida doble para organización sin ánimo de lucro
Contabilidad partida doble para organización sin ánimo de lucro
Inicia la gestión contable, de forma clara y transparente, de tu organización o asociación sin ánimo de lucro. Utilizando esta sencilla plantilla apta para cualquier persona, y con el método de partida doble.
Abrir en Banana WebApp
Abra Banana Contabilidad Plus en su navegador sin necesidad de instalación. Personaliza la plantilla, introduce las transacciones y guarda el archivo en tu ordenador.
Abrir plantilla en WebAppTemplate preview
Asociación XX
Contabilidad 2022
Moneda base: USD
Partida doble
| Grupo | Cuenta | Descripción | Sumar en | Gr1 |
|---|---|---|---|---|
| BALANCE GENERAL | ||||
| ACTIVOS | ||||
| 1000 | Efectivo | 1 | ||
| 1010 | Cuenta Corriente postal | 1 | ||
| 1020 | Cuenta Corriente bancaria | 1 | ||
| 1100 | Clientes | 1 | ||
| 1150 | Impuestos anticipados | 1 | ||
| 1300 | Activos transitorios | 1 | ||
| 1400 | Mobiliario de oficina | 1 | ||
| 1500 | Hardware/Software | 1 | ||
| 1 | TOTAL ACTIVOS | 00 | 1 | |
| PASIVOS | ||||
| 2000 | Proveedores | 2 | ||
| 2100 | Préstamo bancario c/c | 2 | ||
| 2400 | Préstamo bancario a largo plazo | 2 | ||
| 2700 | Pasivos transitorios | 2 | ||
| 2800 | Capital inicial | 2 | ||
| 2900 | Beneficios o pérdidas acumuladas | 2 | ||
| 299 | Ganancia o pérdida del año en curso | 2 | 1 | |
| 2 | TOTAL PASIVOS | 00 | 1 | |
| 1 | ||||
| CUENTA DE RESULTADOS | ||||
| INGRESOS | ||||
| 4200 | Ventas varias | 4 | ||
| 4400 | Cuotas de membresía | 4 | ||
| 4500 | Donaciones | 4 | ||
| 4 | TOTAL INGRESOS | 02 | ||
| GASTOS | ||||
| 3000 | Gastos para Proyecto A | 3 | ||
| 3001 | Gastos para Proyecto B | 3 | ||
| 3002 | Gastos para Proyecto C | 3 | ||
| 3005 | Bienes adquiridos para reventa | 3 | ||
| 3010 | Alquiler, electrícidad, agua | 3 | ||
| 3020 | Impuestos | 3 | ||
| 3050 | Seguros | 3 | ||
| 3070 | Honorarios | 3 | ||
| 3080 | Limpieza | 3 | ||
| 3090 | Material de oficina | 3 | ||
| 3100 | Teléfono | 3 | ||
| 3110 | Coste postal | 3 | ||
| 3130 | Imprenta y publicidad | 3 | ||
| 3140 | Intereses negativos bancarios | 3 | ||
| 3150 | Comisiones banco y cuentas corrientes | 3 | ||
| 3160 | Depreciación mobiliario | 3 | ||
| 3170 | Otros gastos | 3 | ||
| 3 | TOTAL GASTOS | 02 | 1 | |
| 02 | Beneficio(-) Pérdida(+) de la cuenta de resultados | 299 | 1 | |
| 00 | La diferencia debe ser = 0 (nulo) | |||
| CENTROS DE COSTES Y BENEFICIOS | ||||
| Listado de miembros | ||||
| ;MA | Montgomery Alexander | TM | 1 | |
| ;WB | Weelt Bob | TM | ||
| ;JB | Johnson Bill | TM | ||
| ;SA | Smith Ada | TM | ||
| ;MC | Montgomery Chloe | TM | ||
| TM | Total miembros |
Contabilidad multidivisa para organización sin ánimo de lucro
En este artículo
Contabilidad multidivisa para organización sin ánimo de lucro
Contabilidad multidivisa para organización sin ánimo de lucro
Inicia la gestión contable, de forma clara y transparente, de tu organización o asociación sin ánimo de lucro. Utilizando esta sencilla plantilla apta para cualquier persona, incluso con contabiildad multidivisa.
Abrir en Banana WebApp
Abra Banana Contabilidad Plus en su navegador sin necesidad de instalación. Personaliza la plantilla, introduce las transacciones y guarda el archivo en tu ordenador.
Abrir plantilla en WebAppTemplate preview
Asociación XX
Contabilidad 2022
Moneda base: USD
Partida doble con multi-moneda
| Grupo | Cuenta | Descripción | Moneda | Sumar en | Gr1 |
|---|---|---|---|---|---|
| BALANCE GENERAL | |||||
| ACTIVOS | |||||
| 1000 | Efectivo | USD | 1 | ||
| 1010 | Cuenta Corriente postal | USD | 1 | ||
| 1020 | Cuenta Corriente bancaria | USD | 1 | ||
| 1025 | Banco CHF | CHF | 1 | ||
| 1100 | Clientes | USD | 1 | ||
| 1150 | Impuestos anticipados | USD | 1 | ||
| 1300 | Activos transitorios | USD | 1 | ||
| 1400 | Mobiliario de oficina | USD | 1 | ||
| 1500 | Hardware/Software | USD | 1 | ||
| 1 | TOTAL ACTIVOS | 00 | 1 | ||
| PASIVOS | |||||
| 2000 | Proveedores | USD | 2 | ||
| 2100 | Préstamo bancario c/c | USD | 2 | ||
| 2400 | Préstamo bancario a largo plazo | USD | 2 | ||
| 2700 | Pasivos transitorios | USD | 2 | ||
| 2800 | Capital inicial | USD | 2 | ||
| 2900 | Beneficios o pérdidas acumuladas | USD | 2 | ||
| 290 | Ganancia o pérdida del año en curso | 2 | 1 | ||
| 2 | TOTAL PASIVOS | 00 | 1 | ||
| 1 | |||||
| CUENTA DE RESULTADOS | |||||
| INGRESOS | |||||
| 4200 | Ventas varias | USD | 4 | ||
| 4400 | Cuotas de membresía | USD | 4 | ||
| 4500 | Donaciones | USD | 4 | ||
| 4600 | Diferencias de tipo de cambio | USD | 4 | ||
| 4 | TOTAL INGRESOS | 02 | |||
| GASTOS | |||||
| 3000 | Gastos para Proyecto A | USD | 3 | ||
| 3001 | Gastos para Proyecto B | USD | 3 | ||
| 3002 | Gastos para Proyecto C | USD | 3 | ||
| 3005 | Bienes adquiridos para reventa | USD | 3 | ||
| 3010 | Alquiler, electricidad, agua | USD | 3 | ||
| 3020 | Impuestos | USD | 3 | ||
| 3050 | Seguros | USD | 3 | ||
| 3070 | Honorarios | USD | 3 | ||
| 3080 | Limpieza | USD | 3 | ||
| 3090 | Material de oficina | USD | 3 | ||
| 3100 | Teléfono | USD | 3 | ||
| 3110 | Coste postal | USD | 3 | ||
| 3130 | Imprenta y publicidad | USD | 3 | ||
| 3140 | Intereses negativos bancarios | USD | 3 | ||
| 3150 | Comisiones Banco y cuentas corrientes | USD | 3 | ||
| 3160 | Depreciación mobiliario | USD | 3 | ||
| 3170 | Otros gastos | USD | 3 | ||
| 3 | TOTAL GASTOS | 02 | 1 | ||
| 02 | Beneficio(-) Pérdida(+) de la cuenta de resultados | 290 | 1 | ||
| 00 | La diferencia debe ser = 0 (nulo) | ||||
| CENTROS DE COSTES Y BENEFICIOS | |||||
| Listado de miembros | |||||
| ;MA | Montgomery Alexander | USD | TM | 1 | |
| ;WB | Weelt Bob | USD | TM | ||
| ;JB | Johnson Bill | USD | TM | ||
| ;SA | Smith Ada | USD | TM | ||
| ;MC | Montgomery Chloe | USD | TM | ||
| TM | Total miembros |
| Referencia Moneda | Moneda | Texto |
|---|---|---|
| USD | EUR | Euro |
| USD | CHF | Francos Suizos |