In this article
Income & Expenses: INPAS Standard Template
The INPAS International standard Income & Expenses template for associations provides a comprehensive framework for organizing financial transactions and reporting for associations adhering to international standards.
Open in Banana WebApp
Run Banana Accounting Plus on your browser without any installation. Customize the template, enter the transactions and save the file on your computer.
Open template in WebApp Open tutorial in WebAppTemplate documentation
The NPO is responsible for ensuring that its financial reports comply with all applicable INPAS requirements. Using the template alone does not guarantee compliance.
INPAS requires accrual-based financial reporting, meaning that income and expenses must be recorded in the period to which they relate, even when payments occur at a different time. For example, an expense relating to December but paid in January may need to be recorded in December. When using this Income & Expense template, additional accounting adjustments may therefore be necessary to correctly report income, expenses, assets and liabilities.
Recording transactions by fund
This template uses segments to identify restricted funds (:Fund A, :Fund B, :Fund C) and the unrestricted General Fund (:General).
For ordinary transactions, add the segment after both the Account and Category codes when they belong to the same fund.
For example, Bank:Fund A and Grants restricted Project 1:Fund A identify the bank amount and the donation income as belonging to Fund A.
Projects are tracked separately using cost centres CC2, and donors using CC3.
The following examples show how to record donations, expenses, grant advances and transfers between funds.
Receiving a restricted donation without delivery obligations
The organisation receives EUR 727 from Benjamin Foster for Fund A and Project 1:

- Date: 2026-01-10
- Income: 727.00
- Expenses: leave empty
- Account: Bank:Fund A
- Category: Grants restricted Project 1:Fund A
- CC2: Project 1
- CC3: Benjamin Foster
The donation is recognised as income attributable to Fund A.
Paying project expenses
The organisation pays EUR 307 for Project 1:

- Date: 2026-01-12
- Income: leave empty
- Expenses: 307.00
- Account: Bank:Fund A
- Category: Expenses Project 1:Fund A
- CC2: -Project 1
- CC3: leave empty
Considering these two transactions alone, the project shows a surplus of EUR 420.
Receiving an advance with delivery obligations
The organisation receives EUR 3,000 in advance for Fund B:

- Date: 2026-02-11
- Income: 3,000.00
- Expenses: leave empty
- Account: Bank:Fund B
- Category: Grant oblig. liability:Fund B
- CC2: leave empty
- CC3: Olivia Reynolds
In this example, Grant oblig. liability is a balance-sheet account defined in the Accounts table, not an income category.
Although EUR 3,000 is entered in the Income column because money is received, it is recognised as a liability, not as grant revenue.
Recognising revenue after fulfilling delivery obligations
The association recognises EUR 1,200 after completing part of its obligations:

- Date: 2026-05-27
- Income: 1,200.00
- Expenses: leave empty
- Account: Grant oblig. liability:Fund B
- Category: Grants restricted Project 2:Fund B
- CC2: Project 2
- CC3: leave empty
This is a non-cash accounting adjustment. It reduces the outstanding liability and recognises revenue without increasing the bank balance.
Recording unrestricted income in the General Fund
The tutorial includes an unrestricted donation receipt of EUR 25,000:

- Date: 2026-01-02
- Income: 25,000.00
- Expenses: leave empty
- Account: Bank:General
- Category: Grants unrestricted:General
- CC2: leave empty
- CC3: Miles Thompson
The segment :General assigns the recognised income to the unrestricted General Fund.
Recording transfers between funds
The tutorial includes a permitted reallocation of EUR 900 from the General Fund to Fund A:

- Date: 2026-04-18
- Income: 900.00
- Expenses: leave empty
- Account: Bank:Fund A
- Category: Bank:General
- CC2: leave empty
- CC3: leave empty
This transaction changes the fund attribution of an existing bank balance. It does not represent an external bank receipt, create new revenue or change the association's total cash balance.
Both Account and Category refer to balance-sheet accounts, and the segment is used on each side to identify the source and destination funds.
The association must ensure that transfers between funds are permitted by the applicable restrictions.
Checking fund movements and net assets
Use reports subdivided by segment to analyse the income, expenses and relevant assets and liabilities attributed to individual funds. Each fund can be displayed in a separate column.
The balance-sheet report provides an overview of assets and liabilities by fund. The final balance represents net assets, not necessarily the annual surplus or deficit. The organisation must ensure that net assets are correctly classified and presented in the INPAS financial statements.
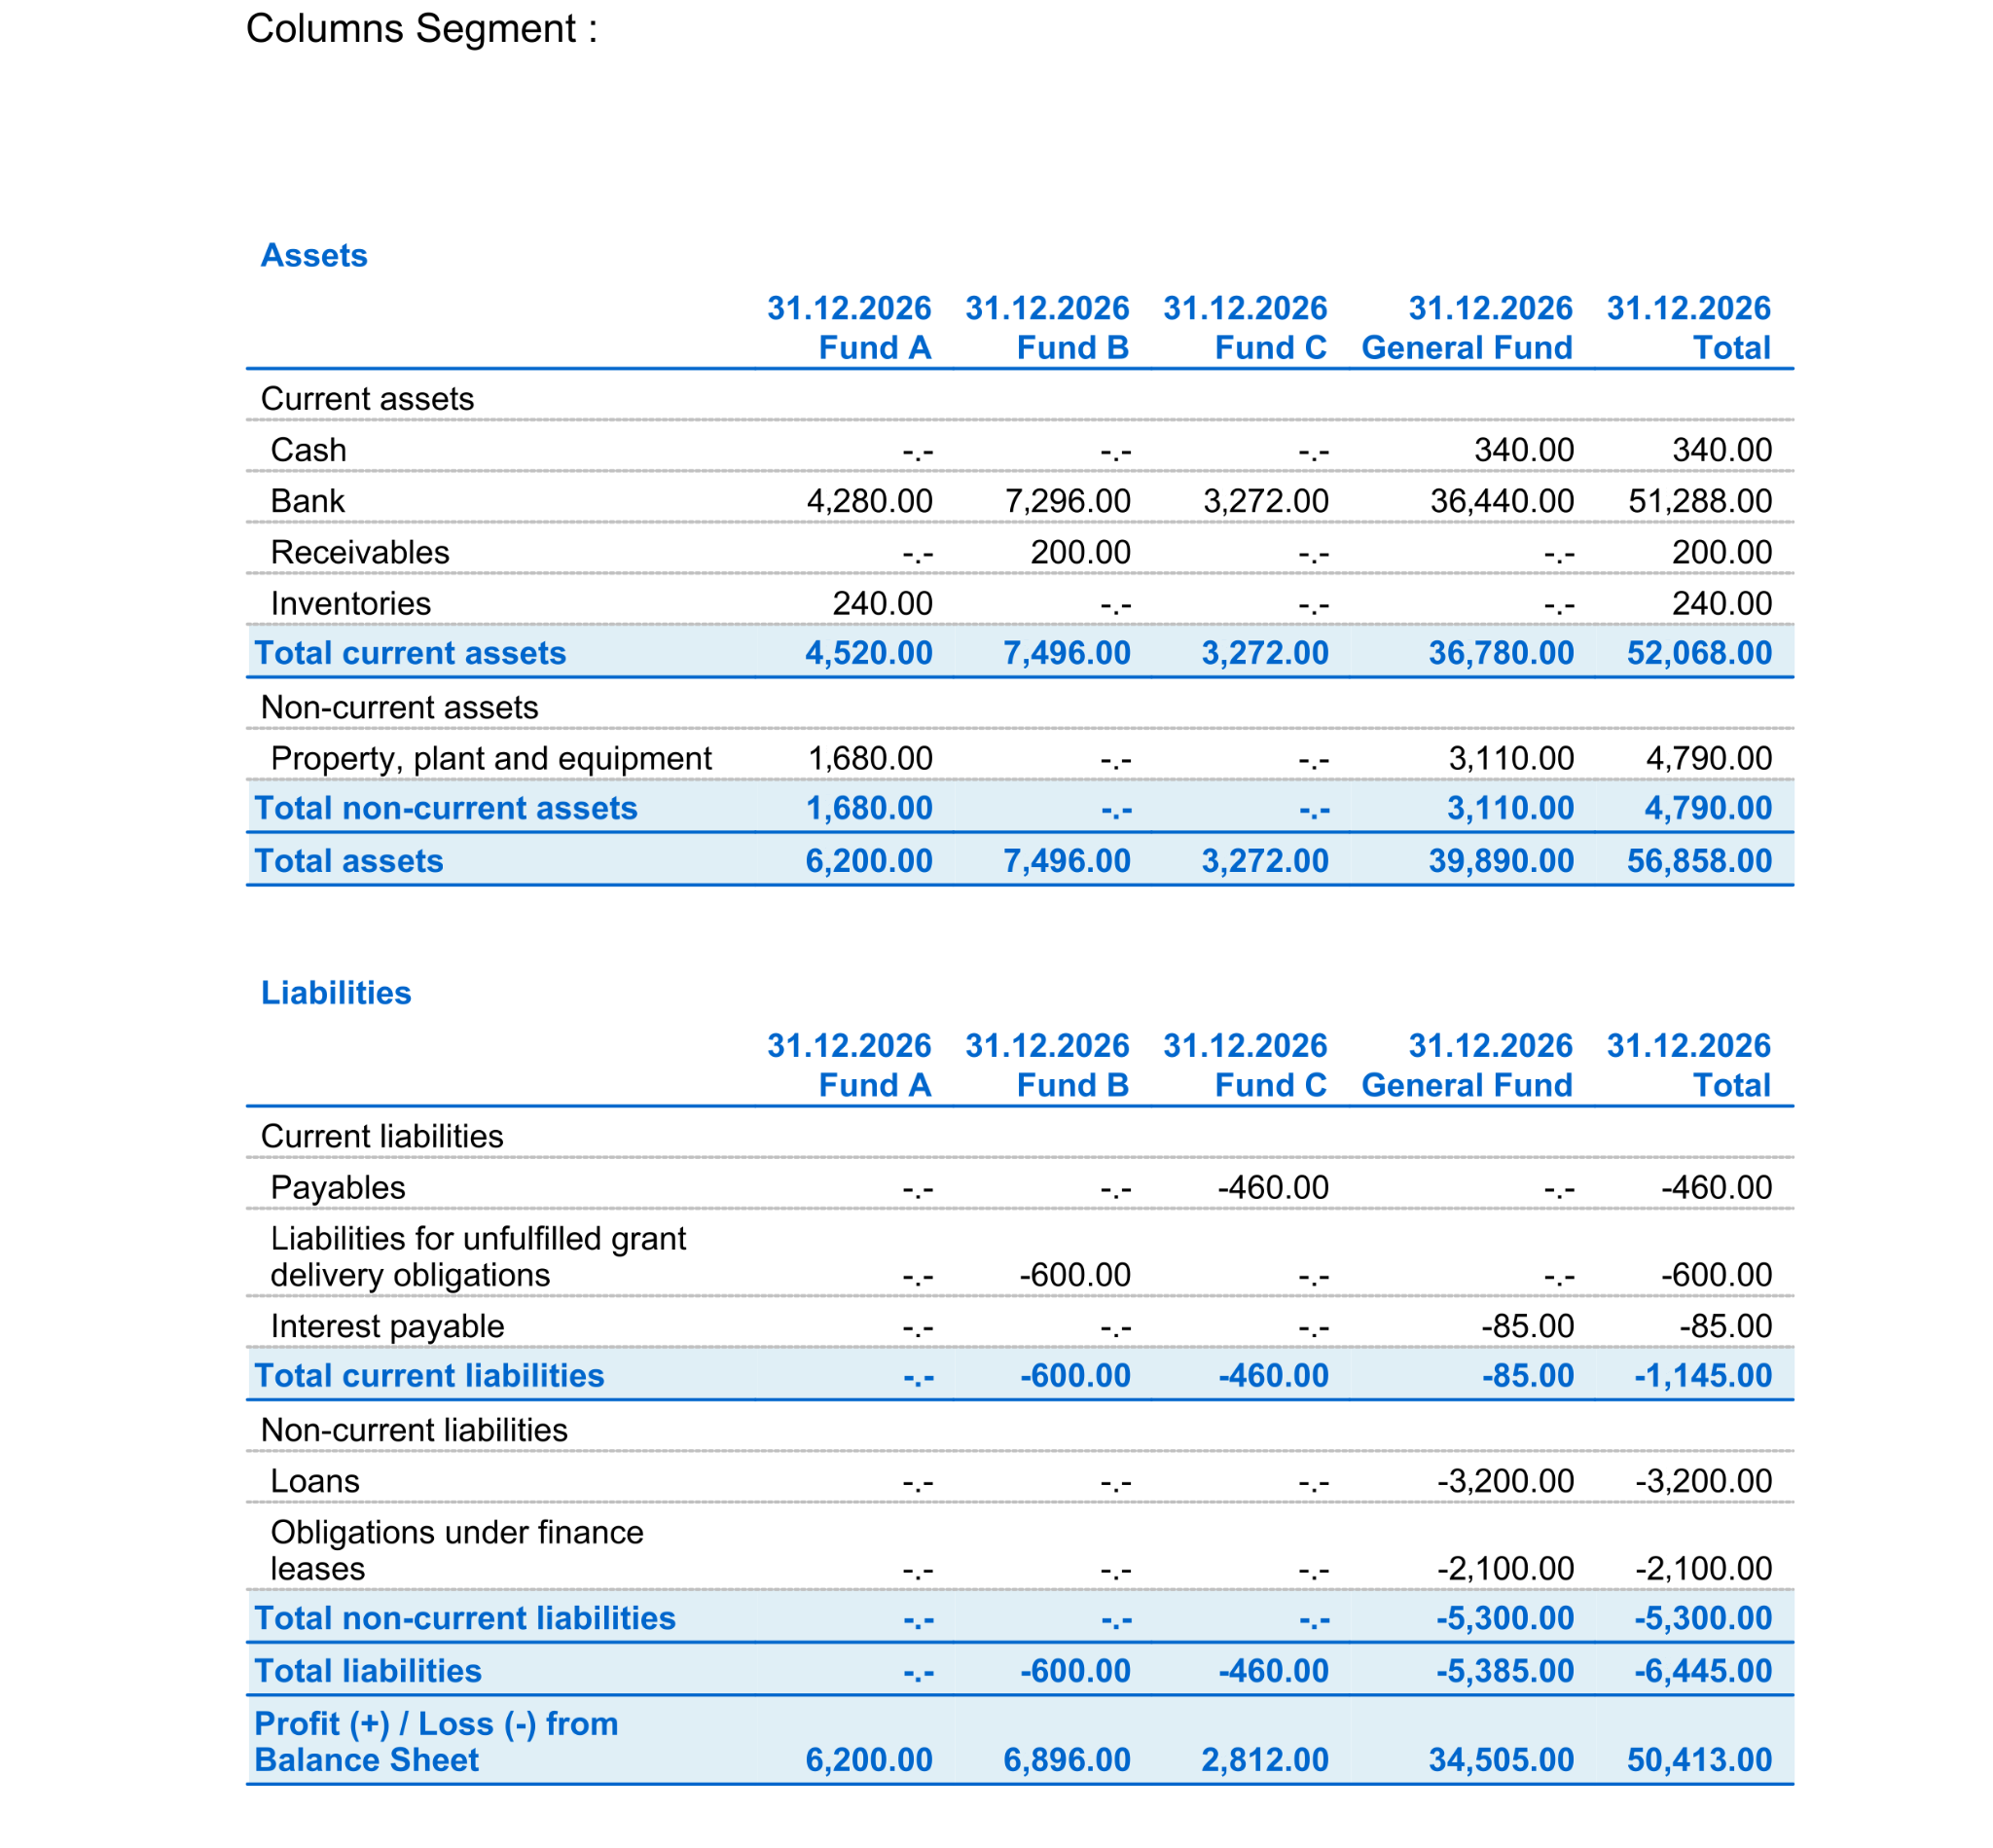
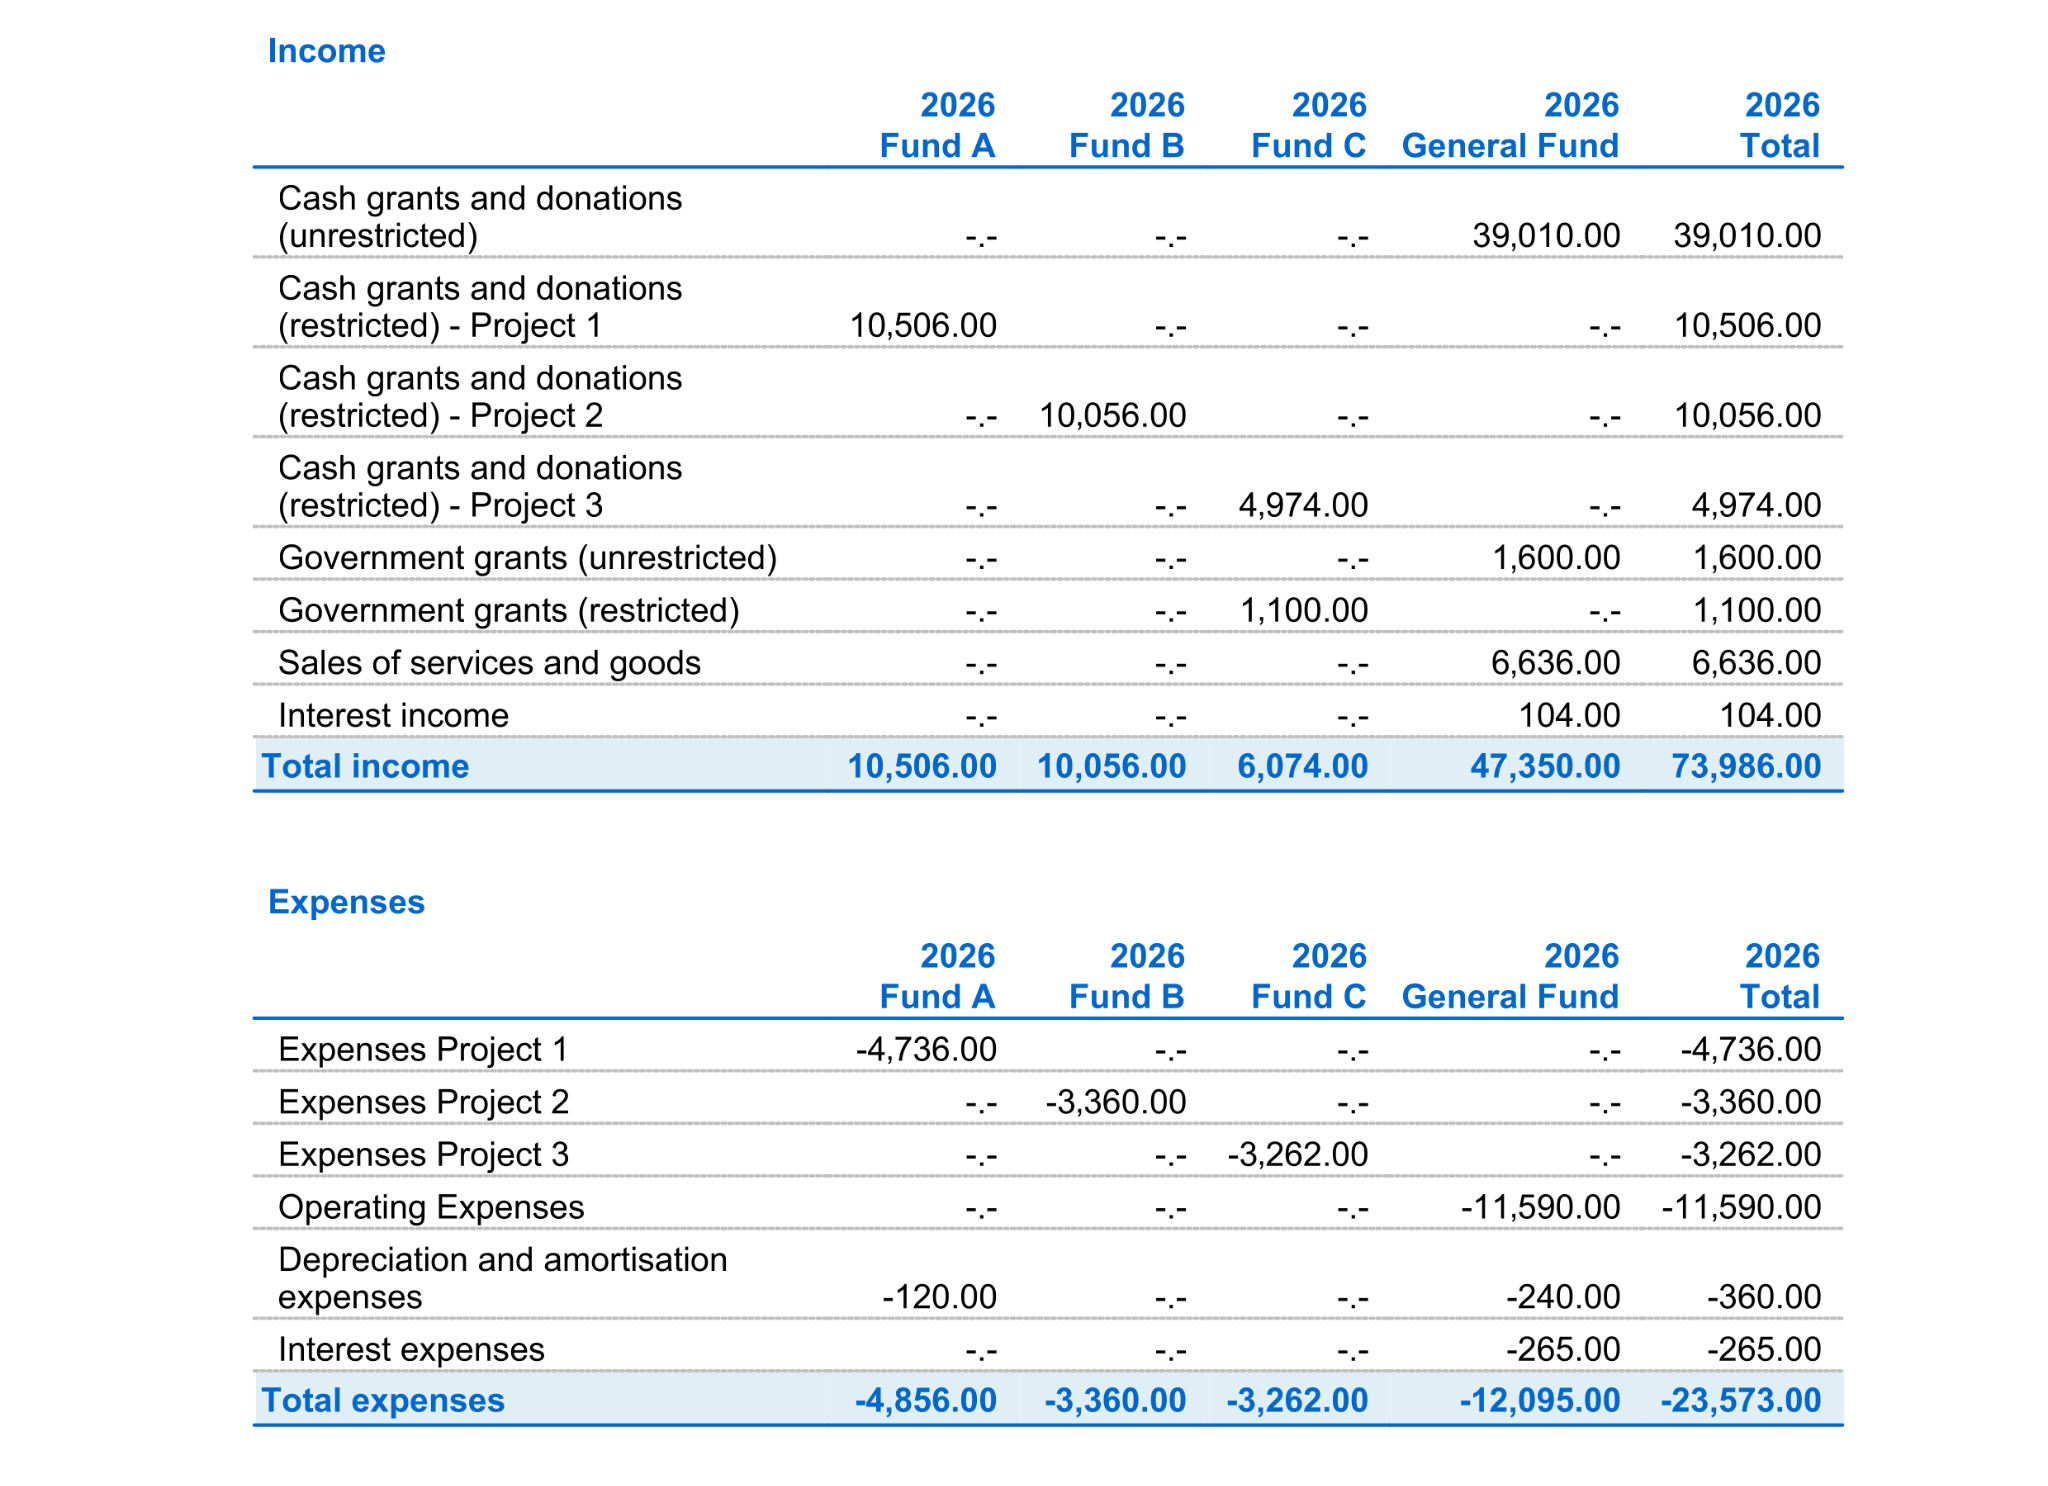
The balance shown on an individual segment card is not necessarily the fund's net asset balance. Some transactions affect liabilities instead of income, and transfers or non-cash adjustments may involve two segment-attributed positions.
For example, the EUR 3,000 advance received for Fund B is initially a liability. It does not represent a deficit in the fund's net assets.
The organisation must reconcile opening balances, recognised income, expenses, permitted transfers, other changes and closing balances for each relevant fund.
INPAS requires accrual-based financial reporting. Additional year-end adjustments may be necessary to ensure that the financial statements are complete.