Modelos Universal Noprofit
INPAS Standard Templates
[This page is currently being updated]
INPAS key accounting documents
This page introduces Banana Accounting+ and Excel templates designed to support financial reporting under the International Non-Profit Accounting Standard (INPAS). The templates help prepare the required financial statements, but full compliance also depends on applying all relevant accounting and disclosure requirements.
The NPO is responsible for ensuring that its financial reports comply with all applicable INPAS requirements. Using the template alone does not guarantee compliance.
Statement of Financial Position
The balance sheet is an essential document that provides a detailed view of your organization's financial health, clearly showing assets, liabilities and net worth. Because of the flexibility of the INPAS standard, you can present the financial statements either vertically or horizontally, tailoring them to the specific needs of your nonprofit.
This document can be generated easily using Banana Accounting+ template.
Statement of Income and Expenses
This document shows your organization's income and expenses during a period. Proper management of the income statement is crucial to demonstrate how resources were used to achieve missionary goals.
This document can be generated easily using Banana Accounting+ template.
Statement of Changes in Net Assets
This document is critical to understanding the changes that have occurred in net assets during the fiscal year. The INPAS standard provides a sequence of elements that transparently reflects the changes, making clear the impact of financial activities on the organization's assets.
Statement of Cash Flows
The cash flow statement, which shows cash flows, is essential for monitoring your organization's liquidity and ability to fund its activities. With our INPAS template, you can present this information in a clear and accessible way, improving transparency to donors and board members.
Explanatory notes
Explanatory notes are a mandatory part of INPAS financial statements. They include the basis of preparation, material accounting policies, information about individual funds and their movements, relevant grants and donations, delivery obligations where applicable, and other disclosures required by INPAS.
The notes must also include relevant comparative information for the previous reporting period.
Comparative information and Narrative reporting
INPAS requires comparative financial information for the previous reporting period.
Full INPAS compliance also requires a narrative report describing the NPO's mission, activities, performance and principal risks. The narrative report can be prepared separately, for example in Word, but must be included as part of the NPO's general purpose financial report to declare full INPAS compliance.
During the first two years following transition to INPAS, an NPO may declare compliance with the financial statement requirements only, subject to the transitional provisions.
References
- International Financial Reporting For Non Profit Organisations: https://www.inprf.org
International Non-Profit Accounting Guidance - INPAS Standard Template
En este artículo
International Non-Profit Accounting Guidance - INPAS Standard Template
International Non-Profit Accounting Guidance - INPAS Standard Template
The INPAS International standard template for associations provides a comprehensive framework for organizing financial transactions and reporting for associations adhering to international standards.
Abrir en Banana WebApp
Abra Banana Contabilidad Plus en su navegador sin necesidad de instalación. Personaliza la plantilla, introduce las transacciones y guarda el archivo en tu ordenador.
Abrir plantilla en WebAppDocumentación de la plantilla
[This page is currently being updated]
The INPAS International template for associations provides a comprehensive framework for organizing financial transactions and reporting for associations adhering to international standards.
This chart of accounts template is designed to streamline accounting processes, ensure consistency in financial reporting and facilitate compliance with regulatory requirements. With a user-friendly format and customizable accounts name, associations can efficiently track income, expenses, assets and liabilities, enabling clear and transparent financial management. Whether managing donations, membership dues or program expenditures, this template offers flexibility and adaptability to suit the unique needs of diverse associations while promoting transparency and accountability in financial operations.
The NPO is responsible for ensuring that its financial reports comply with all applicable INPAS requirements. Using the template alone does not guarantee compliance.
Banana Accounting+ provides the accounting information needed to prepare the Statement of Financial Position and the Statement of Income and Expenses.
The Excel template supports the preparation of the remaining financial statements and explanatory notes. The narrative report can be prepared separately, for example in Word, but must be included as part of the NPO's general purpose financial report to declare full INPAS compliance.
Create your file
- Create a new file, starting from this template (Template ID +11255), using one of the methods explained.
- With the command File → File properties, set the period, the association name and the basic currency.
- With the command File → Save as, save the file. Enter the association name and year in the file name.
For example "no-profit-2024.ac2".
See also Organize accounting files locally, online or in the cloud
Customize the Accounts table
Once you have entered the transactions, you can check the Accounts table. You will have an overview of your assets, liabilities, income and expenses, which allows you to keep your balance under control.
Customize the Accounts table to suit your needs: you can add, delete and edit accounts, groups or descriptions.
Enter Opening Balances
In the Opening column enter the opening balances of the Accounts. Negative asset account amounts are entered with a minus sign in front.
Enter the balances of the previous year
INPAS requires comparative financial information for the previous reporting period.
To enter the previous year's balances in Banana Accounting+, go to the Previous view and enter the amounts in the Previous Year column. Ensure that comparative information is also included in the other required financial statements and related notes.
Enter the Transactions
Register the accounting transactions in the journal. Enter the date, the document number and the description. Enter the destination account into the Debit account column, and the account of origin in the Credit account. Then add the amount.
You can modify the journal at any time.
Manage funds, grants and donations, project and operating expenses
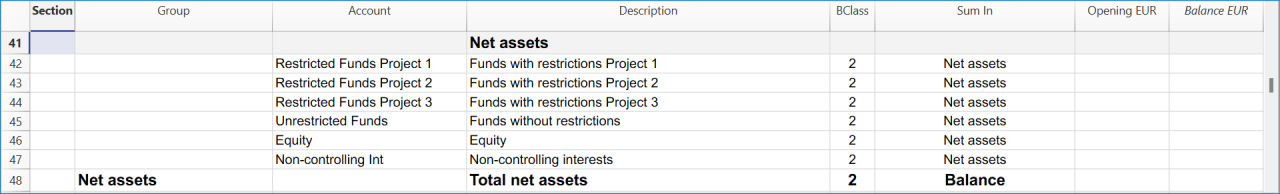
Under INPAS, the NPO must identify its funds and classify them as restricted or unrestricted. Each fund may relate to a specific project or another purpose.
Income, expenses, non-financial assets, non-current liabilities and assets or liabilities relating to delivery obligations must be tracked by fund. Other current assets and liabilities must also be tracked where available without undue cost or effort.
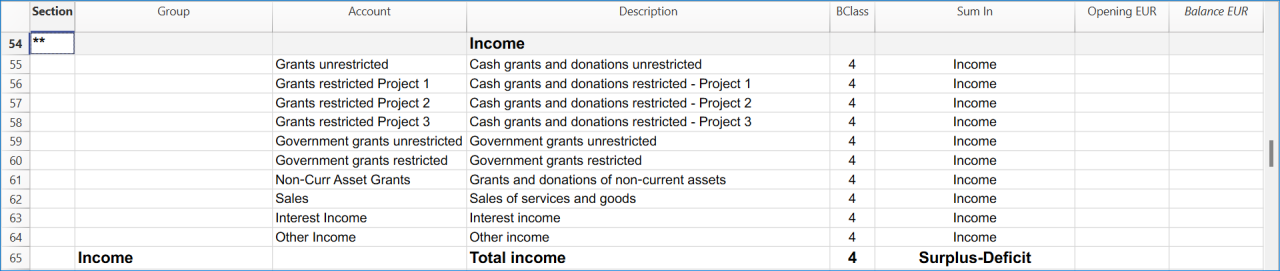
Manage grants and donations in the Income Statement.
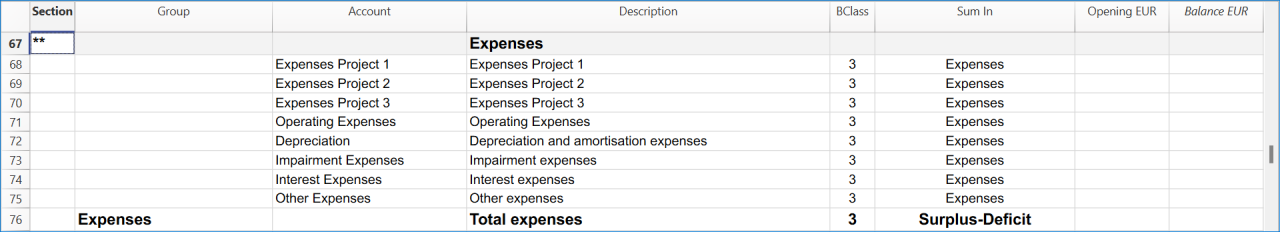
Manage projects expenses and operating expenses in the Income Statement.
Recording transactions by fund
Under INPAS, the organisation must identify and track its funds. In this Banana Accounting+ template, funds are defined as segments (:Fund A, :Fund B, :Fund C), projects are tracked through cost centres CC2, and donors through cost centres CC3.
In the Transactions table, add the fund segment after the account code. In the CC2 and CC3 columns, enter the cost centre name without its leading punctuation.
Receiving a restricted donation without delivery obligations
A donor contributes EUR 1'000 to Fund A for Project 1. The donation has a restriction on its use but no enforceable delivery obligation. It is therefore recognised as revenue when received:
- Date: 2024-01-15
- Description: Fund A restricted donation without delivery obligations
- Debit account: Bank:Fund A
- Credit account: Grants restricted Project 1:Fund A
- Amount: 1000.00
- CC2: Project 1
- CC3: Benjamin Foster
Paying expenses for Fund A
The organisation pays EUR 300 for costs incurred in Project 1:
- Date: 2024-01-22
- Description: Fund A project expense paid by bank
- Debit account: Expenses Project 1:Fund A
- Credit account: Bank: Fund A
- Amount: 300.00
- CC2: -Project 1
The income of EUR 1,000 and the expense of EUR 300 result in a surplus of EUR 700 attributable to Fund A.
Receiving a grant with delivery obligations
The organisation receives EUR 800 in advance for Fund B. The grant agreement contains clearly defined, enforceable and measurable delivery obligations that have not yet been fulfilled:
- Date: 2024-02-05
- Description: Fund B advance subject to enforceable delivery obligation
- Debit account: Bank:Fund B
- Credit account: Grant oblig. liability:Fund B
- Amount: 800.00
- CC2: Project 2
- CC3: Olivia Reynolds
The amount is initially recognised as a liability, not revenue. Revenue is recognised when or as the relevant delivery obligations are fulfilled.
Checking and reporting fund balances
Use the accounting reports subdivided by segment to analyse transactions attributed to each fund. The balance displayed on an individual segment account card is not necessarily the fund's net asset balance: when the same segment appears on both sides of a transaction, its movements can offset each other.
The restricted fund balances in the Statement of Financial Position must be reconciled with opening balances, income, expenses, other changes and permitted transfers. Additional fund information must be disclosed in the notes to the financial statements, as required by INPAS.
A restriction on the use of a donation does not automatically create a liability.
Get the Statement of Financial Position and the Income Statement
At any time of the year you can create your Balance sheet, which is a financial report of your assets, liabilities and equity and the Profit and Loss statement, which includes income and expenses. You will achieve optimal reports because you can always modify the data until they are perfect. You have the possibility to print out your statements or save them in PDF format.
Complete the documentation using the Excel Template
After preparing the Statement of Financial Position and the Statement of Income and Expenses in Banana Accounting+, use the Excel template to complete the additional financial statements and explanatory notes.
The NPO must ensure that all applicable INPAS requirements are met before declaring compliance with the Standard.
Income & Expenses: INPAS Standard Template
En este artículo
Income & Expenses: INPAS Standard Template
Income & Expenses: INPAS Standard Template
The INPAS International standard Income & Expenses template for associations provides a comprehensive framework for organizing financial transactions and reporting for associations adhering to international standards.
Abrir en Banana WebApp
Abra Banana Contabilidad Plus en su navegador sin necesidad de instalación. Personaliza la plantilla, introduce las transacciones y guarda el archivo en tu ordenador.
Abrir plantilla en WebAppDocumentación de la plantilla
[This page is currently being updated]
The NPO is responsible for ensuring that its financial reports comply with all applicable INPAS requirements. Using the template alone does not guarantee compliance.
INPAS requires accrual-based financial reporting. When using an Income & Expenses accounting template, the NPO must ensure that all relevant assets, liabilities, receivables, payables, accrued income and expenses are correctly recognised and reported in accordance with INPAS.
Recording transactions by fund
In this template, funds are identified using segments (:Fund A, :Fund B, :Fund C). Projects are tracked using cost centres CC2 and donors using cost centres CC3.
For the following examples, add the fund segment only after the code entered in the Category column. Do not also add it after the Account code, as this can result in duplicated amounts on the segment account card.
Receiving a restricted donation without delivery obligations
The organisation receives EUR 1'000 for Fund A and Project 1, with no enforceable delivery obligation:
- Date: 2024-01-15
- Description: Fund A restricted donation without delivery obligations
- Income: 1000.00
- Expenses: leave empty
- Account: Bank
- Category: Grants restricted Project 1:Fund A
- CC2: Project 1
- CC3: Benjamin Foster
Paying expenses for Fund A
The organisation pays EUR 300 for costs incurred in Project 1:
- Date: 2024-01-22
- Description: Fund A project expense paid by bank
- Income: leave empty
- Expenses: 300.00
- Account: Bank
- Category: Expenses Project 1:Fund A
- CC2: -Project 1
- CC3: leave empty
The resulting surplus attributed to Fund A is EUR 700.
Receiving a grant with delivery obligations
The organisation receives EUR 800 in advance for Fund B, before fulfilling the enforceable delivery obligations specified in the grant agreement:
- Date: 2024-02-05
- Description: Fund B advance subject to enforceable delivery obligation
- Income: 800.00
- Expenses: leave empty
- Account: Bank
- Category: Grant oblig. liability:Fund B
- CC2: Project 2
- CC3: Olivia Reynolds
In this example, the Category column refers to a liability account in the Accounts table rather than an income category. The amount is not yet recognised as grant revenue.
Checking fund movements and net assets
Use reports subdivided by segment to analyse income, expenses and relevant assets or liabilities attributed to each fund.
The amount shown on a segment card is not automatically the fund's net asset balance. In the example above, Fund B shows a negative segment balance of EUR 800.00 because the advance is recorded as a liability. This does not represent a deficit in the fund's net assets. The organisation must reconcile the opening and closing balances of each fund using the required accounting information.
Do not record an additional payment from the bank to a restricted-fund account merely to allocate the donation to that fund. This would incorrectly reduce the bank balance without an actual payment.
This template must also be used consistently with accrual-based financial reporting. Additional year-end adjustments and reconciliations may be necessary to prepare financial statements in accordance with INPAS.
Free INPAS Excel Template
En este artículo
Free INPAS Excel Template
Free INPAS Excel Template
The INPAS Excel Template provides nonprofit associations with a complete set of accounting documents aligned with the upcoming INPAS (International Non-Profit Accounting Standard). It includes a chart of accounts and ready-to-use financial statements: Balance Sheet, Statement of Income and Expenses, Statement of Changes in Net Assets, Statement of Cash Flows and Explanatory Notes, all designed to enhance transparency and consistency in financial reporting. The template can be used alongside Banana Accounting+ to easily generate compliant reports. It is based on current INPAS drafts and will be updated after the final release in 2025.
Contabilidad libro de caja para organización sin ánimo de lucro
En este artículo
Contabilidad libro de caja para organización sin ánimo de lucro
Contabilidad libro de caja para organización sin ánimo de lucro
Inicia la gestión contable, de forma clara y transparente, de tu asociación u organización sin ánimo de lucro, Utilizando esta sencilla plantilla apta para cualquier persona, con el método de libro de caja.
Abrir en Banana WebApp
Abra Banana Contabilidad Plus en su navegador sin necesidad de instalación. Personaliza la plantilla, introduce las transacciones y guarda el archivo en tu ordenador.
Abrir plantilla en WebAppTemplate preview
Asociación XX
Contabilidad 2022
Moneda base: USD
Cash Manager
| Grupo | Cuenta | Descripción | Sumar en |
|---|---|---|---|
| 1000 | Efectivo | ||
| Grupo | Categoría | Descripción | Sumar en |
|---|---|---|---|
| RESULTADO OPERATIVO | |||
| INGRESOS | |||
| 4000 | Ventas varias | 4 | |
| 4010 | Pagos de membresía | 4 | |
| 4020 | Donaciones | 4 | |
| 4030 | Otros | 4 | |
| 4 | TOTAL INGRESOS | 00 | |
| GASTOS | |||
| 3000 | Gastos para Proyecto A | 3 | |
| 3005 | Gastos para Proyecto B | 3 | |
| 3010 | Gastos para Proyecto C | 3 | |
| 3025 | Papelería, equipos, limpieza, etc. | 3 | |
| 3030 | Coste postal | 3 | |
| 3035 | Alquiler, electricidad, agua | 3 | |
| 3040 | Teléfono y fax | 3 | |
| 3050 | Publicidad, folletos, imprenta | 3 | |
| 3055 | Reembolso a voluntarios | 3 | |
| 3060 | Tasas y otras licencias | 3 | |
| 3065 | Gastos imprevistos | 3 | |
| 3070 | Gastos menores no registrados | 3 | |
| 3075 | Otros | 3 | |
| 3 | TOTAL GASTOS | 00 | |
| 00 | RESULTADO | ||
| CENTROS DE COSTES Y BENEFICIOS | |||
| Listado de miembros | |||
| ;MA | Montgomery Alexander | TM | |
| ;WB | Weelt Bob | TM | |
| ;JB | Johnson Bill | TM | |
| ;SA | Smith Ada | TM | |
| ;MC | Montgomery Chloe | TM | |
| TM | Total miembros | ||
Contabilidad ingresos y gastos para organización sin ánimo de lucro
En este artículo
Contabilidad ingresos y gastos para organización sin ánimo de lucro
Contabilidad ingresos y gastos para organización sin ánimo de lucro
Inicia la gestión contable, de forma clara y transparente, de tu asociación u organización sin ánimo de lucro. Utilizando esta sencilla plantilla apta para cualquier persona, con el método de ingresos y gastos.
Abrir en Banana WebApp
Abra Banana Contabilidad Plus en su navegador sin necesidad de instalación. Personaliza la plantilla, introduce las transacciones y guarda el archivo en tu ordenador.
Abrir plantilla en WebAppTemplate preview
Asociación XX
Contabilidad 2022
Moneda base: USD
Contabilidad de ingresos y egresos
| Grupo | Cuenta | Descripción | Sumar en |
|---|---|---|---|
| PATRIMONIO | |||
| 1000 | Efectivo | 1 | |
| 1010 | Cuenta Corriente postal | 1 | |
| 1020 | Cuenta Corriente bancaria | 1 | |
| 1100 | Clientes | 1 | |
| 1150 | Impuestos anticipados | 1 | |
| 1300 | Activos transitorios | 1 | |
| 1400 | Mobiliario de oficina | 1 | |
| 1500 | Hardware/Software | 1 | |
| 2000 | Proveedores | 1 | |
| 2050 | IVA Automático | 1 | |
| 2060 | IVA Autoridades fiscales | 1 | |
| 2100 | Préstamo bancario c/c | 1 | |
| 2400 | Préstamo bancario a largo plazo | 1 | |
| 2700 | Pasivos transitorios | 1 | |
| 1 | TOTAL | ||
| CENTROS DE COSTES Y BENEFICIOS | |||
| Listado de miembros | |||
| ;MA | Montgomery Alexander | TM | |
| ;WB | Weelt Bob | TM | |
| ;JB | Johnson Bill | TM | |
| ;SA | Smith Ada | TM | |
| ;MC | Montgomery Chloe | TM | |
| TM | Total miembros |
| Grupo | Categoría | Descripción | Sumar en |
|---|---|---|---|
| RESULTADO OPERATIVO | |||
| INGRESOS | |||
| 4200 | Ventas varias | 4 | |
| 4400 | Pagos de membresía | 4 | |
| 4500 | Donaciones | 4 | |
| 4 | TOTAL INGRESOS | 00 | |
| GASTOS | |||
| 3000 | Gastos para Proyecto A | 3 | |
| 3001 | Gastos para Proyecto B | 3 | |
| 3002 | Gastos para Proyecto C | 3 | |
| 3005 | Bienes adquiridos para reventa | 3 | |
| 3010 | Alquiler, electricidad, agua | 3 | |
| 3020 | Impuestos | 3 | |
| 3050 | Seguros | 3 | |
| 3070 | Honorarios | 3 | |
| 3080 | Limpieza | 3 | |
| 3090 | Material de oficina | 3 | |
| 3100 | Teléfono | 3 | |
| 3110 | Coste postal | 3 | |
| 3130 | Imprenta y publicidad | 3 | |
| 3140 | Intereses negativos bancarios | 3 | |
| 3150 | Comisiones Banco y cuentas corrientes | 3 | |
| 3160 | Depreciación mobiliario | 3 | |
| 3170 | Otros | 3 | |
| 3 | TOTAL GASTOS | 00 | |
| 00 | RESULTADO | ||
Contabilidad partida doble para organización sin ánimo de lucro
En este artículo
Contabilidad partida doble para organización sin ánimo de lucro
Contabilidad partida doble para organización sin ánimo de lucro
Inicia la gestión contable, de forma clara y transparente, de tu organización o asociación sin ánimo de lucro. Utilizando esta sencilla plantilla apta para cualquier persona, y con el método de partida doble.
Abrir en Banana WebApp
Abra Banana Contabilidad Plus en su navegador sin necesidad de instalación. Personaliza la plantilla, introduce las transacciones y guarda el archivo en tu ordenador.
Abrir plantilla en WebAppTemplate preview
Asociación XX
Contabilidad 2022
Moneda base: USD
Partida doble
| Grupo | Cuenta | Descripción | Sumar en | Gr1 |
|---|---|---|---|---|
| BALANCE GENERAL | ||||
| ACTIVOS | ||||
| 1000 | Efectivo | 1 | ||
| 1010 | Cuenta Corriente postal | 1 | ||
| 1020 | Cuenta Corriente bancaria | 1 | ||
| 1100 | Clientes | 1 | ||
| 1150 | Impuestos anticipados | 1 | ||
| 1300 | Activos transitorios | 1 | ||
| 1400 | Mobiliario de oficina | 1 | ||
| 1500 | Hardware/Software | 1 | ||
| 1 | TOTAL ACTIVOS | 00 | 1 | |
| PASIVOS | ||||
| 2000 | Proveedores | 2 | ||
| 2100 | Préstamo bancario c/c | 2 | ||
| 2400 | Préstamo bancario a largo plazo | 2 | ||
| 2700 | Pasivos transitorios | 2 | ||
| 2800 | Capital inicial | 2 | ||
| 2900 | Beneficios o pérdidas acumuladas | 2 | ||
| 299 | Ganancia o pérdida del año en curso | 2 | 1 | |
| 2 | TOTAL PASIVOS | 00 | 1 | |
| 1 | ||||
| CUENTA DE RESULTADOS | ||||
| INGRESOS | ||||
| 4200 | Ventas varias | 4 | ||
| 4400 | Cuotas de membresía | 4 | ||
| 4500 | Donaciones | 4 | ||
| 4 | TOTAL INGRESOS | 02 | ||
| GASTOS | ||||
| 3000 | Gastos para Proyecto A | 3 | ||
| 3001 | Gastos para Proyecto B | 3 | ||
| 3002 | Gastos para Proyecto C | 3 | ||
| 3005 | Bienes adquiridos para reventa | 3 | ||
| 3010 | Alquiler, electrícidad, agua | 3 | ||
| 3020 | Impuestos | 3 | ||
| 3050 | Seguros | 3 | ||
| 3070 | Honorarios | 3 | ||
| 3080 | Limpieza | 3 | ||
| 3090 | Material de oficina | 3 | ||
| 3100 | Teléfono | 3 | ||
| 3110 | Coste postal | 3 | ||
| 3130 | Imprenta y publicidad | 3 | ||
| 3140 | Intereses negativos bancarios | 3 | ||
| 3150 | Comisiones banco y cuentas corrientes | 3 | ||
| 3160 | Depreciación mobiliario | 3 | ||
| 3170 | Otros gastos | 3 | ||
| 3 | TOTAL GASTOS | 02 | 1 | |
| 02 | Beneficio(-) Pérdida(+) de la cuenta de resultados | 299 | 1 | |
| 00 | La diferencia debe ser = 0 (nulo) | |||
| CENTROS DE COSTES Y BENEFICIOS | ||||
| Listado de miembros | ||||
| ;MA | Montgomery Alexander | TM | 1 | |
| ;WB | Weelt Bob | TM | ||
| ;JB | Johnson Bill | TM | ||
| ;SA | Smith Ada | TM | ||
| ;MC | Montgomery Chloe | TM | ||
| TM | Total miembros |
Contabilidad multidivisa para organización sin ánimo de lucro
En este artículo
Contabilidad multidivisa para organización sin ánimo de lucro
Contabilidad multidivisa para organización sin ánimo de lucro
Inicia la gestión contable, de forma clara y transparente, de tu organización o asociación sin ánimo de lucro. Utilizando esta sencilla plantilla apta para cualquier persona, incluso con contabiildad multidivisa.
Abrir en Banana WebApp
Abra Banana Contabilidad Plus en su navegador sin necesidad de instalación. Personaliza la plantilla, introduce las transacciones y guarda el archivo en tu ordenador.
Abrir plantilla en WebAppTemplate preview
Asociación XX
Contabilidad 2022
Moneda base: USD
Partida doble con multi-moneda
| Grupo | Cuenta | Descripción | Moneda | Sumar en | Gr1 |
|---|---|---|---|---|---|
| BALANCE GENERAL | |||||
| ACTIVOS | |||||
| 1000 | Efectivo | USD | 1 | ||
| 1010 | Cuenta Corriente postal | USD | 1 | ||
| 1020 | Cuenta Corriente bancaria | USD | 1 | ||
| 1025 | Banco CHF | CHF | 1 | ||
| 1100 | Clientes | USD | 1 | ||
| 1150 | Impuestos anticipados | USD | 1 | ||
| 1300 | Activos transitorios | USD | 1 | ||
| 1400 | Mobiliario de oficina | USD | 1 | ||
| 1500 | Hardware/Software | USD | 1 | ||
| 1 | TOTAL ACTIVOS | 00 | 1 | ||
| PASIVOS | |||||
| 2000 | Proveedores | USD | 2 | ||
| 2100 | Préstamo bancario c/c | USD | 2 | ||
| 2400 | Préstamo bancario a largo plazo | USD | 2 | ||
| 2700 | Pasivos transitorios | USD | 2 | ||
| 2800 | Capital inicial | USD | 2 | ||
| 2900 | Beneficios o pérdidas acumuladas | USD | 2 | ||
| 290 | Ganancia o pérdida del año en curso | 2 | 1 | ||
| 2 | TOTAL PASIVOS | 00 | 1 | ||
| 1 | |||||
| CUENTA DE RESULTADOS | |||||
| INGRESOS | |||||
| 4200 | Ventas varias | USD | 4 | ||
| 4400 | Cuotas de membresía | USD | 4 | ||
| 4500 | Donaciones | USD | 4 | ||
| 4600 | Diferencias de tipo de cambio | USD | 4 | ||
| 4 | TOTAL INGRESOS | 02 | |||
| GASTOS | |||||
| 3000 | Gastos para Proyecto A | USD | 3 | ||
| 3001 | Gastos para Proyecto B | USD | 3 | ||
| 3002 | Gastos para Proyecto C | USD | 3 | ||
| 3005 | Bienes adquiridos para reventa | USD | 3 | ||
| 3010 | Alquiler, electricidad, agua | USD | 3 | ||
| 3020 | Impuestos | USD | 3 | ||
| 3050 | Seguros | USD | 3 | ||
| 3070 | Honorarios | USD | 3 | ||
| 3080 | Limpieza | USD | 3 | ||
| 3090 | Material de oficina | USD | 3 | ||
| 3100 | Teléfono | USD | 3 | ||
| 3110 | Coste postal | USD | 3 | ||
| 3130 | Imprenta y publicidad | USD | 3 | ||
| 3140 | Intereses negativos bancarios | USD | 3 | ||
| 3150 | Comisiones Banco y cuentas corrientes | USD | 3 | ||
| 3160 | Depreciación mobiliario | USD | 3 | ||
| 3170 | Otros gastos | USD | 3 | ||
| 3 | TOTAL GASTOS | 02 | 1 | ||
| 02 | Beneficio(-) Pérdida(+) de la cuenta de resultados | 290 | 1 | ||
| 00 | La diferencia debe ser = 0 (nulo) | ||||
| CENTROS DE COSTES Y BENEFICIOS | |||||
| Listado de miembros | |||||
| ;MA | Montgomery Alexander | USD | TM | 1 | |
| ;WB | Weelt Bob | USD | TM | ||
| ;JB | Johnson Bill | USD | TM | ||
| ;SA | Smith Ada | USD | TM | ||
| ;MC | Montgomery Chloe | USD | TM | ||
| TM | Total miembros |
| Referencia Moneda | Moneda | Texto |
|---|---|---|
| USD | EUR | Euro |
| USD | CHF | Francos Suizos |